The taxi stand deserves a place in Brad Marshall’s career history. Leaving a private equity conference in New York, he met a woman who had attended the same event. She became his wife. He moved to the United States about three months later. Asked whether she was a big part of the decision, he supplied an answer short enough to fit on a cab receipt: “It was the only reason.”
Finance likes to explain careers through calculated decisions, carefully chosen employers and an early appreciation of a promising market. Marshall’s version allows room for a person waiting outside. He had grown up outside Ottawa, studied economics at Queen’s, worked in Vancouver and earned an MBA at McGill. Then a conversation changed his address. The professional consequences would take considerably longer to unfold.
Today he is based in New York, serving as Blackstone’s global head of private credit strategies and chairman and chief executive of both Blackstone Private Credit Fund, known as BCRED, and Blackstone Secured Lending Fund, or BXSL. His work concerns an unusually consequential kind of waiting: advancing money to a business, understanding what can happen to it, and collecting what is owed.
Before the loan book, a software company
Marshall’s early résumé contains a detail that disappears beneath the current titles. He co-founded a microchip verification software company and served as its chief financial officer. Before he became a lender to other businesses, he had been responsible for the finances of one he helped start. The product was technical; his job was financial. Both belong in the story.
He later helped develop a private equity funds business for TAL Global, a Canadian asset management division of CIBC. At RBC, his responsibilities included fixed income research and business development for private equity funds. These were different vantage points on the same practical problem: how money reaches a company, and how an investor gets access to the opportunity.
The sequence gives his career more texture than a straight ascent through one institution. A software venture, fund development and credit research ask different questions of a business. A founder has to make the operation work. A researcher has to decide what the numbers mean. A fund business has to connect an investment with people prepared to own it. Marshall had encountered all three before the present job.
A small corner of finance gets a bigger table
Marshall dates the beginnings of Blackstone’s private credit business to 2005. In his account of that period, privately financed borrowers were often smaller businesses or more complicated credits that could not obtain public financing. Private capital providers represented only about 5 percent of US leveraged finance. The business occupied a comparatively small corner of a much larger room.
Over time, the kinds of companies choosing that room changed. In a 2023 discussion with Jonathan Bock, Marshall described an acceleration in multibillion-dollar private financings beginning in 2021. Borrowers increasingly chose private arrangements. He argued that larger companies could offer a broader business mix, experienced management and the backing of private equity sponsors with resources to help through difficult periods.
His argument puts the borrower ahead of the fashionable label attached to the asset class. A large cheque still needs a business capable of servicing it. Size can provide advantages, but his stated requirements include the sector, the position in the capital structure and the loan terms. A large borrower with the wrong economics remains a borrower with the wrong economics.
By June 2023, Blackstone was describing private credit as 24 percent of that addressable sub-investment-grade market in 2022, up from 5 percent in 2005. Its explanation of a defensive lending approach was conditional: select strong businesses, occupy a senior position and put protections into the agreement. The fine print had a starring role. In lending, the fine print usually insists on one.
Two doors for individual investors
The investor side of Marshall’s work became especially visible in 2021. BCRED launched that January. BXSL began trading on the New York Stock Exchange on October 28. Both are business development companies, a structure used to invest in businesses, including through loans. They offer different ways for individuals to participate in portfolios managed by a large credit organization.
The distinction matters. BXSL has shares that trade on an exchange. BCRED’s shares do not trade in a market; investors instead face the terms of the fund’s repurchase arrangements. The same broad investment territory can therefore produce very different experiences when someone wants to leave. An investor’s calendar belongs in the discussion alongside a borrower’s repayment schedule.
In January 2026, BCRED reached its fifth anniversary. Its year-end letter reported approximately $82 billion in total investments as of December 31, 2025. That figure describes the fund’s investments, rather than Marshall’s personal wealth or every asset under his supervision. The scale is striking enough without asking the number to do three jobs at once.
Opening a market to more people also makes the obligations more public. The August 2026 BCRED tender filing offered to purchase approximately 5 percent of outstanding shares as measured at June 30, subject to its conditions. Access and exit have separate mechanics. A profile of the executive who helped expand access has to keep both in view.
The banker in the next chair
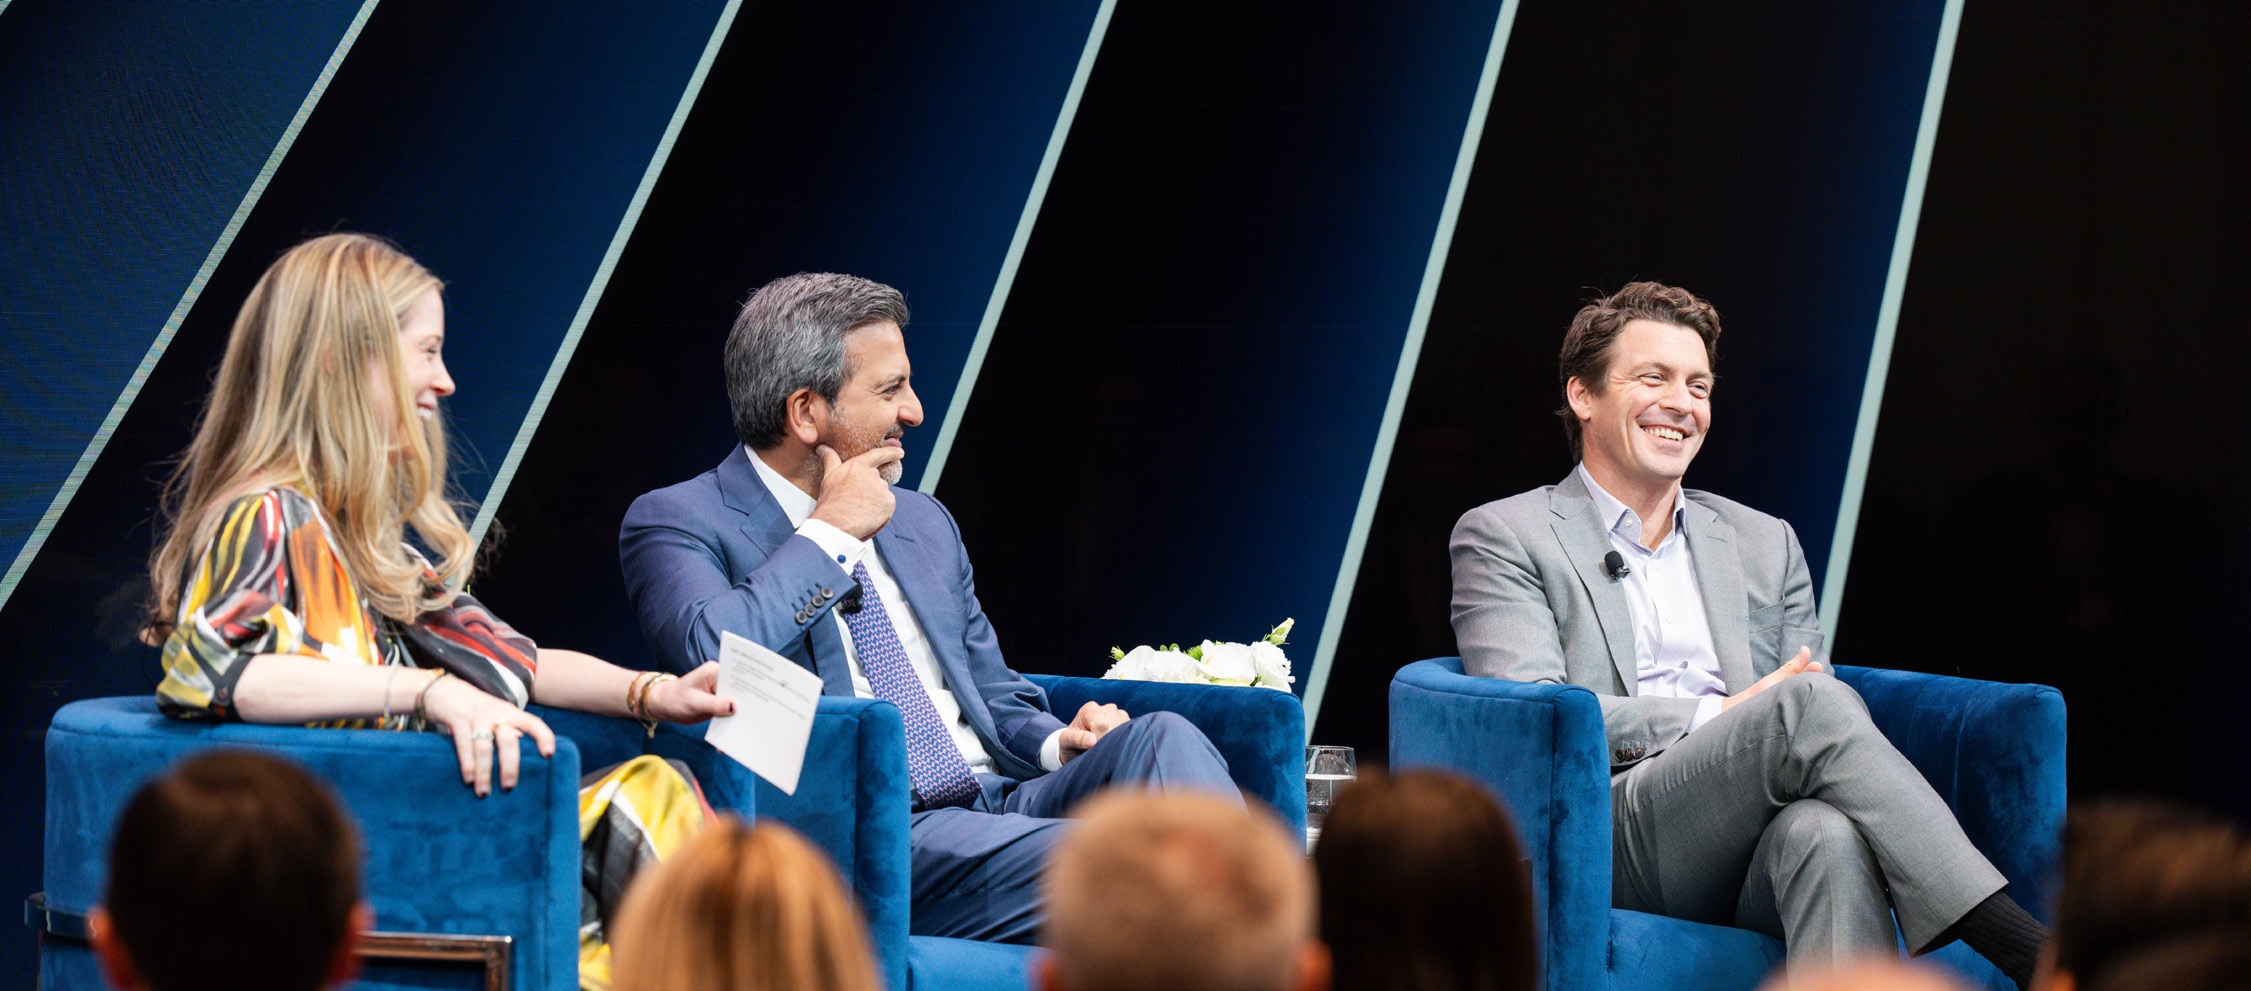
At the investor event recapped in December 2023, Marshall appeared with Emily Yoder, Blackstone’s head of strategic relationships, and Mohit Assomull, Morgan Stanley’s head of capital markets. The photograph offers a useful corrective to the idea that private lenders and banks occupy wholly separate worlds. Here they are, sharing a stage and discussing how financing gets done.
Marshall described the value of being able to offer both private and liquid-market solutions when a bank or sponsor calls. Sometimes the best route is unclear at the beginning. Assomull emphasized the usefulness of a partner capable of responding quickly and committing significant capital. Their conversation concerned the practical business of matching a client with financing that fits.
Marshall’s January 2023 promotion had also brought Bock into the leadership of the two BDCs. Marshall called him a longtime friend. The pairing joined a direct-lending executive with someone who had studied the BDC industry as an analyst and led Barings BDC. Relationships recur in this career, from the conference encounter to the colleagues with whom he built the lending business.
“Investing in larger companies has a lot of intuitive advantages”BRAD MARSHALL · OCTOBER 2023
After the cheque clears
Marshall has publicly highlighted another part of the job: what happens after Blackstone lends. In a LinkedIn post featuring Enstructure, he discussed giving credit portfolio companies access to value creation opportunities also available to Blackstone’s private equity-backed businesses. His emphasis was on partnering with a company through its next stage of growth.
That is a revealing choice of subject for a lender. The first agreement establishes the financial relationship; the work afterward concerns the operating business that must support it. A loan portfolio is composed of companies with customers, expenses and decisions to make. An interest payment arrives because those activities have produced enough cash, or because the borrower has found another way to fund it.
The technology thread also reappears at a different scale. In May 2024, CoreWeave announced a $7.5 billion debt financing facility led by Blackstone-managed funds, with Magnetar as co-lead investor. The financing was intended to expand the company’s high-performance computing fleet to meet existing contracts. Marshall spoke publicly about supporting CoreWeave’s growth.
CoreWeave’s announced debt facility, May 2024. Led by Blackstone-managed funds with Magnetar as co-lead investor; other investors participated.
The amount was a facility involving a group of investors, rather than a cheque written personally by Marshall or a sum attributable solely to either BDC. Its place in his story is the evolution of the work: the former software-company CFO now discussing capital for computing infrastructure. Machines and code have remained part of the landscape, even as his responsibility has changed.
The return trip, and the next quarter
When Blackstone opened its Toronto office in 2023, Marshall posted about celebrating with Jon Gray, Kathleen McCarthy Baldwin, Nadeem Meghji and Janice Lin. He welcomed a larger presence for Canadian companies and clients, including individuals. He also enjoyed showing colleagues around downtown Toronto, where he said his career had started. The public executive briefly became the local guide.
There is some playfulness in his public voice, too. Sharing Blackstone’s 2023 holiday video, he compared the economy to Taylor Swift and invoked an “Alternatives Era.” Even a credit executive can borrow a pop reference. It costs considerably less than borrowing money, and the repayment terms are more forgiving.
By summer 2026, his formal responsibilities had changed again. Bock resigned as BCRED’s co-CEO effective July 20. An August filing identifies Marshall as chief executive, and Blackstone’s current biography gives him the CEO title at both funds. The shared leadership arrangement introduced in 2023 had become a sole chief executive role.
The quarterly numbers supply a less celebratory measure of the job. In May, Marshall acknowledged that BXSL’s non-accruals had increased from historically low levels. In August, he reported no new assets placed on non-accrual during the second quarter, with more than $300 million in new investment activity and more than $700 million in repayments. These describe different quarters; neither erases the other.
A non-accrual is a reminder that an anticipated payment can become a problem requiring attention. Repayments matter just as much as new commitments. For an executive associated with the growth of private lending, the enduring test remains what happens after the money goes out. Every announcement has a later date attached to it, when the business must perform and the account must be settled.
Marshall’s career began far from his present titles and crossed a border for a personal reason. It has since followed a financing market into larger companies, new investor structures and computing infrastructure. The taxi stand explains the move. The years afterward explain the work. Some waits end with a conversation; the ones on his balance sheets need to end with money coming back.