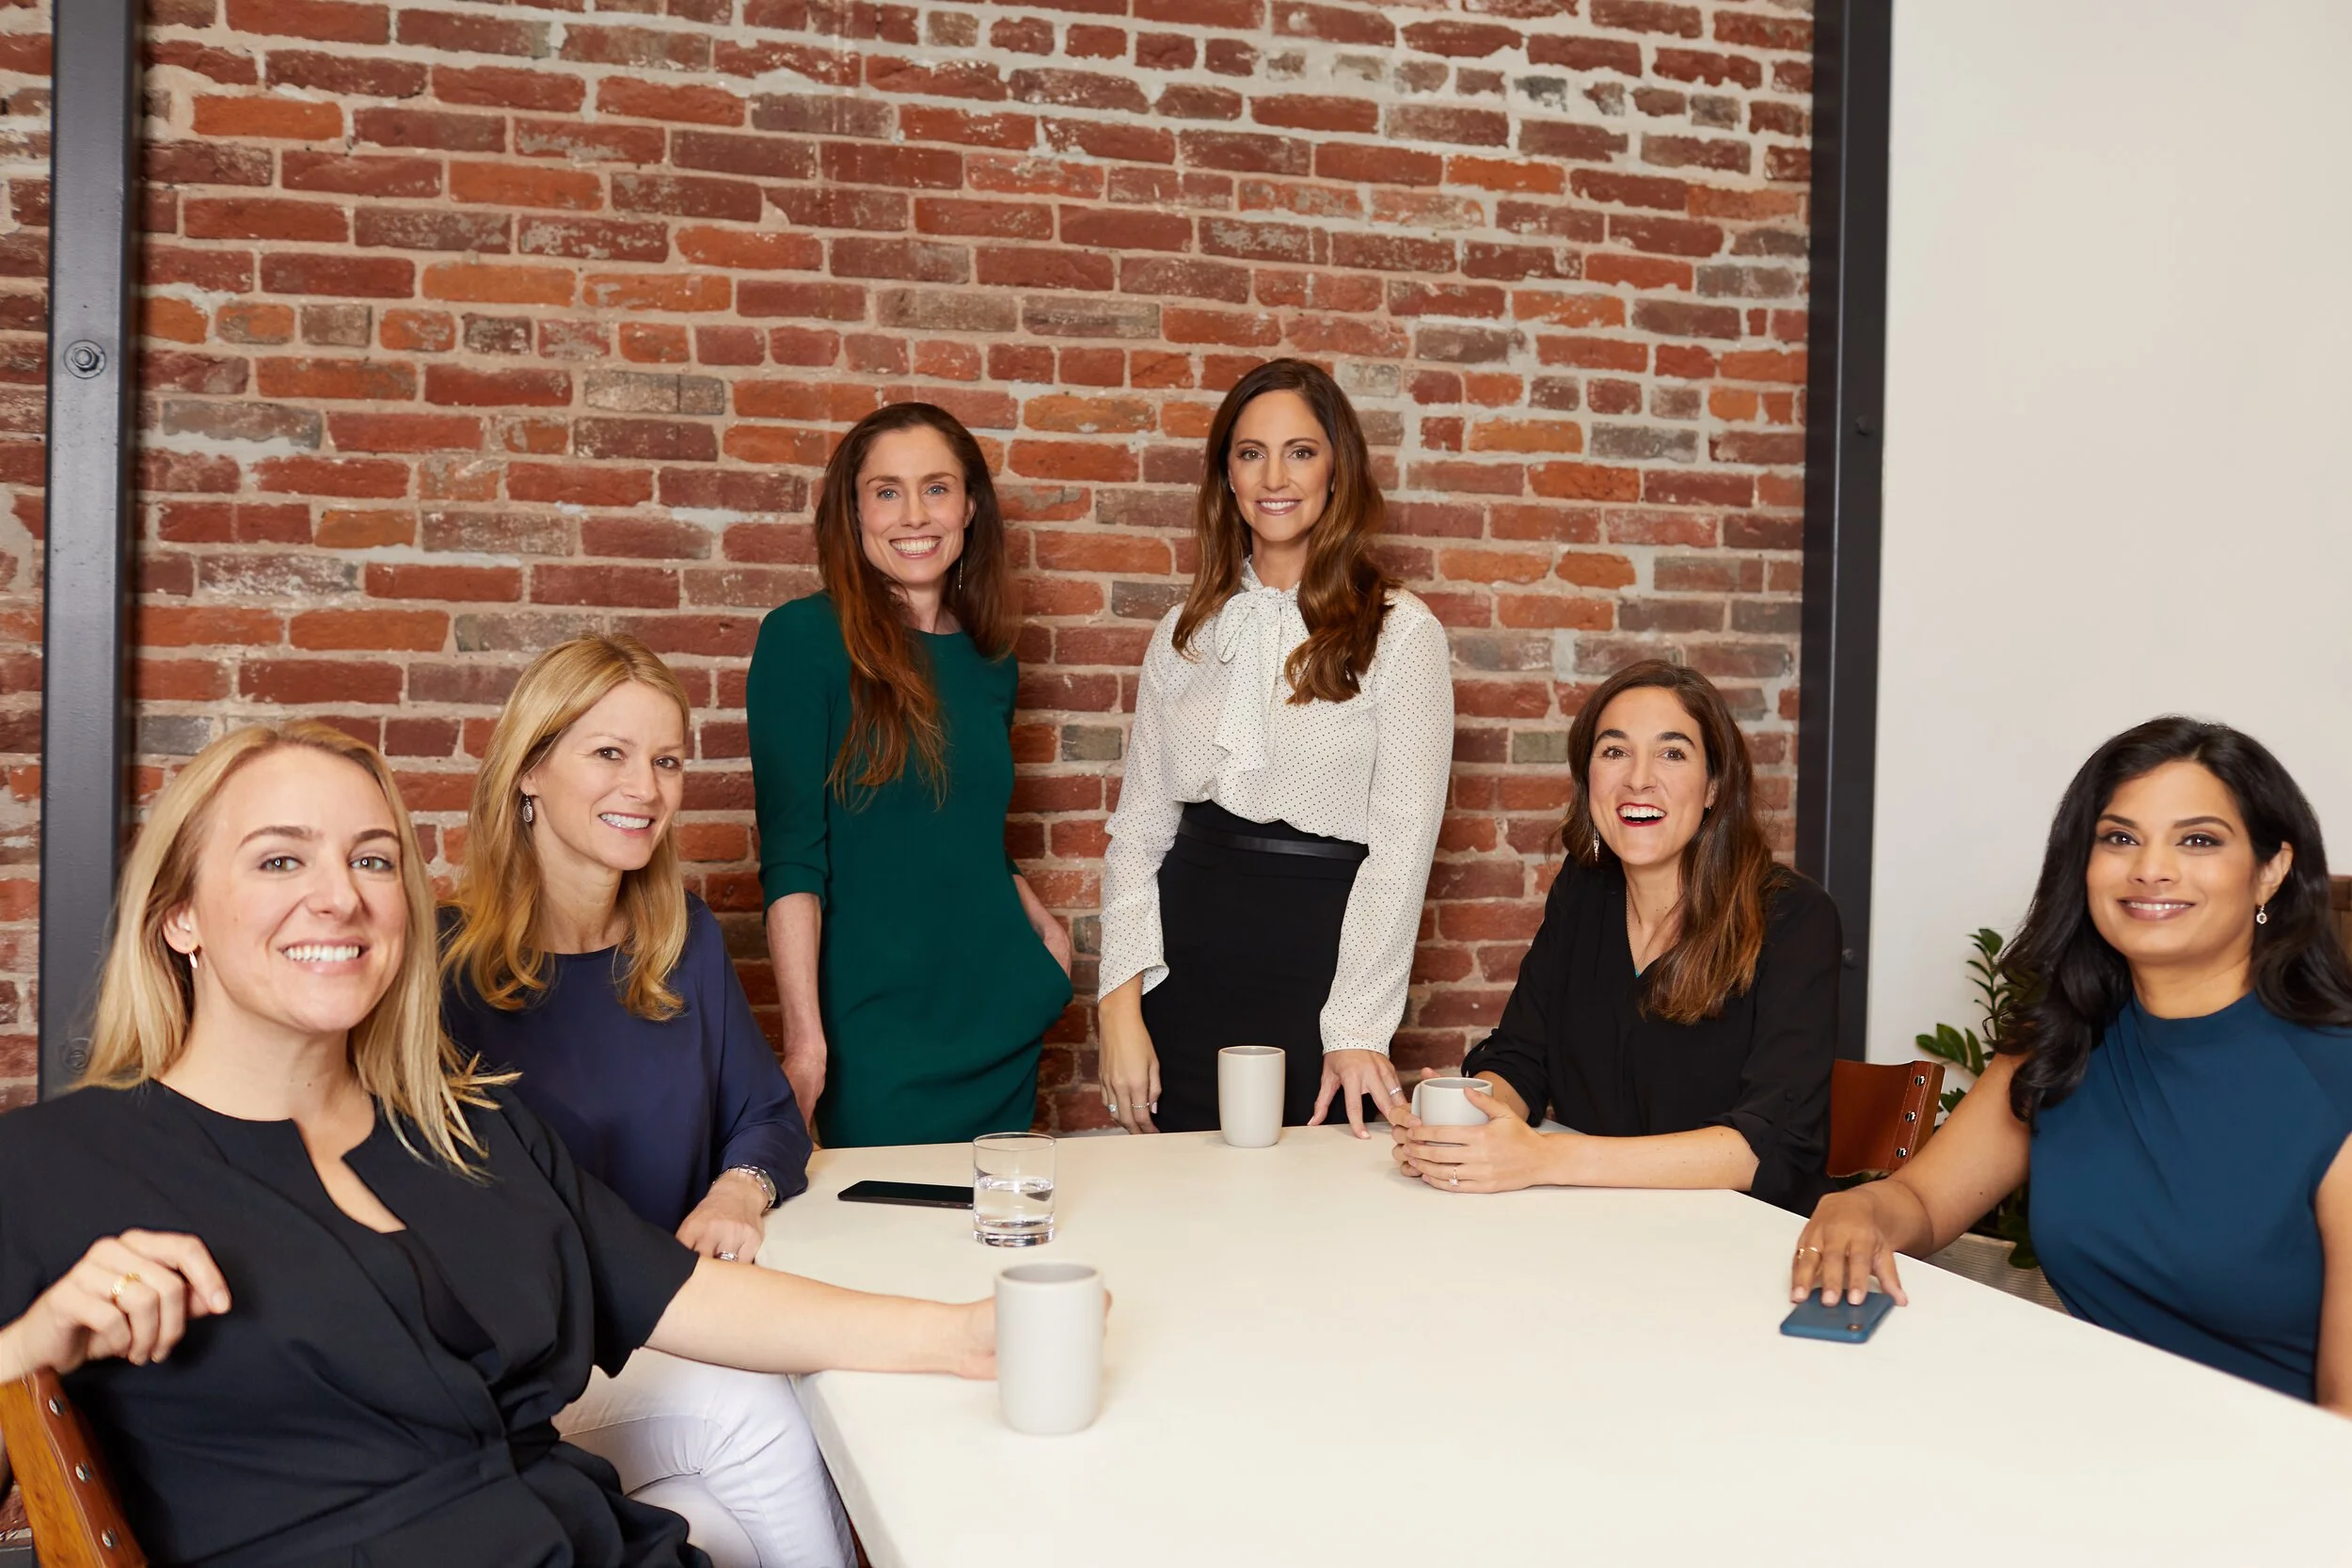
The conversation began over cocktails after Twitter’s IPO. Six colleagues had seen a company become a source of personal possibility. Now they were comparing notes about angel investing. They had money to put at risk, founders in their orbit and different kinds of experience to offer. In 2015, Jana Messerschmidt, Jessica Verrilli, Chloe Sladden, Katie Jacobs Stanton, April Underwood and Vijaya Gadde formed #ANGELS. The question behind their checks would eventually become larger than which startup to back: who gets the resources to do this again?
- Six investors make independent decisions with their own capital.
- Founders get access to a shared network of experienced operators.
- The Gap Table work asks who captures startup wealth.
Six checkbooks. One useful circle.
To understand the business, start with the checkbook. #ANGELS describes a collective in which each member chooses her investments and supplies her own money. A company might receive backing from all six, but usually only some participate. Support travels more freely than capital. The group says, “we work as a team to support all of the founders in our portfolio.” A founder’s relationship can therefore extend beyond the person who signed.
The mix of skills matters. Underwood worked in product at Twitter and later became Slack’s chief product officer. Verrilli worked in corporate development and strategy; Sladden built media partnerships. Messerschmidt brought engineering and business development experience, Stanton a background spanning marketing and international expansion, and Gadde legal expertise. These are people familiar with the decisions that arrive after a financing announcement, when a team still has to build, hire and negotiate.
The price of joining the risk
In a September 2019 interview, Stanton described $25,000 as the most common check per person, with some at $50,000 and a high of $200,000. Those figures belong to that moment. They illustrate the model’s scale: personal commitments that could accompany larger investors. Most investments, she said, had been seed or Series A, although relationships sometimes opened doors to later rounds.
The economic exchange is investment capital for a stake in a company’s future. Founders are the recipients of funding and support. Other angels and seed funds offer alternatives; the distinctive proposition here is the particular combination of operators and their connections. Money has many suppliers. Advice from someone who has faced your problem is harder to compare on a spreadsheet. For a founder, the useful question is which experience the company actually needs.
That makes fit a practical matter. A team facing a product decision may value one member’s background; another may need help thinking through partnerships or expansion. The collective’s structure allows those interests to overlap without requiring every investor to share the same conviction. For founders, understanding who is investing and who might help is part of understanding the offer. Six names on a website do not mean six identical commitments.
The missing column was ownership
As the collective invested, it also questioned the industry’s diversity arithmetic. Hiring, management and board representation were being counted. Ownership needed attention too. The group called this problem The Gap Table in February 2018. The capitalization table records who owns a startup. If a company produces a windfall, that document helps determine who can finance another company, become an investor or afford a career gamble.
Carta supplied a way to test the concern. Its 2018 analysis covered more than 6,000 companies, nearly 180,000 employees and over 15,000 founders. #ANGELS collaborated on methodology without receiving access to Carta’s underlying data. In the combined founder and employee population, women represented 33% of people but held 9% of equity value. Counting people and counting their ownership produced very different pictures.
A third of the people.
A fraction of the ownership.
The findings require care. This was a sample of Carta companies, tilted toward early-stage businesses. Gender was inferred from names, excluded nonbinary identities and could not be assigned to every shareholder. The results identified a disparity; they did not establish a single cause. Still, a salary-only discussion could leave a substantial part of startup compensation unexamined. The practical correction was to put equity into the conversation.
For an employer, this changes the questions at an offer review. A headcount target tells you who enters the building. It does not tell you how ownership is distributed among the people inside. The collective’s argument invites founders to examine the second question explicitly, including who joins early and who gets access to ownership. That is a more demanding exercise than presenting a hiring percentage, because it asks a company to look at how opportunity accumulates over time.
The dinner had a second act
Another part of the work arrived almost accidentally. “We didn’t set out to do events,” the collective wrote in 2020. Yet small gatherings proved useful enough to keep holding. By then, the group reported more than two dozen events. Its invitation spreadsheet became a resource for finding candidates and introducing trusted operators to angel opportunities. The guest list kept working after everyone went home.
The subjects widened as participants’ needs became clearer. #ANGELS hosted a crypto introduction with Andreessen Horowitz in 2018, and its later account described a negotiation summit with Lightspeed and Carta. A 25-person maternity leave salon addressed another practical problem: running an organization while preparing to step away from it. Community work grew from listening to what people wanted help discussing.
An invitation can open a conversation. Ownership can finance the next one.
A network you can put to work
By its first six years, the collective described backing more than 100 startups, including Airtable, Coinbase, Instacart and Vanta. Those names show range, rather than a single product niche. They also demand a distinction: a list of recognizable companies does not reveal investment prices, ownership stakes or realized returns. The portfolio demonstrates participation across businesses; it does not supply a public performance calculation.
In 2021, #ANGELS moved some of its conversations into a podcast. Its launch introduced founder interviews, including Heather Fernandez of Solv Health; the archive also includes Amy Chang discussing her path into product and company building. That gives readers outside the investment circle something useful: access to operating stories without needing a place at dinner.
The parts worth copying are concrete. Review ownership alongside salary. Bring a small group together around a problem people actually share. Keep track of who can help whom. Replicating the investment model asks more: personal capital, patience with uncertain outcomes and experience founders find useful. A circle of friends cannot manufacture those conditions. But an employer can start examining its equity practices before anyone writes an angel check.