The problem arrives at the veterinary checkout. A dog has received treatment. An owner has insurance. Yet someone still needs to produce the money before reimbursement arrives. A policy can solve the eventual expense while leaving the immediate bill untouched. Trupanion has spent years building around that awkward interval.
- Medical insurance for cats and dogs, with unlimited eligible payouts.
- Participating hospitals can receive payment directly at checkout.
- Per-condition deductibles, exclusions and changing premiums still matter.
The money has to arrive first
Consider an illustrative $5,000 bill consisting entirely of eligible expenses, with the deductible already satisfied. At 90% coverage, the insurer’s share is $4,500. Under reimbursement, the owner may initially need all $5,000. With approved direct payment, the owner needs $500. The final allocation is identical. The amount needed that afternoon is very different.
Trupanion calls its system VetDirect Pay. Hospitals using the software can submit the invoice and receive the covered portion directly. The company reported in August 2026 that more than 11,000 North American hospitals used its Veterinary Portal, with 85% of direct-to-practice payments processed in seconds. That qualification matters: quick payment is common within that process, rather than guaranteed for every claim.
The dependency is wonderfully unglamorous. The hospital must participate and accept direct payment. Otherwise, the owner can still seek reimbursement, but the cash-flow advantage disappears. Before an emergency, checking the actual clinic is more useful than admiring a feature list.
The idea predates the software. Founder Darryl Rawlings traces it to losing his family’s young dog when they could not afford surgery. He began building the business in 1998; his own dog Monty became its first insured pet in 2000. The company expanded into the United States in 2008. It is a personal origin for a problem that eventually required insurance capital, hospital relationships and a lot of invoices.
A deductible with a memory
The flagship North American policy has another distinctive mechanism: a lifetime deductible for each condition. Once the deductible for an eligible condition has been met, it does not reset every January for that condition, provided coverage continues under the policy’s terms. A chronic illness can therefore produce a different long-run calculation from an annual-deductible policy.
There is a catch hiding in perfectly ordinary language: “each condition.” Several unrelated problems can mean several deductibles. Unlimited eligible payouts also leave the owner’s coinsurance and excluded expenses intact. Standard coverage excludes routine wellness and pre-existing conditions; examination fees and taxes can be excluded too. Local policies and optional riders change the details.
Customers buy protection against unexpected medical expense. Veterinary teams gain a payment route that can make treatment conversations easier. The underlying expertise combines underwriting, claims handling, veterinary relationships and software. Trupanion belongs in the pet-insurance market alongside companies such as Pets Best, Embrace and Fetch; savings remain an alternative for owners able to absorb the risk.
“We continue to execute on the priorities that matter most”
Margi Tooth / CEO and President / August 2026
The forecast that broke
Insurance has an inconvenient property: the product’s cost becomes clear after its price has been set. Trupanion learned this painfully when veterinary inflation accelerated. Its 2023 shareholder letter said the company had planned for 12% veterinary inflation and experienced 15%. The first thing to give way was the pricing assumption.
The letter estimated a $72 million cumulative negative cash impact across 2022 through 2024 from the pricing miss and falling short of its subscription margin target. Part of that figure was a forecast for 2024. It was management’s estimate of a shortfall, not a separately reported $72 million accounting loss.
The response was to raise rates and restrain acquisition spending while repairing margins. Its subsequent shareholder letter acknowledged the consequence: slower pet growth and fading brand presence. Recruiting owners into underpriced policies could mean confronting them with steep increases at renewal. Selling faster would have multiplied that problem.
This is the uncomfortable business behind the friendly animals. The company charges recurring premiums and assumes insurance risk through its insurance operations. Its 2025 subscription average revenue per pet reached $80.79 a month, versus $72.98 in 2024. Those are company averages across subscription pets, not quotations for a particular puppy, and certainly not promises of a fixed lifetime price.
A bigger business, two different directions
Full-year revenue reached $1.439 billion in 2025. Net income was $19.4 million, following a $9.6 million loss in 2024. By June 2026, subscription enrollment was up 5% year over year, while total enrollment, including the other-business segment, was down 2%. A growing core and a shrinking overall pet count can coexist.
Distribution helps explain the shape of the company. Territory Partners work with veterinary hospitals; members refer other owners; alliances extend its reach. Aflac’s 2020 investment supplied $200 million in gross equity capital alongside a distribution agreement. Chewy and State Farm also appear among its partners. This is an insurer with several routes to customers.
In August 2026, an integration with Digitail put claims, pre-approval requests and payment posting into a practice-management workflow. It addresses a small operational nuisance with considerable consequences: entering information again in another system. Hospital staff already have enough screens.
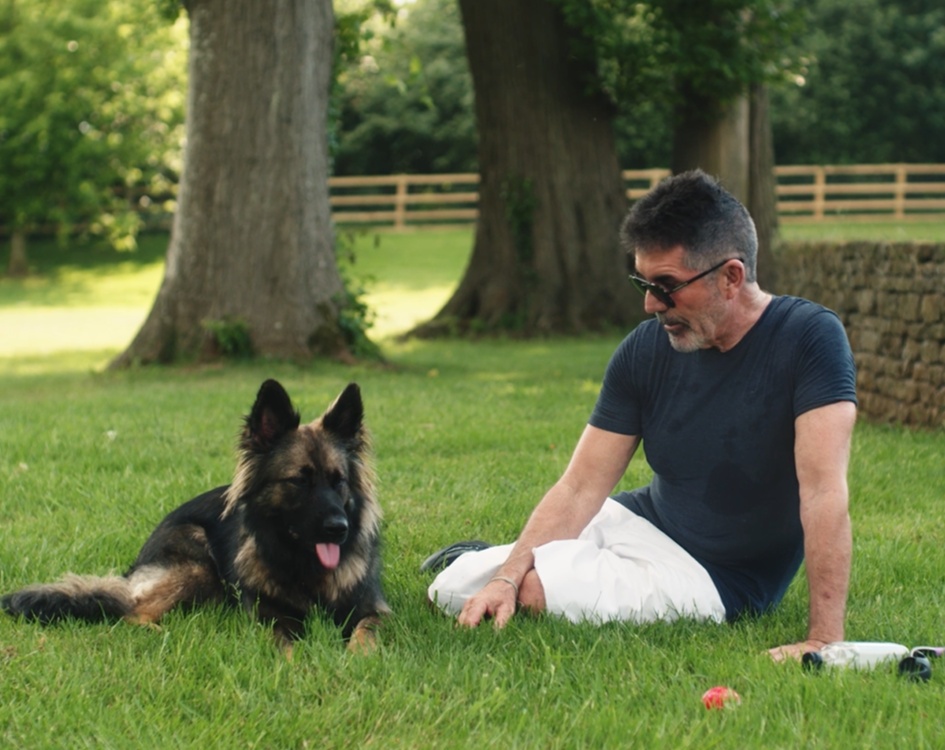
The October campaign with Simon Cowell takes the opposite route, reaching owners before they enter a clinic. Trupanion said he had insured four dogs before joining the partnership. Celebrity attention can introduce the question; hospital participation and policy terms determine the answer.
Copy the sequence
For another business, the useful lesson is to examine the order in which money changes hands. Where must a customer advance cash? Where does a provider re-enter information? Trupanion’s approach joins those two questions, making the payment mechanism part of the insurance proposition.
For a pet owner, the practical comparison is equally concrete: check the hospital, obtain a quote, read the exclusions, and consider multiple-condition deductibles as well as one large claim. Trupanion’s appeal depends on those conditions fitting the household. A covered bill becomes much more useful when the money arrives in time.