Before a venture capitalist can write a founder a check, somebody has to write the venture capitalist one. Transpose Platform has made that upstream transaction a central part of its business. It invests in young companies, but also in the funds, accelerators and venture studios around them. The wager is that a useful place to meet tomorrow’s founders is beside the people helping them get started today.
That creates an unusual seat at the table. Transpose can be a startup investor in one conversation and a limited partner, or LP, in another investor’s fund in the next. Its proposition is less about a single hot sector than about where a company’s journey begins. By the time a promising startup becomes a widely circulated fundraising opportunity, the firm would like to have a relationship already.
A university memo before the buzz
The idea predates the current enthusiasm for AI. An October 2016 University of Michigan document approved a $10 million commitment to TI Platform Fund I, the earlier name found in the firm’s paper trail. Its targets included entrepreneur-led venture funds without long investment histories, along with platforms offering help in hiring, business development and product design. This was a deliberate appetite for the unfamiliar, written in the sober language of an endowment allocation.
The distinction matters. A conventional track-record screen can reward a manager for having already become established. The Michigan rationale contemplated backing teams before that evidence existed, in exchange for exposure the university’s portfolio did not already have. The hard work moves earlier: evaluating whether a manager has a credible way to attract founders and help them, before a spreadsheet of exits can settle the argument.
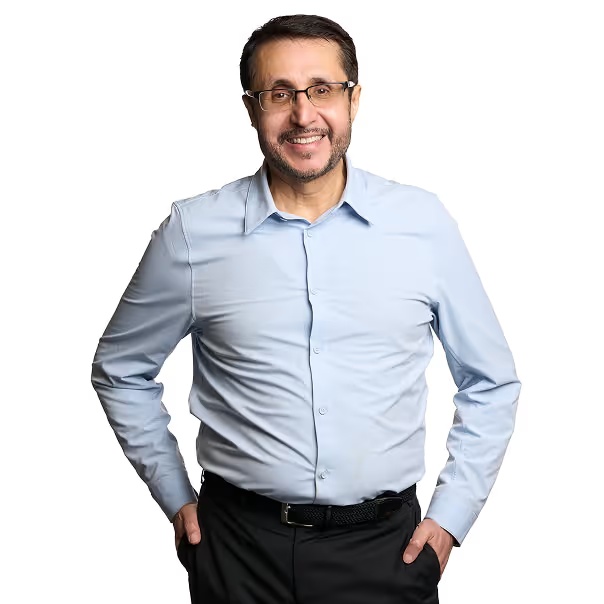
Co-founders Alex Bangash and Trang Nguyen established the business in 2015. Their backgrounds help explain the combination. Bangash worked in engineering and executive roles at companies including Bell Labs and GE before advising institutional investors. He also co-founded Trusted Insight, a network for capital allocators. His Biotech2050 interview biography reads like a bridge between the people building technology and the institutions deciding where to place long-term money.
Nguyen brought experience from the allocation side too. Her Arctic15 biography describes leading investments at Sutter Health and working on strategy and product development at Trusted Insight. It also identifies her as a co-founder of AGI House Accelerator. Those roles make the founder-and-fund combination understandable: the business asks its partners to recognize technical ambition while speaking the language of the institutions that finance it.
Two doors into the same young company
Transpose’s market has three constituencies. Founders need financing and practical help. Emerging fund managers need committed backers and introductions to more capital. Institutional investors want access to venture opportunities without building every relationship themselves. These are different jobs, with different obligations. Calling all three groups “customers” obscures who is paying, who is investing and who is receiving the money.
Relationships, not allocation percentages. A firm can invest at more than one point.
For an allocator, alternatives include committing directly to individual venture funds or hiring a specialist fund-of-funds manager. For a founder, alternatives include a seed investor, an accelerator or a studio. Transpose sits across those choices, so an organization that looks like a competitor in one transaction can become a partner in another. The overlap is the model’s defining feature, and the reason a simple league table would tell only part of its story.
Its own website emphasizes first-check relationships and help before conventional proof arrives. Garry Tan supplies the memorable shorthand: “Transpose Platform Fund is the Y Combinator for Funds.” That is a portfolio-connected endorsement, rather than an independent performance assessment. Still, it neatly captures the intended service: help a new investment organization get into business, just as an accelerator helps a startup find its feet.
Japan puts a price on the relationship
The Japan connection gives that abstract proposition a concrete buyer. In June 2024, Japan Investment Corporation announced a $30 million commitment to Transpose Platform BOV II. JIC described a vehicle investing in funds managed by Y Combinator, with a broader ambition to connect Japanese startups to global support and investors. The $30 million was an LP commitment to a fund, not a funding round for Transpose’s management company.
*With a possible two-year extension. Commitment announced June 2024.
There was a practical follow-through. On December 17, 2024, JIC, Transpose and IVS organized Tokyo Founder’s Day. About 120 people attended, and the program included Garry Tan, Bangash and Transpose partner James Tan. JIC’s subsequent presentation describes an audience of early founders, aspiring entrepreneurs, accelerators and investors. International access here meant an actual room, a program and people available to question.
The editorial lesson is straightforward: a partnership becomes easier to evaluate when it produces an activity. Introductions and advice are difficult to value in isolation. A named event with a defined audience at least makes the work visible. It does not prove that a startup will expand successfully, but it moves the relationship beyond the ceremonial exchange of logos.
Bluetooth, meet the capital table
Transpose also writes checks with much more literal destinations. In May 2023, it led Hubble Network’s $20 million Series A. Hubble wanted to connect Bluetooth devices to satellites, and said the financing would support its first satellite launches and initial pilot customers. This was a round with an identifiable technical milestone attached, not merely another promise to “scale.”
Hubble’s founders described a stubborn customer problem: existing connectivity could be geographically limited, expensive and power-hungry. A sensor is less useful if connecting it requires a large battery or infrastructure that does not exist where it operates. The investment thesis therefore involved both technology and economics. Could familiar, inexpensive devices become useful across a much larger area?
By its September 2025 Series B announcement, Hubble reported seven satellites in orbit and a $70 million round, naming Transpose among its supporters. That sequence illustrates what continued backing can look like. The round totals belong to Hubble, and the announcements do not make the entire amounts Transpose’s checks. They describe a company moving from launch financing toward a larger operating network.
A very different investment makes the portfolio’s breadth clear. In March 2025, Transpose participated in Kosli’s $10 million Series A, led by Deutsche Bank’s venture group. Kosli’s problem was software governance: banks can automate software delivery while still getting stuck collecting approvals and audit evidence manually. Its Enterprise offering pairs an evidence platform with controls-engineering services. Satellites and audit trails share little glamour; both need a specific problem worth paying to solve.
The clock is part of the cost
The firm’s March 2026 regulatory filing reports approximately $2.65 billion in assets under management. That measures the adviser’s scale, not its valuation or investment profit. Its listed clients are pooled vehicles; their number is not a headcount of underlying founders. Venture statistics become much more useful once each number has the correct noun beside it.
The same care applies to fundraising. A Form D filed in April 2025 listed a $400 million offering for Fund IV entities and zero dollars sold at that initial filing. An offering target describes an intention at a particular date. It cannot, by itself, establish a completed raise or the fund’s subsequent progress. The filing also specifies a management fee payable to the general partner or its designee, making at least one part of the business model explicit.
Time is another price. BOV II’s stated 12-year term, potentially extended by two years, gives substance to the phrase patient capital. That horizon suits a strategy whose underlying companies may still be forming. It is a poor match for someone who needs predictable near-term liquidity. Access to early companies is valuable only in conjunction with the ability to wait, absorb losses and evaluate the eventual outcome after costs.
Conviction gets its awkward chapter
The founders have discussed moments when that patience was uncomfortable. In their 2021 SALT conversation, Bangash recalled concern about three portfolio lending companies as the credit cycle changed. He said two later reached billion-dollar valuations. The companies were unnamed, and the anecdote describes his experience of changing sentiment rather than a verified loss-and-recovery ledger. It is nevertheless more revealing than an uninterrupted parade of success stories.
“We always back the underdogs.”
Alex Bangash · SALT Talks, 2021
What initially shook confidence in that account was the prospect of lending businesses being damaged by the cycle. What followed was a different market reception. The distinction matters: a financing valuation can vindicate an investor’s patience in the moment without settling the eventual investment return. Readers can borrow the habit of testing an unpopular business on its operating merits; copying someone else’s confidence is a much less reliable method.
Make the network do a job
Transpose’s public recruiting material offers a less theatrical view of the work: market research, founder outreach, investment memos, portfolio reviews and LP reporting. It describes an associate role spanning investment execution and investor communication. The implied culture is one of analytical work alongside relationship management. That is the employer’s account, but the task list is specific enough to show that networking comes with paperwork.
For a founder assessing this kind of investor, the useful question is concrete: which customer introduction, technical adviser or next financing relationship would help clear the immediate obstacle? For an emerging manager, it is how an anchor backer can support the next fund as well as the first. For an allocator, it is whether access and selection justify the structure’s costs and long holding period.
Those questions also establish the limits. A network cannot repair weak demand, and more portfolio relationships do not automatically create better returns. The approach needs founders who benefit from early help, managers who can keep earning their attention, and capital willing to remain committed. Transpose’s distinctive bet is that getting close to that process early can be a repeatable business. Its real test arrives when the introductions turn into companies, and the companies eventually turn into cash.
- Explore Transpose PlatformInvestment approach, portfolio and team.
- Transpose on LinkedIn / Transpose on X
- Watch: Alex Bangash and Trang Nguyen on SALT TalksA 2021 conversation, under the earlier TI Platform name.
- Listen: Bangash on AI, biotech and venture investing
- Watch: Transpose Ecosystem Day 2025 introduction
- Explore: Kosli Enterprise and its Series A announcement
- Upcoming: Bangash at SuperReturn Asia, September 28, 2026