Tobi Amira was eating rice when a new assignment arrived. In May 2018, during his first month at TeamApt, chief executive Tosin Eniolorunda came over with an idea for an agency-banking application. Lunch would have to accommodate a product discussion. The following day, Amira went to Sangotedo with a marketing colleague to speak to payment agents. There he encountered the kind of customer problem that rarely looks impressive in a presentation: people were checking bundles of receipts by hand.
It is a wonderfully ordinary beginning for a career that now centres on business lending. The object on the counter was small. The work behind it was considerable. Each slip represented a transaction that someone needed to understand, reconcile and trust. A product manager could admire the payment technology and still miss the person spending tomorrow morning sorting out what happened today.
Lunch, interrupted
Amira helped build the early Moniepoint product with engineers Toba Ojo and Dami Ajiboye. Prospective customers were sufficiently eager to visit the office before it was finished, waiting near the glass wall of his workspace. He remembers the pressure of their presence. Customer demand had acquired excellent visibility and rather inconvenient seating arrangements. The early application gave agents real-time transaction reports.
The episode is revealing because it leaves the users in the picture. They have things to do, money to account for and very little reason to be interested in the internal elegance of a software project. The team’s problem was to make an existing day’s work easier. A receipt can be a surprisingly demanding brief.
That is one way to read Amira’s subsequent career: as a succession of attempts to understand the activity around a payment. Who is accepting it? What do they need after it arrives? How much of the business becomes visible when the record is reliable? Those questions connect product development to operations, and eventually to the decision to lend.
A reading of the connection between Amira’s payment and lending work.
A business bank takes the stage
By November 2019, Amira was appearing publicly as TeamApt’s chief operating officer. At a business partnership session organised by Made Culture and GIZ’s Make-IT in Africa initiative, he delivered the keynote. The event brought startups and established financial businesses into the same conversation about collaboration. It was a different setting from Sangotedo, though both involved learning how one part of a commercial system could work with another.
His remit would later become more explicitly focused on credit. A 2022 conference biography described him as responsible for the product, operations, credit risk and growth of TeamApt’s lending portfolio. That is a substantial list of dependencies. A loan product has to work for the borrower, the people administering it and the institution carrying the risk. A pleasing screen is only one participant in the arrangement.
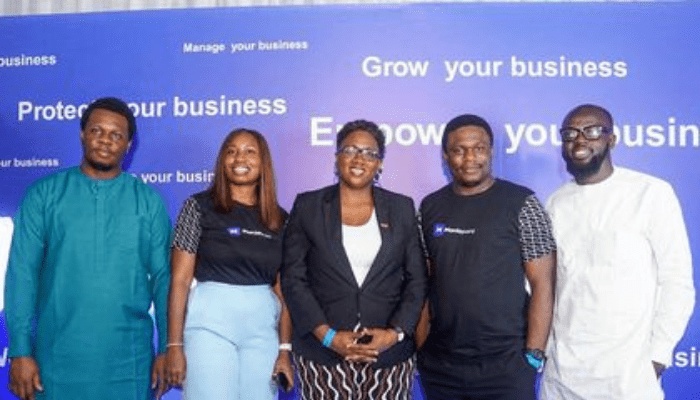
At Moniepoint’s April 2022 business-bank launch, Amira presented the scale of the payment activity the company had already handled. He reported more than a billion transactions, worth ₦23 trillion, for 162,000 small business owners since 2019. He also spoke about the operational needs the team had encountered while solving payments. The numbers described a company’s activity at that moment; the next question concerned what else its customers needed.
A business bank carries a longer obligation than a successful transaction. The merchant still has tomorrow’s stock to buy, next week’s expenses to meet and decisions to make about expansion. Payments put a financial institution close to that routine. Credit asks it to understand the routine well enough to advance money against what comes next.
The payment that seemed to disappear
A colleague’s memory offers a smaller view of Amira at work. Samuel, who later became a software engineer at Moniepoint, had been handling customer support for Monnify. A customer reported a transfer that appeared to be missing. Samuel had checked the system and the bank without resolving the puzzle. He took the problem to his line manager, Amira.
After Amira looked at it, they identified the transaction as a NEFT payment, which would reflect on the next business day. Samuel remembers the incident as a lesson in asking more questions and developing relationships with bankers who could help explain unfamiliar situations. The managerial contribution was practical: understand the process before treating the outcome as inexplicable.
That story sits neatly beside the market visit. In both cases, the interesting work begins with something that seems awkward or incomplete. A user is doing too much manual checking. A payment is behaving differently from what a support officer expects. The next step is an inquiry. There is room here for knowledge, patience and the willingness to examine a detail that somebody else has already exhausted.
It also makes the executive title easier to picture. A person can be responsible for a portfolio and still matter to a colleague through one well-timed explanation. Corporate biographies tend to prefer promotions. Teams remember the afternoon when somebody helped.
What a shop can afford to borrow
Amira’s 2023 account of Moniepoint’s credit development describes two distinct customer needs. Cash agents sometimes required additional money in their digital wallets to keep processing transactions. The overdraft product was designed around a 24-hour cycle. When the company moved toward serving businesses more directly, that design needed to change. A merchant buying stock works to a different rhythm.
Amira worked with Tosin, Chidum and other colleagues on the working-capital product, which went live in May 2023. His explanation emphasises the danger of giving a business more debt than it can manage. Transaction history helps the lender consider whether an advance makes sense and how large it should be. Product ambition has to coexist with the arithmetic of repayment.
The early overdraft addressed an agent’s short-term wallet float.
Working-capital lending launched for a broader business customer base.
Consider the difference in the underlying question. An agent may need to complete today’s transactions. A shop may want to buy goods it expects to sell over time. Both need capital, but the money enters a different sequence of events. Designing for that sequence means paying attention to what the borrower does after the application is approved.
There is a useful restraint in this part of Amira’s work. The objective includes helping a business continue trading successfully after it has received the loan. An approval is an event. Repayment is a process. A product that looks generous on the first day can prove uncomfortable over the days that follow.
Ownership, before the job description
“You more often than not have to take responsibility before it’s given to you.”
Tobi Amira, on career ownership
Amira has offered that advice in Moniepoint’s career video series. It puts emphasis on action before formal recognition. For a reader tracing his movement through product, operations and lending, the remark supplies a useful organising idea. Responsibility can expand because a problem needs someone to stay with it.
Another colleague remembers Amira introducing her to SQL while she was working as a business analyst. She describes that introduction as a turning point toward data analysis, and credits him with caring about colleagues’ growth. The scene is modest enough to be credible: a manager suggests a tool, and someone else discovers a direction worth pursuing.
His teaching has also extended beyond the company. Talstack featured him as an instructor for a course on product idea selection, covering research, competition, feasibility and prototyping. In the course introduction, he discusses an insurance company’s need to reconcile payments. The lesson returns to a familiar territory: a business process that looks straightforward until the person using it explains where it gets stuck.
In 2021, he also served on the judging panel for the Pegasus Fintech Challenge. The panel included leaders from DLM Capital, Cowrywise, Links Microfinance Bank and other organisations. These appearances place him in the exchange of ideas around Nigerian financial technology, while the colleague stories show that exchange operating on a much smaller scale.
The businesses a model has to learn to read
By July 2026, Amira was writing as Moniepoint’s Business Lead, Business Loans. His field notes argue for assessing microbusinesses through their actual trading records, with human verification alongside technological assessment. He also identifies mobile service providers without storefronts as a group requiring further work. The ambition reaches toward businesses whose activity is real but whose records do not arrive in a convenient format.
That concern gives the receipt a new significance. At the beginning of the story, it was something an agent had to reconcile. In a lending conversation, a record of trading can help make a business understandable. Its usefulness depends on the question being asked and on the care taken with the answer.
Amira’s public reflections on Moniepoint’s decade describe a consistent interest in how responsibly designed credit can help businesses recover and grow. The career has changed titles and products, but there is continuity in that attention to the customer’s next task. First, make the payment intelligible. Then ask what the business behind it might be able to do.
The glass wall, the support query and the SQL introduction belong in the same portrait. Each involves a person needing something specific. Amira’s work becomes easier to understand when those people remain visible. The receipt on the counter was never going to write a product roadmap. It did, however, provide a very good place to begin.