A payment arrives in seconds. The work that makes those seconds possible can take years. Eric Woodward has spent much of his career in that less visible interval, where banks, technology companies and customers must agree on what counts as proof. The customer sees a button. Woodward’s professional world contains the questions behind it: whose account is this, who is holding the phone, and how confidently can the system let the money move?
Today he is CEO of FinatIQ and an adviser to Baselayer, which works on business identity and fraud. Earlier, he led risk businesses at Early Warning, the company behind Zelle. That sequence gives his career an unusual shape. He has helped finance financial infrastructure, helped operate it, and then brought the experience to younger companies. The subject keeps returning, even as the name on the meeting invitation changes.
The investor crosses the table
Woodward’s route into payments ran through finance. His education paired finance and accounting at the University of Colorado with an MBA at Berkeley’s Haas School of Business. He also received his California CPA qualification. There is a pleasingly literal foundation here: before working on whether a digital identity adds up, he learned how the numbers do.
His earlier career included Donaldson, Lufkin & Jenrette and technology investment banking at Credit Suisse. At Bank of America, he became a managing director and co-founded the Strategic Investments Group. His 2019 professional biography credits that work with more than $1 billion invested in financial services companies. It also describes more than $6 billion in financings and acquisitions during his Credit Suisse work. Those are career figures, rather than a measure of his personal wealth.
One investment brought him unusually close to the machinery. He facilitated Bank of America’s initial investment in Early Warning and represented the bank on its Management Committee before becoming an employee. The move took him from evaluating an institution to helping run its businesses. An investor’s questions about a company eventually meet an operator’s questions about what it must do on Monday.
At Early Warning, his remit included identity, authentication and payments risk, alongside a decade of strategy and acquisitions work. By 2019, his team’s responsibilities covered the safety of Zelle’s payments network and established identity and authentication products. His work belonged to the part of a payment system that customers generally encounter only when it asks a question.
Represented Bank of America on the network’s Management Committee.
Led Early Warning’s risk businesses during Zelle’s development.
Listed on Baselayer’s advisory board and as FinatIQ CEO.
A phone becomes part of the evidence
In September 2017, Woodward appeared on a payments panel at the Rakuten FinTech Conference alongside Kyash founder Shinichi Takatori and Tencent’s Ling Tang. The photograph places him at the right of the stage, listening, with the other participants turned toward the discussion. The subject was the future of payments. For Woodward, part of that future was already sitting in customers’ hands.
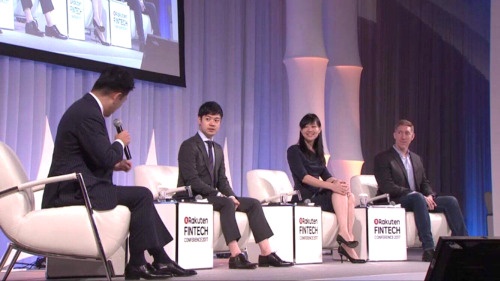
That year, he explained how a mobile device could contribute to authentication. Device information, the network operator, location, user behavior and proximity could provide layers of evidence about a transaction. A phone introduced another banking channel, but it also carried information that could help assess the person using it. He saw a security opportunity inside something often treated as an additional risk.
His point had a customer’s experience built into it. “Mobile has the potential to be the most secure channel,” he said. The useful word is potential. A device does not settle the question by itself. It offers signals that a system can combine and evaluate. Security becomes a matter of designing the relationships among those signals, rather than admiring a single impressive piece of technology.
In 2016, Early Warning announced an agreement with NuData Security to incorporate behavioral analytics and risk decisions into its authentication offering. Woodward described the combination as a way to secure faster payments while retaining a good experience. The partnership shows how that balancing act entered his operating work: combine capabilities, fit them into the network, and keep the customer’s interaction in view.
“The banking relationship starts and ends with trust.”
Eric Woodward, 2018
He returned to the subject in a 2018 essay on real-time payments. His argument favored multiple layers of authentication and a network view of fraud patterns. Shared information could reveal behavior that an individual financial institution would struggle to see alone. Faster movement of money made current information particularly valuable. There is a rather unforgiving practical demand in that argument: the risk decision has to be ready when the payment is.
A bank login, with a second life
Another part of Woodward’s work asks what an existing banking relationship might do elsewhere. Liminal identifies him as the founder of Authentify, a bank-backed identity network. Early Warning introduced the service in April 2022 with Bank of America, Capital One, Chase, PNC, Truist, U.S. Bank and Wells Fargo.
The announced experience allowed a consumer visiting a participating business to sign into an online or mobile banking environment, then share bank-trusted data with that business. Its appeal is easy to understand. A person who already has a trusted relationship with a bank might be able to use it when another service asks for proof of identity. Permission, participation and the way the information travels all matter.
The service’s April 2022 announcement, reduced to its three customer actions.
Woodward keeps returning to bank-backed identity in his public commentary. In one post, he asked what a bank should call a product built around the trust associated with account access. The question sounds like a naming exercise, yet it exposes a larger product problem. A useful institutional relationship has to become something a person can recognize and choose to use.
Advice before there was a brand
By November 2020, Woodward had retired from his Early Warning risk leadership role and joined One World Identity’s newly announced Senior Advisory Board. The group included David Birch, Jackie Shoback and Filip Verley. Its brief covered transactions, growth strategy and market intelligence. His operating experience was moving into a setting where other companies could borrow it.
Socure announced his appointment as senior adviser to CEO Johnny Ayers in May 2021. Ayers described a relationship stretching back more than eight years, with recurring conversations about digital identity. It is a useful corrective to the tidy arrival implied by an appointment announcement. The public title appeared after a much longer exchange of ideas.
Woodward’s explanation of the attraction included the ability to identify qualified customers who might otherwise be denied access to financial services. That concern gives identity work a second consequence. A decision that misses a fraudulent application can cause loss. A decision that misreads a legitimate applicant can close a door. His stated interest in financial inclusion sits inside the daily choices made by verification systems.
The next generation of relationships includes Baselayer. Woodward was named among investors in its 2024 seed round, and its FinovateSpring 2026 profile lists him as an advisory board member. Co-founder and CEO Jonathan Awad has said Woodward agreed to mentor the company before it had a brand. Awad describes turning to him on product direction and fraud strategy, particularly when the team needs to understand banks’ priorities.
That is a specific form of usefulness. Experience can help a founder anticipate the questions on the other side of the table. Woodward has sat there as a bank representative, an investor and an operator. His value to a younger business can emerge in an ordinary conversation about what a customer will need before agreeing to a new service.
The joke is in the product name
Woodward’s public voice has room for a raised eyebrow. His bank-identity naming post ends with the prospect of a cumbersome name assembled from payment speed, a bank and a login. Anyone who has watched a committee name a product can supply the accompanying sigh. He makes the joke while continuing to take the underlying idea seriously.
In a LinkedIn introduction, he also described an adjustment in how he communicated. He had enjoyed reading other people’s ideas and replying individually; he wanted to start posting more of his own thinking for payments, risk and identity professionals. The admission is modest and recognizable. Having a career’s worth of material does not automatically make someone eager to broadcast it.
His posts extend the identity question beyond banking. In a discussion of social platforms, he considered how knowing more about the party behind a message might help people interpret online content. The connection to his financial work is clear: identifying a participant changes the context in which another person decides to trust them. The applications differ, while the question travels surprisingly well.
Who gets to write the rules?
In a Fintech Takes conversation with Alex Johnson, Woodward joined a discussion about financial data networks. The subjects included who controls data, who pays for access and how shared infrastructure should be organized. Consumer control, compensation for contributors and common rules all entered the conversation. Software is only part of what a network needs to function.
His current public work includes moderating an Improve 2026 panel with Baselayer’s Jonathan Awad, U.S. Bank’s Rachel Castro and the Federal Reserve Bank of Boston’s Staci S. Shatsoff. The discussion concerned AI-related business identity risk and the speed at which banks adopt new capabilities. For someone accustomed to institutional timelines, the pressure is familiar even as the technology changes.
Woodward’s career offers a way to see the ordinary payment differently. Behind its apparent simplicity are choices about evidence, participation and responsibility. He has approached those choices through investments, operating roles, product ideas and advice to founders. The customer still wants the same small miracle: press a button, send the money, get on with the day. Making that moment dependable has given him plenty to work on.