At Chase Bank, Rose Muturi acquired a nickname that would look rather peculiar on a business card: “The Undertaker.” Her subject was the bank’s product catalogue. There were more than 130 duplicated products to streamline, and she helped turn that crowded collection into a simpler portfolio for retail customers and small businesses. In a profession fond of launching things, she had found useful work in retiring them.
The story has the appeal of a small workplace joke, but it also supplies a way into her career. A financial product can be technically impressive and still be a nuisance to understand. Another account, another application, another menu: an institution can mistake its own abundance for a customer’s convenience. Simplification requires someone to decide what deserves to survive.
Muturi now leads Moniepoint’s Kenya operations. She joined the group in June 2026, after running Branch’s Kenyan banking business. Between those appointments sit years spent in traditional banks, a credit bureau, digital lending and a mortgage lender’s digital operation. Her career repeatedly returns to the point where the institution’s internal machinery meets the person trying to use it.
Before the corner office, a telephone
Her early work included night shifts making cold calls in a business process outsourcing operation. Later came banking work involving customer documentation and analysis. These are jobs close to the practical edges of an organisation: a conversation has to happen, a record has to be usable, a process has to get through the day. They provide little room for a grand theory that cannot survive contact with a form.
Her formal education paired statistics with computer science at Jomo Kenyatta University of Agriculture and Technology. She also studied information technology at Strathmore and later completed an executive MBA at Strathmore Business School. Numbers, software and management appear here as successive tools, rather than competing identities. The work would eventually require all three.
At Standard Chartered, her roles included business analysis, planning, deposit products and priority banking relationships. Chase followed, with product development and pricing responsibilities. A career viewed only through job titles can seem to progress neatly upwards. This one also moved sideways, accumulating different ways of seeing the same customer: as a record, an account holder, a borrower and a person choosing among products.
- BankingStandard Chartered · Chase
- Credit informationTransUnion
- Digital lendingTala
- Digital bankingHF Group · Branch
- Kenya strategyMoniepoint · 2026
“Inform me” is a product brief
TransUnion changed the angle. Muturi worked on products and strategy and became acting country manager in Kenya. The credit bureau sits at a consequential junction: information held about someone helps determine what lenders will offer them. For the consumer, being assessed and understanding the assessment are two different experiences. Her work on Nipashe brought those experiences closer together.
Nipashe means “inform me” in Kiswahili. The original SMS service let consumers check their credit status, address negative listings and pursue credit. At the launch of its updated application in February 2017, Muturi said more than 60,000 consumers had already used the earlier service. Nipashe 2.0 extended the approach into an application for smart and feature phones, with a route for lenders and consumers to connect.
The name is a wonderfully economical brief. It begins with the customer’s request. Credit information is often discussed as a resource for institutions; here, the person described by the information gets a way to inspect it. That change does not guarantee a loan or a better rate. It does make the conversation less one-sided. A borrower who can see the record has something concrete to question, correct or discuss.
The phone acquired a lending desk
Tala announced Muturi as its Kenya country manager in February 2017. In her introduction, she chose “Optimistic” as the word to describe herself. She was attracted to joining the business in its pioneering Kenyan market. The company welcomed her experience and sense of humour, an agreeable combination for a job that would include both growth and the awkward questions growth brings.
By 2019, she was regional manager for East Africa. Her management routine included weekly conversations with department heads about progress and problems. She let colleagues make decisions and wanted to hear the important details. That offers a more recognisable picture of executive work than the customary photograph of someone gazing thoughtfully through glass: other people do the work, and the leader must know enough to help without becoming the queue.
The lending industry was also facing scrutiny. In 2019, she helped found the Digital Lenders Association of Kenya, bringing together firms with shared concerns about conduct and the sector’s relationship with regulators. Rapid access to a loan leaves further questions about how a lender behaves. An industry association was one way of addressing those questions collectively. Product innovation had led her into the less glamorous business of rules, representation and responsibility.
“Optimistic.”Rose Muturi, describing herself on joining Tala in 2017
A mortgage lender meets WhatsApp
Her next move was to HF Group as chief digital officer in 2019. The group’s annual report described a career spanning banking, credit scoring, pricing and technology. HF was undertaking a wider rebuilding effort under chief executive Robert Kibaara. Recruiting someone from digital lending brought a different set of habits into an institution with a long history in housing finance.
She oversaw HF Whizz, the digital banking platform. Her own account of that period includes a digital home ownership savings plan, a product that connects the small repeated act of saving with the much larger ambition of buying a home. It is an instructive pairing. A phone can shorten a transaction; the thing someone hopes to achieve with that transaction may still take years.
Another project involved WhatsApp. HFC wanted to communicate with younger customers and micro-entrepreneurs through a familiar channel and help them use a broader range of services. Working with Infobip, it adopted the WhatsApp Business Platform. Muturi described the resulting change in customer interactions and the customer journey. The significance lies in the modesty of the starting point: find where the conversation already happens, then make the bank easier to reach there.
The puzzle piece that was a licence
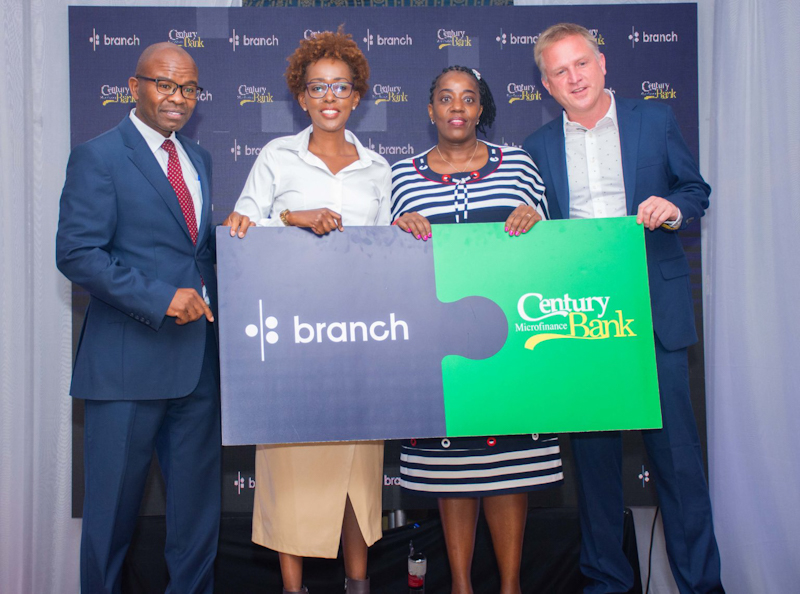
In March 2022, a photograph captured Muturi with Century Microfinance Bank’s chairman Peterson Mwangi, its chief executive Florence Muchiri and Branch co-founder Matt Flannery. They held large interlocking pieces carrying the two companies’ names. Acquisition ceremonies rarely trouble the history of visual metaphor, but this one made the underlying transaction unusually easy to read.
Branch had acquired an 84.89 percent stake in Century. The acquisition gave the digital lender a route into deposit-taking banking and a broader set of services. Muturi was its East Africa managing director. She described the opportunity to move beyond lending and offer more products to existing Kenyan customers. The Central Bank of Kenya’s subsequent directory listed her as chief executive of Branch Microfinance Bank.
The business question had expanded. A lender meets someone when they need money; a banking relationship can include keeping money and moving it as well. Branch’s later messaging placed saving, investing, borrowing and transacting together. That sequence matters to the story because the phone stayed familiar while the institution behind it changed. A new capability required the banking structure to support it, as well as an interface that customers could understand.
The ask, and the people doing the work
Muturi grew up in Ayany, in Kibera, among a mix of communities and languages. A school visit by Kenya Airways captain Koki Mutungi once made flying seem the obvious future. She eventually took a different route. The anecdote is a reminder of how concrete an ambition can become when someone who already does the job walks into the room.
Her own approach to opportunity is to ask. In a later conversation about rejection, she said, “I don’t have a hard time handling rejection.” It is a useful temperament for a career that has involved changing industries and learning unfamiliar commercial skills. A refusal can be an event to work through. It need not become a verdict that governs the next application.
She has also spoken about wanting influence beyond East Africa and about enjoying the process of making products with customer feedback. Her work has drawn recognition, including Business Daily’s Top 40 Under 40 women in 2015 and recognition as a fintech finalist in the 2024 Angaza Awards. Those honours identify moments of visibility. The steadier thread is the work itself: what a team builds, what a customer can use, and what needs another attempt.
Kenya, again - with a different brief
Moniepoint confirmed her appointment as Kenya CEO in July 2026. The company made a precise distinction: she would lead the group’s strategic direction in the country, while Sumac Microfinance Bank remained a separate entity with its own leadership. Moniepoint had acquired Sumac earlier that year. Her new position therefore belongs in a story about building the group’s Kenyan operation, rather than treating every acquired business as the same management job.
The appointment brings together experience that is often described in separate professional vocabularies. Banking contributes the discipline of operating an institution. Credit scoring brings attention to the information behind decisions. Product work asks how the service will function for someone using it. Digital lending supplies experience of building in a market where customers, competitors and regulators can all change the conversation quickly.
Her path makes those connections visible without requiring a tidy destiny. The child who wanted to fly, the night-shift caller, the bank product manager and the digital banking executive were doing different work. The later roles gave her reasons to reuse what the earlier ones had taught her. At Moniepoint, the next products and decisions will provide the evidence of what that combination can do.
There is still something pleasing about “The Undertaker.” It gives the career a human scale. Amid the large language of financial technology, someone had to look at a cluttered shelf and decide which products to remove. Banking becomes easier through such decisions, one at a time. Rose Muturi’s story leaves room for the quiet achievement of making a complicated institution a little easier for another person to use.
Continue the conversation
- Moniepoint ↗
- Rose Muturi on LinkedIn ↗
- Twitter profile linked by Tala in 2017 ↗
- Tala’s introduction ↗
- Nipashe’s 2017 update ↗
- The Fuzu conversation ↗
- Her conversation with Ali Hussein Kassim ↗
- Video conversation and listening links ↗
- The Moniepoint appointment ↗
- The Branch acquisition ↗
- HF Whizz and WhatsApp ↗
- A personal interview ↗