A paycheck can arrive like clockwork while a credit application goes nowhere. That is the contradiction Tilt wants to turn into a business: someone can earn money, pay the bills, and still look unpromising to a lender reading a thin or bruised credit file. The bank account contains a running account of that effort. Tilt wants it admitted into evidence.
The San Francisco company, known as Empower Finance until August 2025, offers cash advances, a revolving credit line, and unsecured credit cards. Its intended customer needs usable money and a chance to establish a better borrowing record. The proposition is practical, almost stubbornly so: judge people partly by what their finances are doing now.
There is an equally practical way to read the pitch. Tilt advertises cash advances of up to $500, but reports an average first-time offer of $98 in the second quarter of 2026. The maximum is the ceiling; the average gets closer to the first encounter. For a household short on gas or groceries, those are very different numbers. Tilt publishes both.
01The car loan that would not budge
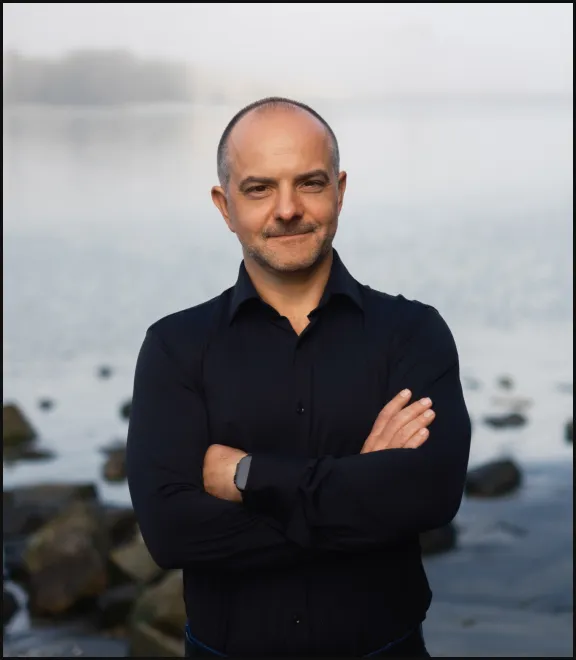
Warren Hogarth had met that contradiction personally. An Australian immigrant to the United States, he paid bills from savings and income, then discovered that getting a loan for a car was another matter. In a 2024 Banking Transformed interview, he recalled being turned down despite doing what he considered financially sensible. Avoiding borrowing had left him without the history a lender wanted.
Hogarth went on to spend about eight years at Sequoia Capital before co-founding Empower with technologist Justin Ammerlaan in 2016. The early product helped people organize their financial lives. By its 2020 funding announcement, the menu included budgeting, spending analysis, bill negotiation, deposit products, and human coaching alongside AI. It was an ambitious answer to the familiar problem of knowing what to do with money.
The emphasis shifted in 2019 toward a more immediate need: obtaining it. Contemporaneous reporting on the company’s later financing traced that change to customers needing food and fuel before financial planning. In September 2022, Empower raised $150 million in combined equity and debt, with Blisce leading and Community Investment Management supplying debt financing.
That sequence offers a useful lesson for anyone building a consumer product. A detailed map of someone’s spending can be helpful. It does not fill a petrol tank. Tilt’s evolution suggests the urgent job can be smaller, less glamorous, and much more valuable than the comprehensive service a founder first imagined.
02A bank statement gets a second job
Tilt says its underwriting uses more than 250 nontraditional indicators of financial health. Income, spending, and savings patterns help it decide what someone may be able to repay. Its description of the approach emphasizes current financial readiness and the possibility of larger offers as a customer establishes consistent payments.
The expertise is in credit decisions, with the app providing the front door. Bank linking gives those decisions more information; Tilt identifies Plaid as a partner. For a customer, the exchange is straightforward: provide access to financial activity so the company can make a more informed offer. A person without useful account data, or without enough capacity to repay, may still be turned down.
Cash-flow underwriting is also a bet with a delay built in. Hogarth explained in the podcast that a lender can send money today and wait months to learn how much comes back. More information is valuable only if it helps predict outcomes. Fast approval is visible immediately; sound underwriting takes longer to demonstrate.
Tilt sits among cash-access apps such as Dave, Brigit, and MoneyLion, while also competing with credit-building and card products. Its distinctive proposition is the combination of several kinds of cash and credit access with the same emphasis on financial activity. That creates room to serve different needs, provided customers understand which agreement they are entering.
“many people are good for it”Warren Hogarth, announcing the Tilt rebrand, August 2025
03Three doors. Different bills.
Cash Advance is the short bridge. Eligible customers receive offers from $10 to $500 without a credit check, interest, or late fees. Repayment follows the expected paycheck. Tilt says an unpaid advance is not sent to collections or reported on a credit file, although another advance is unavailable until the previous one is repaid. That distinction matters when borrowing products share a screen.
The subscription introduces a separate cost. Tilt’s published fee schedule charges most subscribers $8 a month after a 14-day first-time trial. Standard delivery is free and usually takes one business day. Instant delivery costs extra: a $100 advance carries a $5 delivery fee under the listed schedule. Deleting the app does not cancel the subscription.
Consider a simple illustration: one $100 advance during a paid subscription month, delivered instantly. The listed subscription and delivery charges total $13, in addition to repaying the $100. Choosing standard delivery removes the $5 delivery charge. This is a dollar-cost example, not an APR calculation, and the subscription also covers other tools. Still, “no interest” leaves some arithmetic to do.
Example: one $100 instant advance during a paid month. The $100 principal is repaid separately. Standard delivery would remove the $5 fee.
The FinWise Bank-issued credit line has different mechanics. Starting limits are $200-$400, with potential growth to $1,000. Customers draw money into a bank account and choose a repayment plan. Selecting automatic repayment in full on the next payday brings 0% APR; other schedules generally carry 35.99% APR, subject to state requirements. Late payments can bring fees and negative credit reporting.
That product can create reported payment history, but it also introduces the obligations of a credit account. A larger limit is conditional, not an automatic graduation prize. The useful comparison is the actual offer, due dates, and total cost of the selected plan. Someone who needs several pay cycles to repay is considering a different proposition from someone bridging a few days.
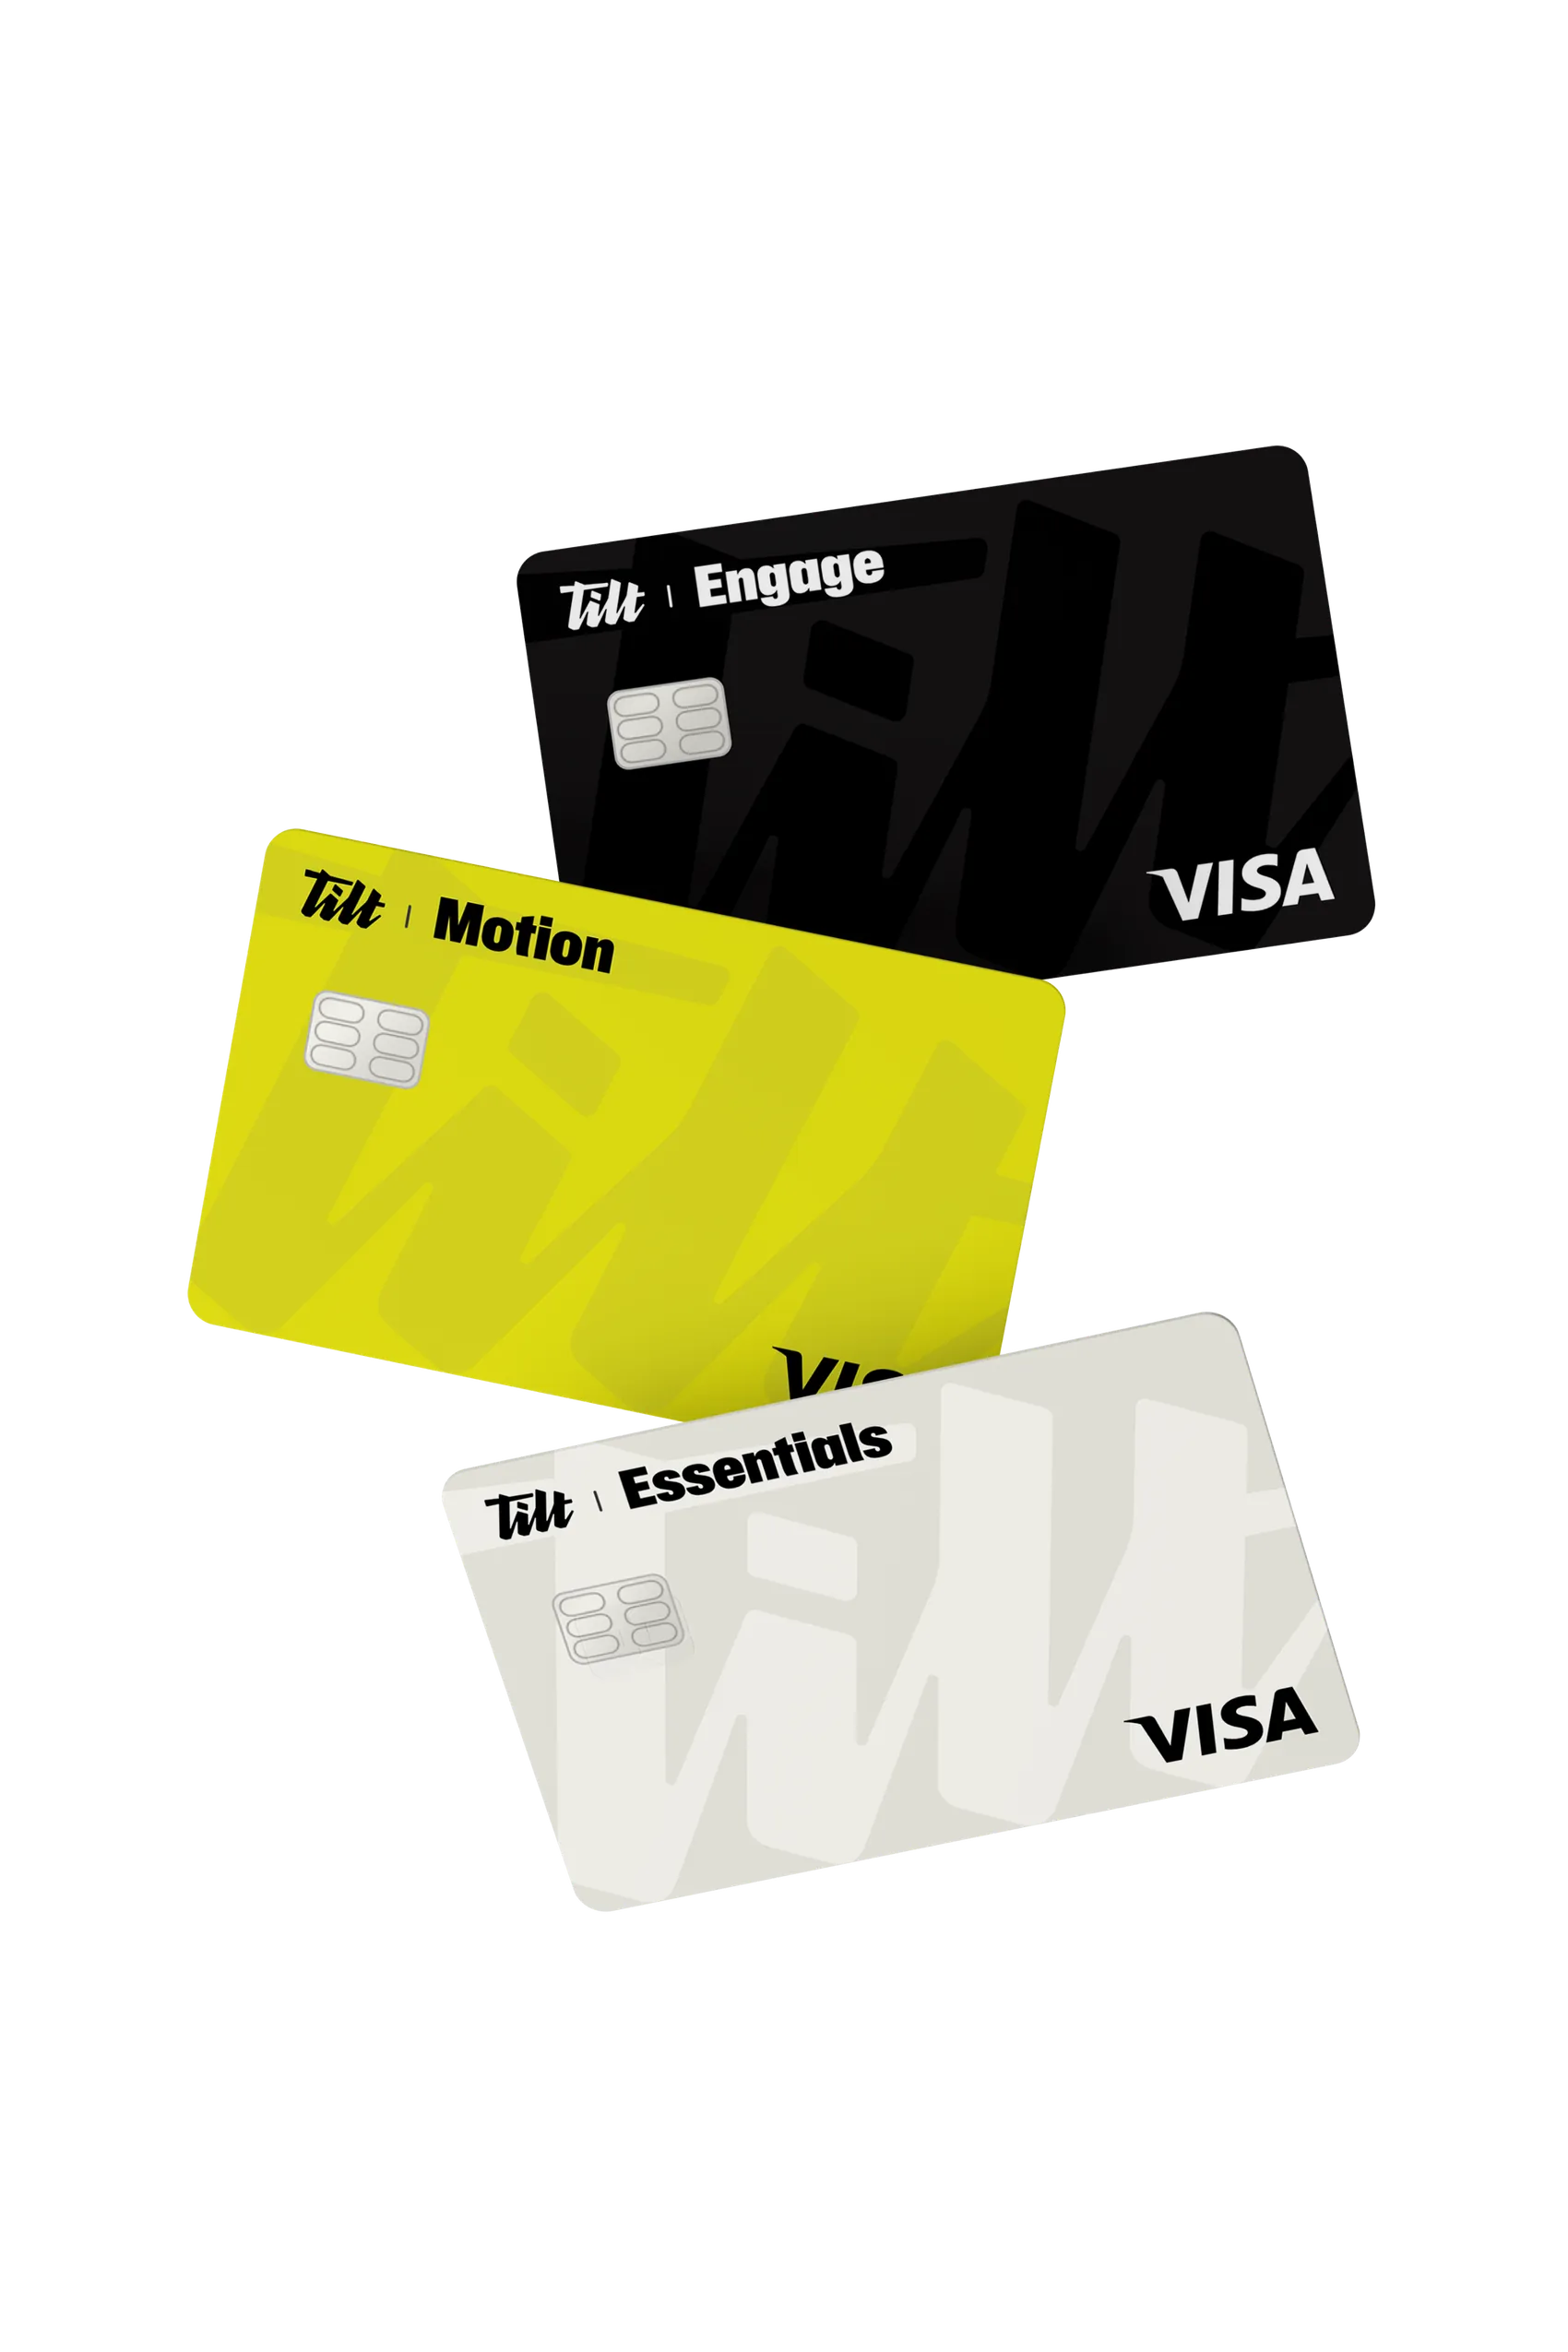
The three WebBank-issued cards require no security deposit and carry no Tilt subscription charge. Prequalification does not affect the credit score; a full application involves a hard credit inquiry. This is where Tilt competes for a longer relationship: everyday purchases, rewards, reported payments, and opportunities for increased spending capacity.
Essentials has no annual fee and lists a 29.99% variable purchase APR. Its rewards structure offers 3% cash back on gas and groceries with AutoPay enabled, plus 1% elsewhere. Motion also has no annual fee; Engage charges $59 annually. Both list variable purchase APRs of 29.24%-34.24%. Merchant-specific rewards come with their own terms. At these rates, carrying a balance deserves more attention than the color of the card.
04Buying a way into the wallet
The card expansion has a corporate backstory. In April 2024, Empower announced an agreement to acquire Petal and completed its purchase of Philippine digital credit company Cashalo. Petal brought an established card business built around a similar idea: bank-account information could help qualify people with limited credit histories. Nearly 400,000 consumers had been approved for Petal cards since 2018, according to the announcement.
By the August 2025 rebrand, Tilt also identified Indian personal-loan provider NIRA as a recent acquisition. It had established a Mexican credit business in 2022. The company said it served more than three million active US subscribers and had been profitable since 2022. Those are company-reported measures, but they describe a business with operations beyond a freshly painted app.
The commercial logic is an inference from that sequence: acquire local expertise and products where they already exist, then expand the range of needs the group can address. Subscriptions and delivery charges support the core cash offering; credit products add interest, applicable fees, and card-payment economics. The tension is familiar in consumer finance: a more useful relationship can also become a more expensive one.
05Fewer meetings, more money questions
Tilt’s careers page describes a virtual-first team across 14 countries and 12 time zones. It favors recommendations on Slack over meetings and slide decks, and brings employees together twice a year. Its stated values put weight on ownership and outcomes. These are specific working choices, rather than proof that every employee experiences the same culture.
For consumers, the smaller supporting tools remain relevant. Tilt’s product range includes budgeting and automatic savings, with banking services supplied by nbkc bank. The original financial-organization idea has survived alongside credit. A cash buffer and clearer spending information can complement access to borrowed money; repeatedly moving the same shortage forward is a harder problem.
That is the condition attached to Tilt’s larger ambition. The offer must fit what a customer can repay, the data must reflect that customer’s life, and the benefit must justify the charges. A short gap between income and bills is one use case. Expenses that keep exceeding income are another. An app cannot make those two situations equivalent.
What readers can copy is the sequence: identify the immediate obstacle, examine current evidence, and give progress a measurable next step. What borrowers can use is more concrete: compare the actual offer, check the payment date, and distinguish an advance from a credit account. Tilt wants to change the story a lender sees. The customer still has to live with the next chapter.
Keep following the money
Explore Tilt · The Tilt blog · LinkedIn · X · Instagram · Facebook
Watch: Garry Tan talks credit access with Empower (2022)
Tilt on YouTube · Listen: Hogarth on alternative-data lending