There is a revealing verb on Pale Blue Capital’s website: triage. Hospitals use it when several things need attention and somebody must decide what comes first. Investment firms more often talk about growth. This one also talks about repairing impaired investments and relationships that have soured. For the business formerly called Tecton Capital Partners, the interesting customer may arrive carrying a portfolio assembled by somebody else.
- Tecton Capital Partners now operates as Pale Blue Capital.
- The offering spans portfolios, alternatives, financial transitions and family offices.
- Its distinctive pitch: start with the investor’s needs, including the awkward ones.
The business of the second opinion
The firm says it often begins working with people after an earlier investment relationship has deteriorated. That is a specific point of entry. A prospective client already has assets, an experience of advice, and reasons to question both. The first task becomes diagnosis: understand what the investments are doing and whether they still serve the owner.
On its special-situations menu, Pale Blue lists concentrated stock holdings, business sales, generational wealth transfers, and scattered or opaque investments. These problems have something in common. A balance sheet can look substantial while its owner struggles to answer practical questions about access, exposure or control. Wealth can make the paperwork considerably more interesting.
A scientist, a banker, a family
Founder Denver Dale’s background supplies an unusual route into this work. He earned a doctorate in biomedical sciences at Oxford, following studies in medical and marine biology at the University of Queensland. FINRA records place him at Goldman Sachs from August 1992 to August 2000. The scientist became an investment professional.
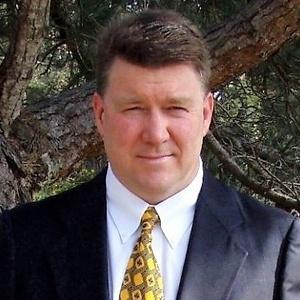
His interests also reached the commercial side of science. At SynBioBeta London in 2014, where he appeared as On-Point Capital’s founder, he urged entrepreneurs to think carefully about who would want their products and when. He described the investor’s supporting role with an image refreshingly distant from the usual financial vocabulary.
“Venture capitalists are the roadies, not the rockstars.”Denver Dale · SynBioBeta London, 2014
Tecton’s own company profile dates its founding to 2015 and now directs visitors to Pale Blue Capital. Dale’s FINRA employment history places the Pale Blue chapter from August 2021. The successor says it originally served his family’s investment needs before opening to outside clients. Its advertised audience includes individuals, trusts, foundations, corporations and institutional investors.
Start with the deadline
Pale Blue describes an approach that begins with objectives and timelines, then works backward to investment strategies. The order matters. The desired outcome becomes the starting specification. Selection, structure, management and time have to fit around it. The firm presents itself as an independent registered investment adviser offering customized work across traditional investments and alternative assets.
Its services divide into four areas. Investment Services covers liquid portfolios. Alternative Investments addresses assets including venture capital, private equity, hedged funds, structured securities and real assets. Special Situations handles major financial changes. Family Office Services coordinates a family’s wider affairs. The common thread is the effort to make several financial decisions work together.
That makes the company broader than its venture-capital associations suggest. Someone looking for a startup cheque would be asking a different question from a family seeking coordinated investment management. The public service menu speaks mainly to the owner of capital: how to arrange it, evaluate opportunities, and prepare for changes in the owner’s circumstances.
The investment that outlived its job
The alternatives offering includes reviewing and repurposing legacy investments. That small detail deserves attention. An asset can have made sense when purchased and become awkward later. The owner’s circumstances may change while the investment carries on with its original timetable. Reviewing an existing commitment can be as consequential as selecting a new one.
The firm’s public descriptions connect that review to consolidation, liquidity and reporting. Its family office service adds privacy, security and alignment among relatives. A family can own assets together without agreeing about their purpose. Bringing those expectations into the conversation is part of the service Pale Blue offers, alongside managing the investments themselves.
Its independence pitch rests on freedom from the pressure to sell proprietary products or satisfy public shareholders’ quarterly demands. That explains its market positioning against private-bank teams and other wealth advisers. It is a statement about incentives and flexibility; readers should assess the actual portfolio decisions and contract terms on their own merits.
The difference is easier to see in the questions a client brings. Which holdings can fund the next obligation? Which require patience? Who receives the reports, and who makes the decisions? Those are editorial examples of the coordination problem implied by the offering, rather than accounts of particular Pale Blue clients.
The price of attention
The public adviser directory Warmer lists annual asset-based rates of 1% through $5 million, 0.9% from $5,000,001 through $20 million, and 0.8% above that. It also describes a separate arrangement for qualified clients: 2% of assets plus 20% of capital appreciation. These are directory-listed terms; the applicable schedule needs confirmation with the firm.
For a simple illustration, a flat 1% annual charge on an unchanged $1 million balance equals $10,000. That arithmetic describes the advisory charge alone. It does not establish a particular client’s bill. A performance-linked arrangement introduces another calculation, so comparing proposals requires attention to the agreement as well as the percentage printed beside it.
Write the job description for the money
The useful lesson here is an editorial one: give each investment a job and a deadline. Ask what it is supposed to support, when access matters, and what has changed since it was bought. Those questions can clarify a conversation with any adviser. They also expose where an attractive asset might fit poorly.
Customized coordination has limits. A straightforward investing need may require much less machinery than a family office, while a long-term private investment may resist a near-term spending plan. Pale Blue’s proposition is most intelligible where financial decisions overlap: the stock position, the sale, the family, the next chapter. The work begins by figuring out which complication needs attention first.