The sign in the window was advertising a building. Someone at TabaPay noticed it, and the conversation eventually reached a more interesting question: was the bank for sale, too? It was. That is how chief executive Rodney Robinson described the discovery of Denver’s Transact Bank to Banking Dive. For a company selling the machinery of instant payments, a bank is quite an addition to the shopping basket.
- TabaPay connects businesses to card and bank payment networks through one API.
- Its specialty is money with a deadline: wages, loan proceeds, repayments and account funding.
- A $155 million financing accompanies a proposed bank acquisition, still awaiting approval.
On September 2, 2026, TabaPay announced that financing, led by FTV Capital, and its intention to acquire Transact. The proposed TabaBank would sit alongside the payments business. The ambition is easy to grasp: bring more of the journey under one roof. Understanding why that matters requires looking behind a button most of us barely notice.
TabaPay’s reported scale. The transactions belong to its clients; the infrastructure sits underneath.
The card in your pocket has a second job
We know what happens when a debit card buys lunch. Money leaves. TabaPay also uses card networks to send money in the other direction. A lender can disburse a loan to an eligible card. A workforce platform can pay someone after a shift. A digital banking app can let customers move money into an account from an outside debit card.
These are different transactions with different rules. Account Funding Transactions bring money into an account; Original Credit Transactions support sending it out to a card. TabaPay puts those flows, along with bank-payment options, behind a unified application programming interface. Developers build the connection; payments teams work through the permissions, funding and operational details.
appTabaPay
APICards
or banks
One integration. Different routes. Eligibility still applies.
Branch makes the purpose concrete. It began with shift scheduling, then confronted an awkward gap: helping someone earn more did not make payday arrive sooner. Its bank introduced it to TabaPay. Push-to-card payments helped Branch deliver earned wages, and the relationship expanded as Branch developed its wallet and broader workforce payments offering.
The customer buying TabaPay is the platform, lender or financial institution. The person waiting for the money may never hear its name. A worker sees Branch’s interface. TabaPay handles the underlying card transaction.
A name is a payment control
Speed creates its own problem. A payment that moves quickly leaves less time to stop a mistake. Current, another customer, needed to admit legitimate cardholders without making its funding process an open door. It already used identity checks and address verification. With TabaPay, it added Visa Account Name Inquiry, which compares the customer’s name with the card issuer’s records.
Visa’s April-June 2025 pilot supplies the revealing detail. Cards with a full name match had a 57% lower chargeback rate than cards with no match. Their card attachment success rate was 76%, versus 30% for no-match cards. Those are comparisons between groups, rather than a claim that every Current payment became 57% safer overnight.
with a full name match
with no name match
Current + Visa ANI pilot · April-June 2025 · Group comparison
The lesson for a product team is practical: inspect the point where a good customer gets rejected. Better information at that point can improve acceptance while helping identify risk. Adding another screen for everyone is only one possible response.
The cents add up
TabaPay sells transaction processing. Its card pricing uses Interchange++: underlying interchange and network charges, plus its processing fee. The fee depends on the program and volume. Direct network connections and routing options give the company ways to work on cost beyond simply discounting its own margin.
Its published account-funding example estimates $0.91 against $2.43 for other payment service providers on a $200 transaction. That comparison assumes a particular mix of networks and regulated and unregulated debit cards. Treat it as a worked example. A buyer should bring an actual transaction mix to the pricing discussion.
Usio’s experience adds another dimension. The payments platform needed more debit routes, stronger fraud visibility and smoother onboarding. TabaPay helped it add network choices and migrate to a different sponsor bank. The bottleneck was partly institutional. A neat API alone would not have solved it.
Its bank relationships span the United States and Canada, with cross-border card payouts also available. That is TabaPay’s position in a crowded market. Stripe Connect covers platform payments and payouts; Dwolla concentrates on bank payments. TabaPay emphasizes regulated money movement, card funding, disbursement and repayment, with network and bank expertise attached.
Follow the payment all the way home
The operational work continues after authorization. TabaPay’s July 2026 Portal update brought deeper transaction history, an Insights Hub for approval and decline patterns, and a Report Builder. A team can follow a transaction through settlement and chargebacks instead of assembling the answer from separate reports.

There are boundaries to the promise. Receiving institutions and recipient eligibility affect availability. ACH and instant card payouts are different products. The dedicated rails page still labels FedNow “coming soon.” A team choosing infrastructure should confirm the route it can use today, the funding required and what happens when a transaction fails.
The API grows a bank
TabaPay’s founders bring long payments experience: Robinson leads the company, Manoj Verma runs revenue, and Marvin Mah leads technology. Their next challenge includes owning more responsibility. In 2024, TabaPay abandoned a proposed Synapse asset purchase after closing conditions were not met. The acquisition did not close.
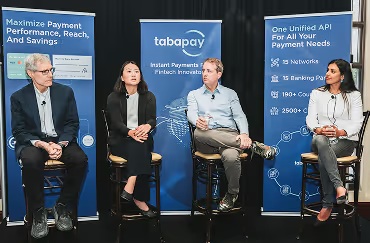
Robinson later connected that experience to the decision to pursue a bank.
“So we learned to go full measure and get a bank.”
Speaking to Banking Dive, October 2026
Yet the planned purchase does not mean dispensing with partners: Pathward extended its TabaPay relationship into 2031.
Regulatory approval remains a condition; TabaPay expects bank operations in 2027. For readers building financial products, the useful idea is already available. Draw the entire payment journey, including the banks and exceptions. Then decide which parts deserve closer control. For TabaPay, that map eventually led to a bank with a building for sale.