A bank founder can spend twenty-two years building an institution and still face an awkward final assignment: handing somebody else the keys. W. Swope Montgomery Jr. reached that moment on June 11, 2013, his sixty-fifth birthday. He stepped down as BNC Bancorp’s president and chief executive and as chief executive of Bank of North Carolina. His successor, Rick Callicutt, had been there from the beginning. The birthday came with a change of title, rather than a clean escape from the banking business.
Montgomery stayed on as vice chairman and a consultant. By then, the enterprise he had helped launch in Thomasville, North Carolina, in 1991 had become a bank with more than $3 billion in assets. That is a considerable distance to travel from a small founding group. But the more revealing part of his departure was the arrangement for what came next: the bank wanted his relationships and experience to remain within reach.
There is something pleasantly practical about this version of a founder’s farewell. The speeches could end. The customers would still have questions. Somewhere between those two facts sat Montgomery’s next job.
Before he put his own bank on the map
Montgomery was an Asheville native and a 1970 graduate of the University of North Carolina at Chapel Hill. His early adult years included service in the US Army Reserves, where he was a staff sergeant, from 1970 to 1977. Banking began alongside that service. At Trust Company of Georgia, from 1971 to 1980, he worked in retail and corporate banking.
Those are two useful ends of the same profession. Retail banking encounters the individual account; corporate banking encounters the company behind the payroll. Montgomery’s subsequent move to Wachovia took him into national accounts, working in Winston-Salem and Atlanta between 1980 and 1988. He then led a commercial banking team for First Union in Greenville, South Carolina, from 1988 to 1990.
The geography matters. His working life already stretched across the Southeast before Bank of North Carolina began. So did the range of institutions on his résumé. By the time he helped establish a bank, he had worked with household customers, companies and national accounts. The founder arrived with an apprenticeship extending across roughly two decades, rather than a sudden enthusiasm for putting his name on an office door.
Fourteen people, then room to grow
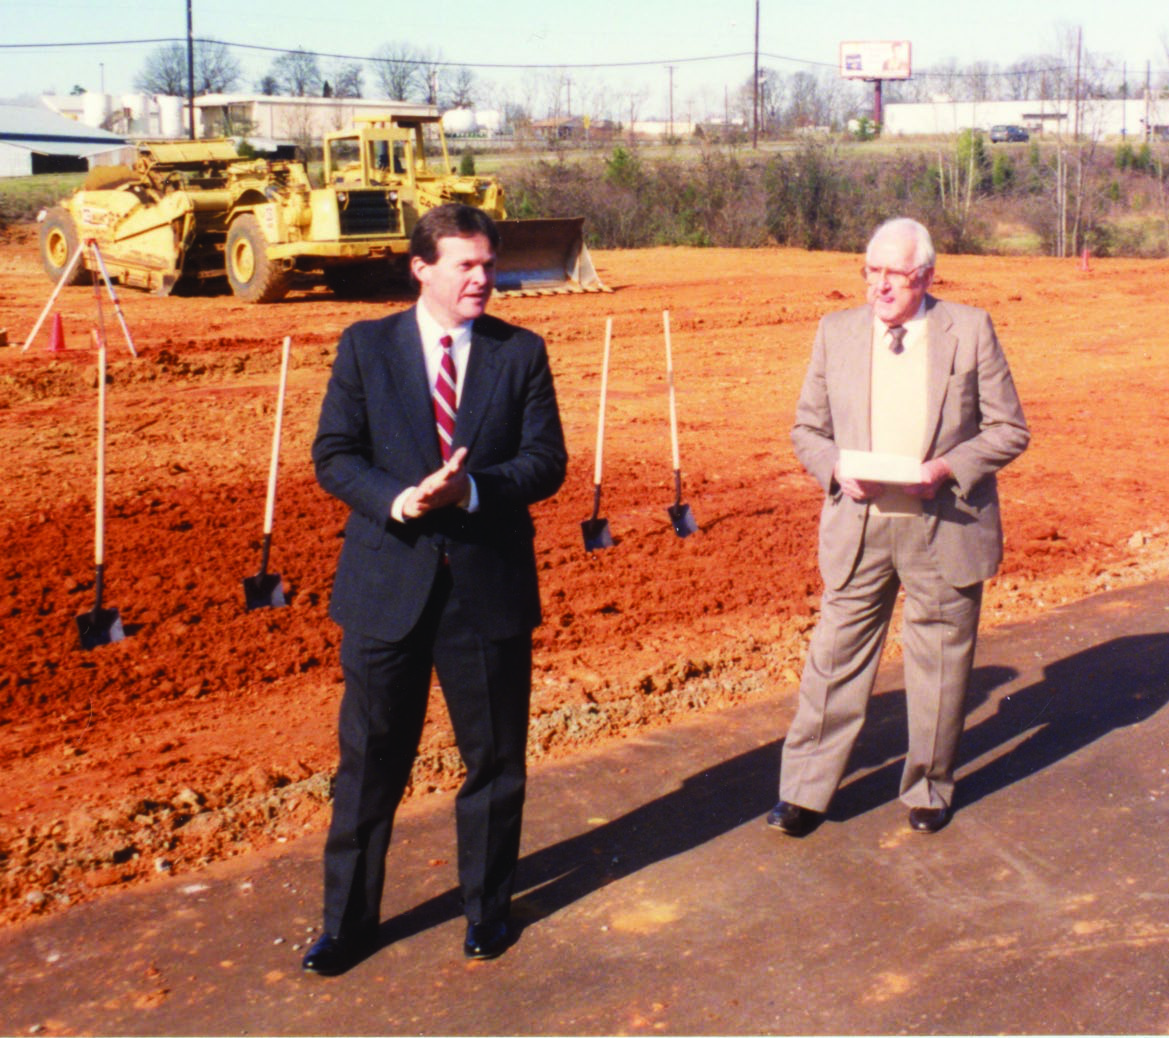
Montgomery and Callicutt helped start Bank of North Carolina in Thomasville in 1991 with fourteen employees. Local investors supplied the initial capital. Later accounts put that founding investment at about $4 million. It is a useful number, provided it is kept in its proper column: founding capital is the owners’ investment, while a bank’s assets describe a different and much larger part of its business.
The institution’s early expansion was measured in years. Its first bank purchase came nine years after the start: a Kernersville bank with $50 million in assets. Subsequent acquisitions extended its presence into places including Asheville, Charlotte, Durham, Greensboro and Greenville, South Carolina. A bank that had begun with a North Carolina place-name was developing a regional reach.
The dates resist the temptation to turn the story into one uninterrupted acquisition spree. First came the work of establishing the bank. Then came the first purchase. Only later did dealmaking accelerate. Montgomery’s career has a long middle, which is where most of the work in a banking business tends to reside.
There is also a distinction between the bank and the holding company. Bank of North Carolina opened in 1991; BNC Bancorp came later, in 2002. Montgomery served both. Keeping those names and dates straight helps explain why his retirement announcement listed more than one position. He was president and chief executive of the parent company, and chief executive of the bank itself. A single career had accumulated a small collection of corporate titles, each attached to a different legal responsibility.
The price of an opportunity
The financial crisis changed the circumstances in which BNC could expand. In April 2010, the bank acquired failed Beach First National Bank in Myrtle Beach, South Carolina, through an FDIC-assisted transaction. That purchase opened a new chapter in its growth. It also belonged to a particular moment: banks with the capacity to act could acquire businesses that others could no longer keep going.
By June 2012, Montgomery had overseen seven acquisitions in two years. BNC was using several sources of capital, including investment from Aquiline Capital Partners and money from the federal Troubled Asset Relief Program. Keeping government capital while raising private money might have appeared an odd combination. Montgomery’s explanation was decidedly a banker’s explanation: he was interested in its cost and its usefulness.
“We consider it fairly inexpensive capital that still counts as Tier 1.”
W. Swope Montgomery Jr., June 2012
That short sentence has little ceremonial polish, which is part of its charm. Tier 1 capital is a core measure of a bank’s financial strength. Montgomery was explaining why BNC retained a particular source of funding while pursuing acquisitions. Opportunity still had to be financed. Even ambition, in a bank, has to find the correct place on a balance sheet.
Growth also carried complications. Acquired offices, customers and loan books had to become part of an operating institution. The transaction announcement was merely the public punctuation. The long sentence that followed belonged to the employees who had to make the enlarged bank function.
The compliment that counted people
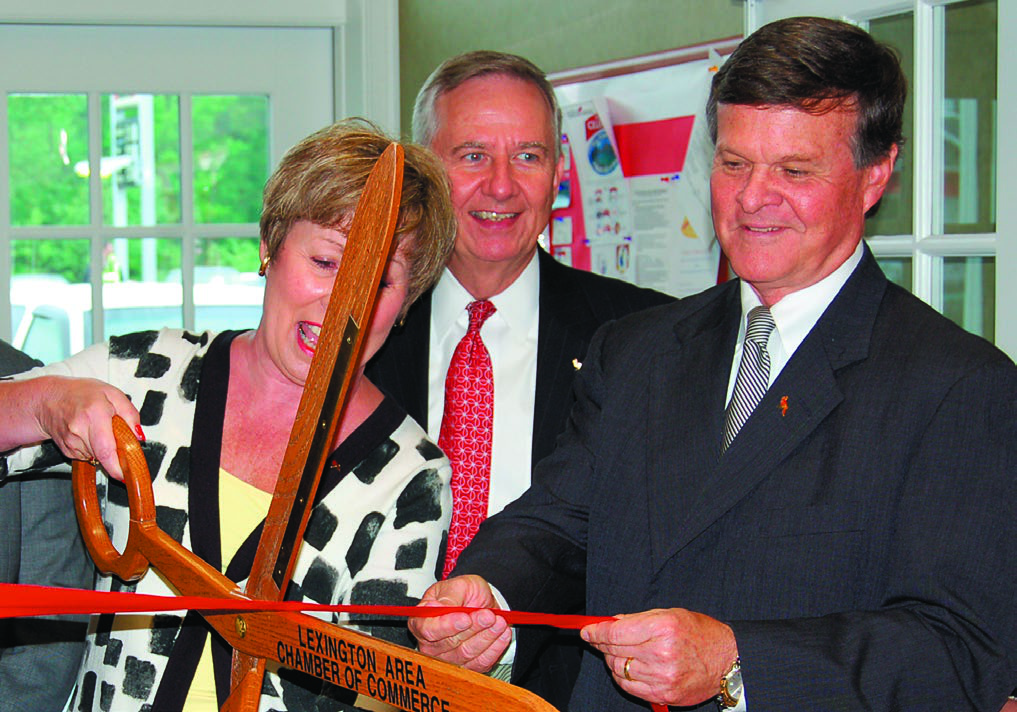
When BNC marked Montgomery’s approaching retirement, one colleague singled out his ability to assemble the management team. Another described him with three compact words: dependable, dedicated and fair. These were assessments by people who had worked alongside him, and their emphasis is telling. They drew attention to the person selecting colleagues and representing the company.
In his own farewell to shareholders, Montgomery stressed integrity and humility. The language could have drifted into the usual corporate wallpaper. Beside the colleagues’ descriptions, however, it points to a consistent concern: the people who would carry the institution after its founding chief executive stepped aside. The balance sheet was visible. The appointments that helped produce it were less conspicuous.
Callicutt’s presence gave that concern a practical answer. He had worked at the bank since its inception and had already served as its president. David Spencer, the chief financial officer, was another central figure in the leadership group. Montgomery’s departure would change the senior executive title without requiring the business to introduce itself to an entirely unfamiliar team.
A birthday with contractual obligations
The transition had a precise date. On April 12, 2013, BNC announced that Callicutt would succeed Montgomery on June 11. Montgomery’s employment agreement provided for retirement at sixty-five. The board arranged for him to continue as vice chairman and retained him under a two-year consulting agreement running to June 11, 2015.
His consulting duties were unusually good at explaining what the company valued. He could be asked to meet customers when his personal knowledge and participation would help, and to represent the bank at industry events. The arrangement allowed for up to ten business days a month. Relationships, which rarely appear as a neat line in an earnings table, had acquired a schedule.
There were boundaries, too. Unless the chief executive specifically requested it, Montgomery was not to initiate transaction discussions with other financial institutions. A founder could remain useful without leaving the new chief executive wondering who was negotiating the next deal. Few retirement sentiments are quite as concrete as a clause establishing who gets to telephone another bank.
“I am comforted knowing we have a proven, results-oriented leader as my successor.”
Montgomery on Rick Callicutt, April 2013
That reassurance made sense because the successor was already part of the story. The handover asked Callicutt to continue an enterprise he had helped build. Montgomery’s continuing board presence offered continuity, while the executive appointment placed responsibility with somebody else. For a bank built over twenty-two years, the distinction mattered.
The board’s decision also preserved access to a particular kind of memory: the founder’s knowledge of customers and the institution’s earlier choices. His consulting assignment made that knowledge available by request. It was a workable way of keeping experience in the room while making space for a new person to take the decisions.
The name changed. The career continued in advice.
BNC kept expanding after Montgomery left the chief executive’s office. By June 2016, it had $5.7 billion in assets and sixty-two branches across the Carolinas and Virginia. Those later figures belong to Callicutt’s period as chief executive. They also show what became of the institution Montgomery had helped establish and then entrusted to his successor.
In January 2017, Pinnacle Financial Partners announced an all-stock acquisition valued at approximately $1.9 billion. The merger closed on June 16, 2017. Bank of North Carolina merged into Pinnacle Bank, and Callicutt became Pinnacle’s chairman for the Carolinas and Virginia. The legal combination was followed that September by the public change of signs and identity.
There is a small irony in a founder’s achievement eventually becoming difficult to spot from the road. The familiar bank name disappeared from the branches. Its business continued inside another institution, with High Point serving as an area headquarters. A sign can be replaced in an afternoon; a regional banking operation takes rather longer to assemble.
Montgomery’s later public biography places him on Pintail Equity’s advisory board. It is an apt continuation for someone whose retirement agreement had already recognized the value of advice and connections. His career moved from learning established banks, to helping create one, to remaining available after he had passed on executive responsibility. The final change of title was smaller than the history behind it.