A customer opens a wallet bearing a retailer’s name. The colors are familiar. So is the logo. Behind that reassuring screen, however, somebody has to verify an identity, maintain a balance, connect a card and move the money. That somebody might be Sipay. The Turkish company’s most revealing product is a way for another business to look a little more like a financial institution without assembling the entire operation itself.
- Merchants buy payment acceptance. Brands can buy the infrastructure for their own wallets.
- Sipay announced $93 million across two funding rounds in 2024 and 2025.
- The attraction is fewer systems to manage. The tradeoff is dependence on one provider.
The wallet with someone else’s name
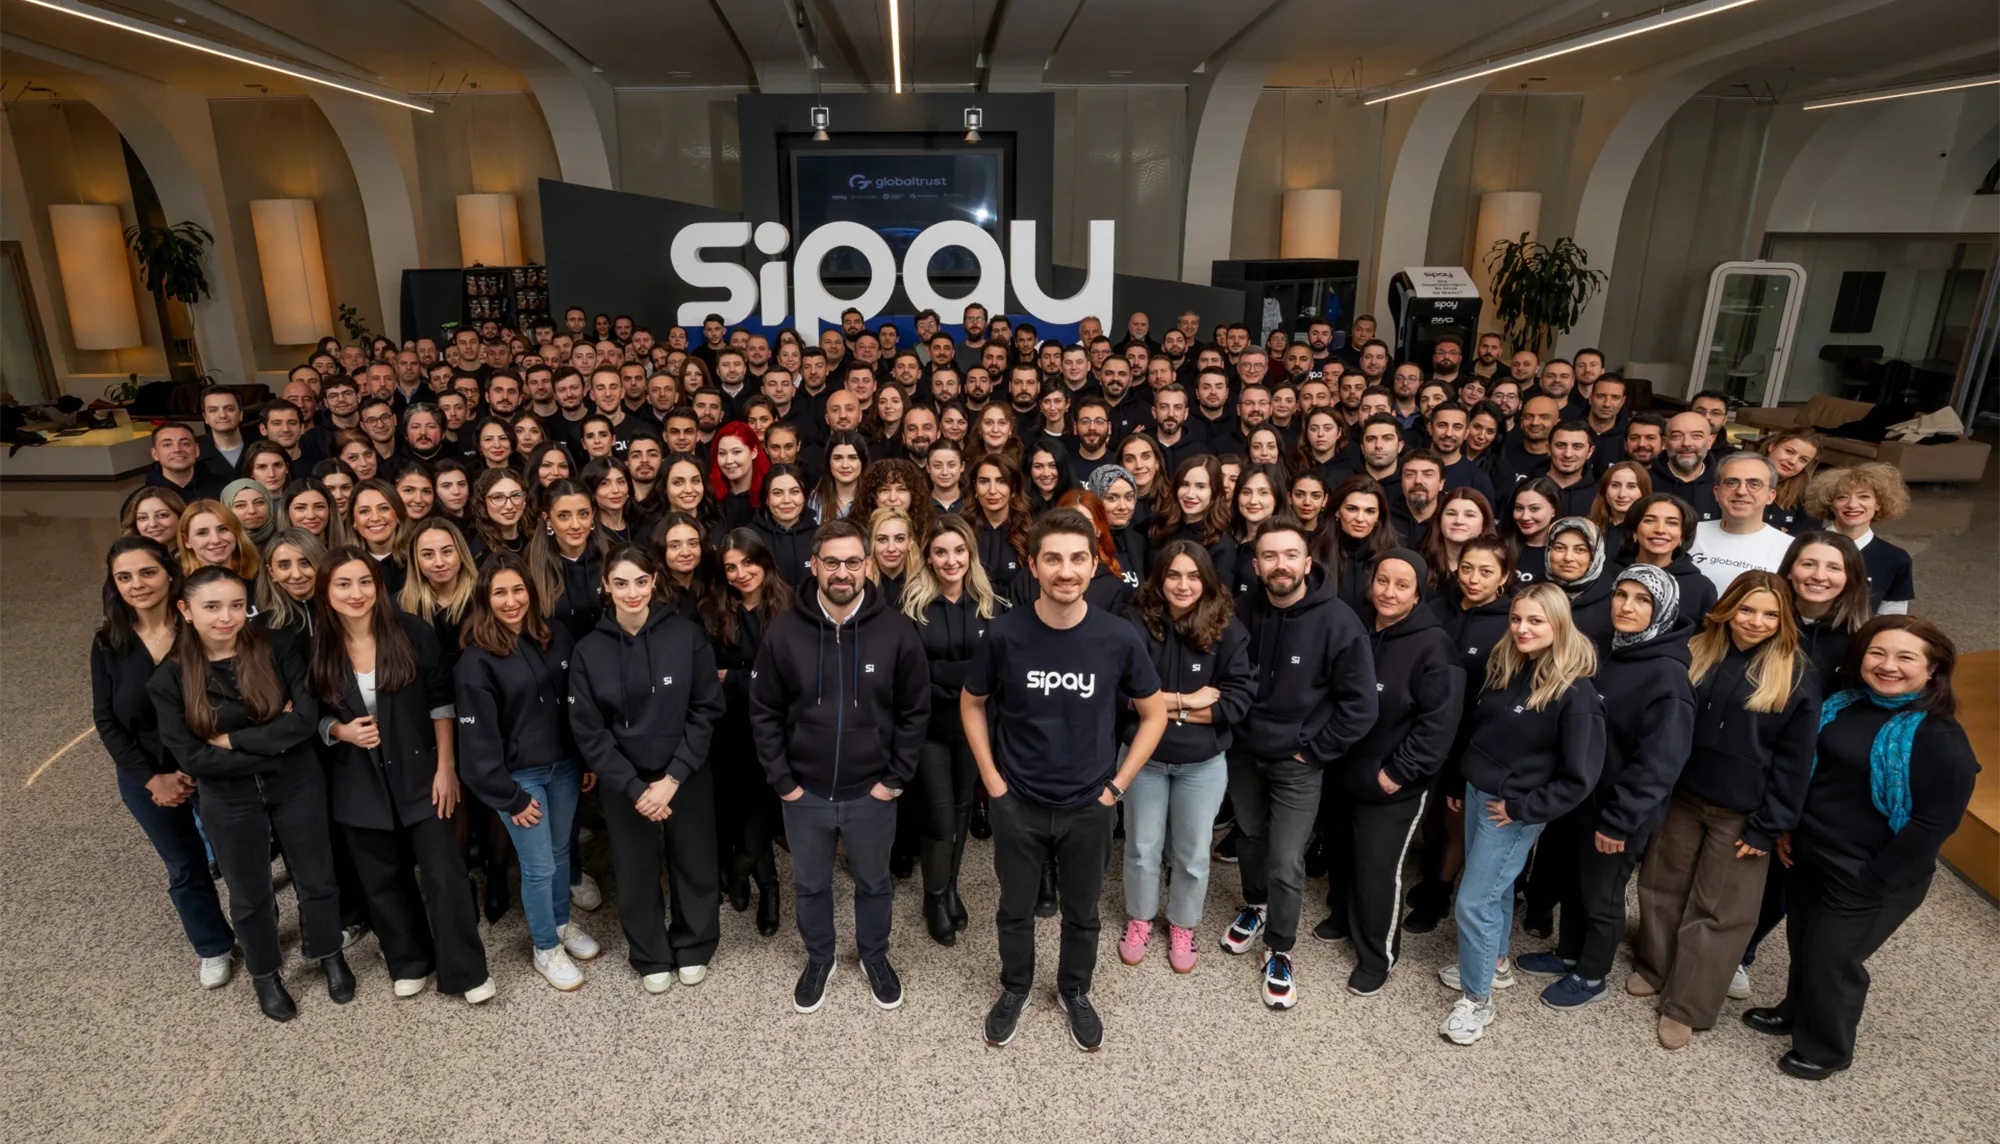
Nezih Sipahioğlu founded Sipay in 2019 after working in consultancy helping Turkish entrepreneurs establish businesses overseas. Its product range now stretches from online checkout to physical payment terminals, consumer wallets and prepaid cards. But Walletgate, its service for branded wallets, offers the clearest explanation of the company’s ambition. A business can keep its identity at the front while Sipay supplies much of the financial apparatus behind it.
Walletgate bundles card issuance, transfers, loyalty programs, fraud tools and a back-office interface. Its API documentation describes individual and business accounts, wallets in Turkish lira, dollars and euros, top-ups, withdrawals and identity checks. These are the little verbs that make a wallet useful. Each looks simple on a phone. Together, they form a substantial operational commitment.
One detail makes the proposition wonderfully concrete: a business can upload a single file to arrange as many as 10,000 payouts to wallets or bank accounts. Imagine the payroll-like burden of paying a network of partners individually. The value here is easy to picture. Fewer repetitive steps leave more time for the business that generated the payments.
The checkout is the front door
For an online merchant, the immediate problem is narrower: get paid. Sipay’s Virtual POS connects card acceptance through one integration, supports installment payments and offers modules for familiar e-commerce systems. Payment links and recurring payments extend the options. The Business Panel gives merchants a place to follow transactions and reports rather than treating every sale as another administrative loose end.
That puts Sipay alongside Turkish payment providers such as iyzico and PayTR for merchant acceptance. Consumer wallets bring a different set of alternatives, including Papara and banking apps. Walletgate adds another dimension to the comparison: whether a company wants a payment provider or the infrastructure to offer financial products itself. A single competitor name cannot capture all three purchasing decisions.
The merchant economics are recognizable. Sipay advertises commissions on Virtual POS transactions, with no setup fee or monthly or annual membership charge. A merchant still needs a quote for the applicable rate. For branded wallets, Sipay describes a software-as-a-service offering. The business case is to compare that contract with the engineering, operations and support a company would otherwise have to organize.
Individuals encounter the same platform differently. Sipay Wallet offers transfers and payments, while physical and virtual prepaid cards give the balance somewhere to go. Open banking brings bank accounts into the experience. Hesap, announced in April 2025, extends the idea into comparing loans, credit cards and deposits. Its launch promised personalized advice using AI as a later addition, rather than an established result.
These products serve different buyers, but they share a practical aim: reduce the number of separate financial systems a customer has to visit. Whether that convenience pays for itself depends on the work it replaces.
$93 million, then a harder number
In June 2024, Sipay announced a $15 million Series A led by Anfa. Ten months later came a $78 million Series B led by Elephant, with QuantumLight participating. The stated purpose was expansion into emerging markets. Public accounts put the valuation around $875 million to $877 million. That narrow discrepancy deserves an approximate number, not an argument over the last digit.
“Nezih and team have achieved a lot with a little.”Idris Sami, partner at Anfa · June 2024
The scale figures explain investor interest. At the April 2025 announcement, Sipay reported 6.3 million wallet users, 25,000 registered merchants and 100 million cumulative transactions. These are historical company figures; registered merchants and wallet users should not be mistaken for people transacting every month. They show distribution, while leaving the intensity of that distribution a separate question.
There is also a useful distinction between a revenue run rate and annual accounts. Sipay publicized a $600 million run rate in 2025. Its Turkish operating company’s published financial tables offer a different, more grounded lens: 2025 revenue of about TRY 20.89 billion and net profit of TRY 342.9 million. The comparison column shows about TRY 16.33 billion in revenue and TRY 851.9 million in net profit for 2024.
Bars are scaled within each pair. Revenue and profit use different scales.
Revenue rose. Net profit fell. Those facts can coexist. They make a more useful starting point for judging the company than assuming that fundraising, payment volume and profit all move together. They also put the operating costs of a broad financial platform back into the picture.
The permission behind the promise
Regulatory permission is part of the product. In November 2025, Turkish technology publication Swipeline reported a renewed temporary suspension of specified Sipay payment and electronic-money permissions, while other permissions continued. The current central-bank register, checked in October 2026, lists Sipay among active electronic-money institutions with those authorizations marked. The historical interruption matters even though it should not be described as ongoing.
This is the dependency hidden inside the promise of convenience. A brand outsourcing its wallet still needs to understand verification, contractual responsibilities and continuity. The interface can carry its own colors; the ability to operate depends on the provider underneath.
Borrow the machinery. Keep the relationship.
The transferable lesson is a product decision: find the work customers need done but do not want to build a department around. Package that work so they can retain the relationship they care about. Sipay’s approach fits businesses with enough payment complexity to justify shared infrastructure. A simple shop may need only checkout. A company requiring unusual controls may need more customization. The sensible question is which responsibilities the package actually removes.