Before Sieva Kozinsky was buying companies, he was carrying too many books. A student at the University of California, Santa Barbara, he lived off campus and biked to class with textbooks, notebooks and a bulky laptop. Going home between lectures was inconvenient. Bringing his entire academic life along was inconvenient in a more literal way. He began wondering why the materials could not all live on the computer.
That question led to an early software business called Studiously. He recruited a friend who could build the product and offered to handle selling it to professors and universities. The division of labor sounded sensible. The sales pitch was harder. University purchasing departments had little reason to trust two students with their course materials. An idea that looked obvious from a bicycle seat looked rather different from behind an institutional desk.
The professor in the Hawaiian shirt
Kozinsky grew up in the San Francisco Bay Area after his family emigrated from the former Soviet Union. Entrepreneurship was not an obvious family script. A conventional profession and a good education offered a more familiar route. Living near technology companies did not automatically make starting one feel like a possible occupation.
At UCSB, an entrepreneurship class changed the picture. John Greathouse, who had built and sold businesses, taught it. Kozinsky remembers the Hawaiian shirts, the relaxed manner and the freedom to swear in class. Here was a professor whose authority seemed to come from having tried things. A Hawaiian shirt is a modest garment to carry the weight of a career change, but this one evidently did.
Kozinsky found himself sitting at the front, taking notes and enjoying the work. He began experimenting with businesses of his own. His account gives the turning point an appealingly ordinary setting: a recommended elective, a teacher he liked, a subject that made him pay attention. The founder story begins with curiosity becoming a practical activity. Someone had shown him that a person could make a company, and he wanted to try.
The notes become the business
StudySoup emerged from the difficulty of finding useful academic help. Kozinsky knew the problem as a student: incomplete notes, guides that did not meet his needs, and tutoring that could stretch a student budget. Together with Jeff Silverman, he developed a marketplace through which students could share and sell learning materials, including course notes and study guides.
The arrangement gave capable note takers an audience and a way to earn money. Other students could find help tied to the classes they were actually taking. The person who had understood Tuesday’s lecture could become useful to the person who had not. StudySoup made that exchange easier to organize across a campus.
The founders moved from selling course software to institutions toward serving students directly. That was a significant change in who needed to say yes. It also kept the company close to a problem they understood. By 2017, Kozinsky was included in Forbes’ 30 Under 30 education list as StudySoup’s cofounder. His early achievement was a working marketplace built around an everyday frustration.
An investor returns to campus
After several years with StudySoup, Kozinsky went to Wharton. He had already made angel investments and enjoyed discussing business ideas with friends. Graduate school placed him among people starting companies while navigating the same uncertainty he remembered from his undergraduate years.
He helped establish The MBA Fund, connecting founders from Wharton, Harvard and Stanford with capital and a support network. The premise was practical: investors wanted to see promising young companies, alumni could help finance them, and founders needed guidance as well as checks. Campus relationships could connect the three.
Kozinsky’s own experience supplied the reason for the mentoring component. He remembered questions and challenges that would have been easier with knowledgeable people nearby. Building a company had taught him the cost of finding every answer alone. The fund made those lessons available to the next group of students.
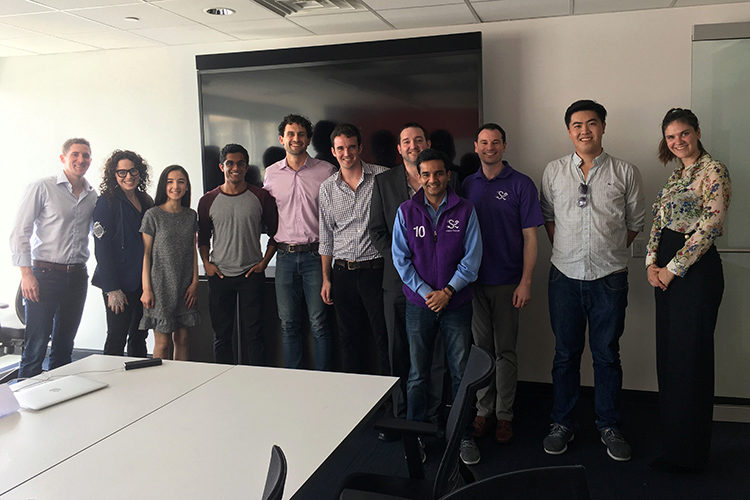
A photograph from Wharton places him among classmates and pitch finalists at 2401 Walnut. It is a useful pause in the story: a founder back in a classroom environment, now helping other people make their first attempts. The notes had changed subjects. The interest in learning from peers had survived.
A partner, a portfolio, a longer calendar
In 2019, Kozinsky and Xavier Helgesen founded Enduring Ventures. Helgesen brought his own company-building experience, including cofounding Better World Books. Together they shaped a holding company inspired by Berkshire Hathaway and by their experience sitting on the seller’s side of transactions.
Their stated ambition was to create the buyer they would have wanted for their own businesses. Enduring would take control, operate companies and give them time to grow at an appropriate pace. It could also accept a business staying the right size. That last possibility is unusually revealing. Size is useful; the obligation to get larger can become expensive.
Enduring’s current biography says it owns more than 25 businesses across fields including software, home services and hospitality, employing hundreds of people around the world. The spread reflects a willingness to consider different kinds of companies rather than confine the portfolio to one fashionable sector.
The company typically seeks control stakes of 51 to 100 percent. An acquisition therefore brings responsibility for what happens afterward. The holding company is meant to provide an enduring home for businesses, with operators doing the daily work. Its name places a fairly demanding instruction on the front door.
Businesses owned by Enduring Ventures, according to its current company biography.
What should the next dollar do?
Kozinsky’s explanation of Enduring begins with cash-flowing businesses bought at reasonable prices, paired with capable operators and held for the long term. Buying is the beginning of the arrangement. The owner must then decide how to use what the companies earn.
This is where his role broadens. A single company may have more cash than it can use productively within its own operations. A holding company can consider opportunities elsewhere in the portfolio, or buy another business. The useful question becomes where an additional dollar has the best chance of doing worthwhile work.
He traces the model to Buffett’s early approach at Berkshire. The attraction is the ability to direct capital among businesses over time. It requires judgment about price, operations and people, then a willingness to wait. Waiting is easier to admire in a biography than to practice with money and employees involved.
Kozinsky’s stated plan is to keep the portfolio rather than organize each purchase around a scheduled sale. “That’s our plan,” he says. The short qualification matters. An intention to hold forever still leaves tomorrow’s decisions to be made.
businesses
to allocate
or acquire another
The notebook that admits mistakes
Kozinsky keeps a running document of beliefs and another of lessons learned at Enduring. In a conversation about his working habits, he described the latter as 15 pages and growing. It includes mistakes as well as things the team got right. He revisits the documents, adds ideas and changes earlier views.
This is a pleasantly unceremonious picture of an investor: occasionally forgetting the document for months, then returning to edit his own convictions. A belief has to remain useful to keep its place. The method gives experience somewhere to accumulate besides memory.
He also describes himself as better suited to buying businesses than building each one from scratch. That is a meaningful adjustment for someone whose early identity came from founding companies. It makes room for other operators’ strengths. Choosing the right work for himself becomes part of choosing the right people for the portfolio.
“I’m a huge biography nerd.”Sieva Kozinsky
When a book business needed an owner
Scribe Media gave the holding company’s philosophy a demanding assignment. In 2023, the publishing services business was in financial trouble. Eric Jorgenson, who had published with Scribe, heard the reports and started calling. He knew Kozinsky and Helgesen through Twitter and had met them at Berkshire and Capital Camp.
Jorgenson brought them the possibility of buying the business. They moved into the work of assessing it, including traveling to Austin. Enduring helped fund salaries and expenses while the team continued supporting authors. Jorgenson later became CEO. His account makes the relationship behind the transaction visible: an author wanted a publisher to survive and knew people prepared to examine the problem.
The legal and financial repair was more complicated than the word “revival” suggests. The old company entered bankruptcy. A new entity hired much of the remaining team and purchased certain assets. Kozinsky served as interim operating CEO during the crisis.
Keeping the business going did not undo every loss. Authors faced difficult news about work they had already paid for. The episode puts weight behind the language of long ownership: somebody must handle the uncomfortable conversations before the future can become an attractive proposition. Here, the calendar began with urgent obligations.
A bargain store in an investor’s reading pile
Kozinsky’s public writing ranges beyond the companies he owns. In January 2025, he wrote about 99 Cents Only Stores, beginning with his mother-in-law’s ability to tell him which locations were worth visiting. It is a small domestic detail that makes an investment history feel less remote. Retail analysis can start with someone who knows whether the shop is any good.
He followed the chain’s founding and eventual collapse, asking whether its demise was inevitable. For a writer interested in businesses that last, a vanished retailer offers useful friction. A company can serve customers for years and still fail. Longevity deserves examination rather than a congratulatory label.
In July 2026, he returned to the dangers of expansion, comparing Litton Industries and Level 3 through periods of technological optimism and diversification. The topic suits an owner of varied businesses: there is a difference between finding another useful investment and allowing enthusiasm to outrun the economics.
The Business Buying Academy turns these investigations into a public practice. Its website advertises weekly insights for more than 70,000 subscribers. Kozinsky also shares material on X and YouTube. The audience extends the classroom, but the subject remains specific: how businesses work, how they are bought, and why apparently sensible decisions sometimes unravel.
Forever still has a Monday morning
Enduring’s current acquisition criteria make room for companies in difficult situations, including former venture-backed startups and business units their parent companies want to sell. The firm looks at revenue from $20 million to $750 million and EBITDA ranging from negative territory to $10 million. Those figures describe its published search criteria, rather than the size or performance of every business it owns.
His story has moved from a student’s bag to a portfolio, with a classroom, an investment fund and a publishing rescue along the way. The appealing thread is his willingness to revise the assignment. Build software. Help students. Connect founders. Buy businesses. Decide where the next dollar should go.
The word “forever” gives Enduring its horizon. The work inside that horizon is ordinary and recurring: understand the company, choose people carefully, pay attention to cash, correct mistakes. Somewhere in that routine sits Kozinsky’s larger aspiration. He wants businesses worth keeping, and an ownership structure capable of keeping them. Then Monday arrives, and the proposition needs to work again.