The bank with a single branch has a problem. Its customers carry the same phones, shop at the same websites and expect the same quick payments as customers of a national giant. They may love knowing their banker. They still expect their debit card to work. Somewhere behind that familiar counter, somebody has to buy the machinery.
SHAZAM Network exists in that gap. It supplies the payment connections, processing and banking software that let local institutions offer services their customers take for granted. But its most revealing feature sits outside the product catalogue: the institutions it serves can become its owners. A small member gets one vote. A larger member gets one vote, too.
- Shared payments infrastructure for community banks and credit unions.
- Members elect the board and have equal voting rights.
- Services span debit processing, banking software and security.
- Earnings go back into the business.
Small banks needed a way in
In 1976, the Iowa Bankers Association brought community banks together to establish Iowa Transfer System, the organization that became SHAZAM. Electronic funds transfer was opening new possibilities. Larger banks had the resources to move first. Cooperation gave smaller institutions a way to participate while keeping local control.
The company’s history traces the experiment through an integrated point-of-sale pilot in 1981, pay-at-the-pump technology in 1986 and the Privileged Status surcharge-free ATM program in 1997. Those milestones describe a practical ambition: make a local bank useful wherever its customers happen to be.
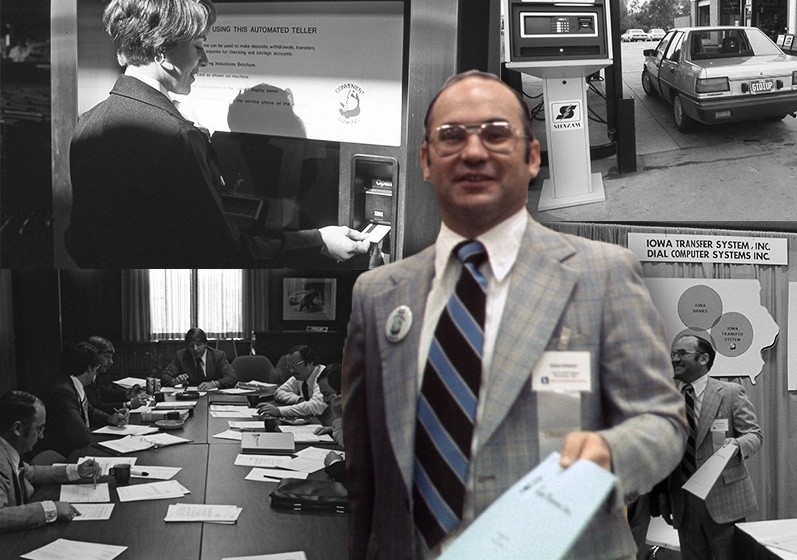
The arrangement also faced a price test. SHAZAM says rising national card-association participation fees in the late 1990s prompted it to form ITS Bank and become a principal member. Its history credits that response with saving participants millions annually. The company was changing its position in the supply chain to address an expense its participants faced. That episode gives the ownership argument a concrete economic purpose.
One vote changes the conversation
An ordinary supplier asks customers what they want. SHAZAM gives eligible institutions a route to formal governance. Members elect a board drawn from member institutions. Committees and an advisory council bring customer experience into planning. CEO Paul Waltz, himself a former bank executive and SHAZAM board chair, describes members as the people who direct the organization.
Its nonprofit, member-owned model reinvests earnings into products and services. The useful inference is about incentives: the people paying for the infrastructure can influence where it goes next. That gives a bank another way to address a familiar procurement frustration - being dependent on a supplier whose priorities it cannot influence.
another ballot.
Members → elected board → investment in services
The machinery behind the card
The name can hide several businesses. The SHAZAM payments network provides debit routing. Peregrine handles processing: authorization, settlement, fraud monitoring, reporting and disputes, alongside ATM and acquiring services. A bank choosing a network and a bank choosing a processor are making related decisions about different parts of a payment.
Then comes the software around the account. KinetiCore provides core banking, with APIs for connecting other systems. DigiHive supplies online and mobile banking. DocuCommand organizes documents, permissions and retention. SHAZAMSecure adds audits, cybersecurity assessments and testing. The customer buys access to operating capabilities, along with the expertise to keep them running.
- 01The purchaseA card starts a payment request.
- 02The connectionProcessing and network routing move the request.
- 03The decisionAuthorization and fraud checks help determine approval.
- 04The accountingClearing, settlement and reporting follow.
The alternatives depend on the job. Fiserv’s STAR and FIS’s NYCE compete in debit networking; Jack Henry sells core and digital banking technology. SHAZAM’s distinctive argument combines its product range with customer ownership. For a prospective buyer, that makes governance another item to compare alongside functionality, integration and price.
There is a human operating layer, too. SHAZAM’s careers page reports average employee tenure of 8.3 years and 90% retention. These employer-reported figures do not prove service quality, but they describe the continuity the company wants to sell alongside its technology. Its stated values include dependability, fairness and transparency.
A savings estimate, with a catch
What does the arrangement cost? An institution needs a proposal that reflects its particular services and requirements. One published result offers a useful starting point. In a SHAZAM-hosted testimonial, Toledo Metro Federal Credit Union CEO Dan Zimolzak estimates monthly savings of $6,000 to $8,000 after conversion, describing the annual benefit from its debit program alone.
“What excites me most about our partnership with SHAZAM is the cost savings.”Dan Zimolzak / Toledo Metro Federal Credit Union
Annual debit-program savings reported by Toledo Metro Federal Credit Union after conversion.
Published testimonial. Individual result; savings will vary.That figure belongs to one credit union. Another institution’s outcome will depend on its existing contract, transaction mix, conversion requirements and service choices. The lesson for a buyer is to ask for the full calculation: processing expenses, network economics, implementation work and the cost of operating the result. A shared ownership structure cannot substitute for that arithmetic.
The network keeps getting new jobs
First Bank in Clewiston, Florida, supplies a concrete example of access. In September 2023, it announced FedNow receive capabilities through SHAZAM, with First National Bankers Bank supporting settlement. Customers could receive payments from other FedNow participants around the clock. First Bank said it had already offered instant payments through The Clearing House’s RTP system and SHAZAM since early 2021.
By January 2026, SHAZAM was emphasizing product decoupling and DigiHive connections to third-party cores. That matters to institutions that want a new digital experience while retaining other systems. In June, it announced debit card bill pay through Peregrine for collections such as insurance premiums, healthcare bills and utilities. On October 20, it added business continuity and disaster recovery testing to SHAZAMSecure.
Those additions expand the kinds of work SHAZAM can handle. They also make product fit more specific. FedNow receive access, for example, describes an incoming-payment capability. A buyer should establish whether the proposed service covers its intended use case. Likewise, a third-party core connection needs to match the institution’s actual core and configuration before it becomes a reason to sign.
What another business can borrow
The transferable idea is straightforward: share the expensive infrastructure that customers need, then give its users a formal voice. SHAZAM applies that idea to institutions whose local relationships remain their own. Copying it requires agreement about what to share, how to govern it and how to pay for the work.
For a bank evaluating SHAZAM, the practical next step is a comparison using its actual systems and transaction data. Confirm integration compatibility, conversion effort and expected economics. The promise of cooperation becomes useful when the details fit. A single vote opens the conversation. The machinery still has to work.