The voice on the call sounded like Steve Jobs. It was negotiating an auto-loan payment. The borrower was imaginary, and so was Jobs's participation, but for lenders being courted by two young founders in 2023, the demonstration did something a slide deck could not. It made the future audible. Ari Malik and Mukund Tibrewala had found a way to make a routine collections conversation startling.
They still had to make it legal, dependable and useful. A clever voice cannot decide when a lender may call someone in another state, whether a payment promise has been recorded correctly, or when a distressed borrower needs a person. That gap between convincing and deployable became Salient's business.
- Salient sells AI tools to U.S. consumer lenders for servicing, collections, audits, claims and disputes.
- Its first large customer, Westlake Financial, let the founders build alongside its operations team.
- Westlake's case study reports more than 10 million calls a month and at least $12 million in annual savings.
- Enterprise prices are private; the value test is whether savings and control survive a real pilot.
The expensive life of a loan
A loan is not finished when the contract is signed. Someone misses a payment. Someone wants a due date moved. A car is totaled and its insurer offers less than the lender expects. A borrower disputes a card charge. Each event sends staff into systems, scripts, deadlines and state rules. Malik had seen the cost of this work while working in Tesla's sales finance operation. He and Tibrewala, an engineer who had worked at Airtable and Dropbox, began with auto lenders because the work was both repetitive and consequential.
The founders were friends from high school. They sent hundreds of cold emails to lenders each day, Malik told Y Combinator. Most said no. Westlake Financial said yes to a meeting. The synthetic Jobs call helped them win attention, but a voice impression is a poor answer to a compliance officer's next question: What happens on a real account?
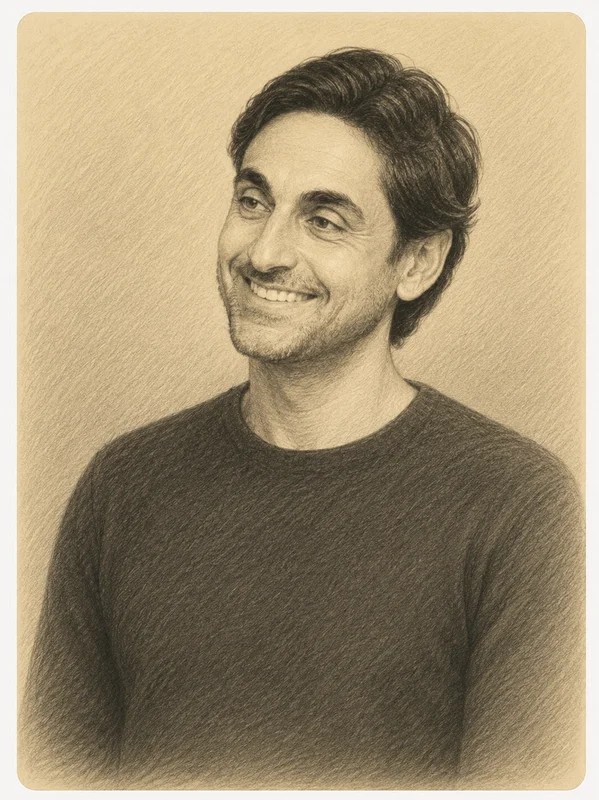
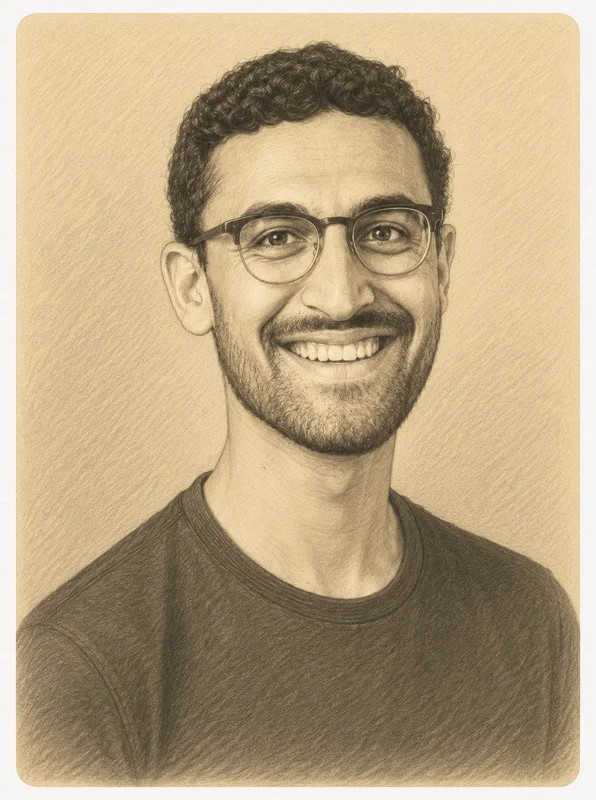
So they moved from San Francisco to Los Angeles and worked beside Westlake's people. The lender and the startup shaped the agent around actual servicing calls. Westlake's case study describes automatic language switching, round-the-clock coverage and full compliance oversight. Its reported results are substantial: more than 10 million calls handled monthly, a 45% reduction in servicing headcount and at least $12 million in annual savings. These are the customer's reported outcomes, measured inside its own operation, rather than a universal promise to any lender that buys the software.
“Both our teams value the velocity of iteration. We gave constant feedback, and saw Salient consistently deliver changes.”Brian Renfro, Westlake executive vice president of servicing
The first technical approach had a ceiling, too. In a Y Combinator interview, Tibrewala said closed models were strong enough to make the original demo, but Salient needed a cheaper way to serve many live calls. Open models, including Llama 2, and the vLLM serving software changed that calculation. He described the jump from roughly a hundred calls a day to hundreds of thousands. The lesson was not that a model won by itself. A model became useful when the company could afford to run it, supervise it and connect it to the lender's work.
Five names for the work behind the phone call
Salient now gives its products first names. Taylor handles inbound and outbound servicing and collections across voice, SMS, email and chat. It can capture a promise to pay, set up an approved arrangement, process a payment and pass a harder conversation to a human. The company says its May 2026 release lets a borrower begin by text and continue by phone without repeating the story. Convenient for the borrower, certainly. More useful to the lender is the continuous account context behind that convenience.
Marshall watches the rulebook. It reviews interactions and account events against lender-approved controls: payment postings, notices, repossession triggers and more. Salient says most manual quality-assurance teams sample only 2% to 5% of calls. Marshall is designed to examine the whole flow and produce an audit trail. Flyn works on total-loss vehicle claims, from challenging a low insurance valuation to filing GAP claims and coordinating lien release. Alex assembles evidence and responses for payment disputes and chargebacks. Melanie covers chargeoff decisions. The names are friendly; the tasks are paperwork with consequences.
One lender, five kinds of unfinished business
A portfolio's work rarely fits in one chatbot window.
American Credit Acceptance offers a second view of the same idea. Its case study reports more than 300,000 Salient-powered calls a month, a 50% cut in confirmation-call costs and 100% compliance coverage across reviewed calls. It also reports a 30% uplift in total-loss settlements. The figures come from the lender and Salient together. They show why an auto lender might buy several connected workflows; they do not prove every portfolio would see the same returns.
Figures from Salient's customer case studies; outcomes depend on each lender's portfolio and deployment.
What the buyer is really comparing
Salient competes first with the existing way of doing the work: human call centers, outsourced teams, dialers, interactive voice response menus and small manual audit samples. General-purpose AI vendors can make a fluent voice too. Salient's pitch is that a lender also needs controlled actions inside its servicing system and a record of why each action was taken. A beautiful conversation that updates the wrong account is an expensive kind of beauty.
Dialer or IVR starts the contact. A human follows a script, changes an account, and a small sample of calls is checked later.
An agent contacts and acts within approved rules; an audit product reviews calls and account events, with escalation for harder cases.
The business is enterprise software, sold through a tailored demonstration, a statement of work and an implementation. Salient says most deployments reach production in 60 to 90 days; its ACA case study describes 12 weeks from contract to testing live calls. For a lender assessing the cost, the sensible comparison is with its present cost per contact, recovery rate, human review burden and the expense of errors. The useful number is the change after a pilot, measured on that lender's own portfolio.
Its buyer also needs enough volume to justify integration. A small lender with few calls and a tidy servicing stack may not see the same payoff. A lender without clean account data or an approved escalation policy would have a different first problem to solve. And a good pilot has to test more than a polite voice: right-party contact, promises kept, disputed actions, state-by-state controls and what happens when the borrower says something the script never anticipated.
The lesson hiding inside the stunt
Salient raised a $60 million Series A led by Andreessen Horowitz in 2025. Its current site says it has raised $75 million in total. Fortune reported annualized recurring revenue above $25 million by December 2025, citing Malik, and an approximately $500 million valuation after additional financing, citing insiders. The numbers suggest fast adoption, though neither revenue nor valuation is an audited public filing.
Its market has widened from auto loans to banks, credit unions and other consumer credit. Consumer Portfolio Services announced a Salient deployment in 2025. Salient's own site lists Westlake, American Credit Acceptance, Ally Financial and Exeter Finance among trusted lenders. JPMorgan Chase selected it for a Hall of Innovation award. Those names matter because lending buyers are conservative for good reasons: their customers, examiners and balance sheets live with a bad deployment.
The copyable part of Salient's story is less theatrical than its opening call. Find a job that costs a customer money every day. Work where that job happens. Learn which exceptions make the old process difficult. Build the controls and the audit record at the same time as the interface. The voice clone got a meeting. Sitting beside the lender turned the meeting into a product. And when the next borrower calls, nobody should need to know which part of the system answered first.