The useful sentence arrived without ceremony: “We’re not picking up the phone.” Rishi Choudhary was a product manager at Redfin, studying a problem inside the company’s Mortgage Marketplace. People had searched for homes, calculated what they could afford and signaled an interest in borrowing. They were unusually promising leads. Yet lenders were failing to convert them. The rates were not necessarily wrong. The customers had not vanished. The phone was simply ringing into an operation without enough hands, speed or software to answer it.
Choudhary dug through the conversion data and called the lenders. Their explanation turned a disappointing chart into a map. Home buying had moved online, where curiosity could become intent in minutes. The operational machinery behind lending still worked to another rhythm. A lead could cross the internet instantly and then wait in a queue built for an earlier decade.
Kastle, the San Francisco company Choudhary later founded with engineer Nitish Poddar, sits inside that pause. Its AI voice and messaging agents help lenders answer loan questions, qualify inquiries and collect payments. They connect with mortgage systems and telephony, write information back into the right records, transfer calls to people when needed and score interactions against quality rules. The voice is the visible part. The less visible integrations are what let the conversation finish a piece of work.
“No borrower should ever wait in a queue to make a payment or get an answer about their loan.”Rishi Choudhary
An Early Taste for Following the Money
The mortgage idea did not appear from a lifelong plan to modernize servicing. Choudhary’s earlier obsession was more domestic and slightly eccentric. Growing up, he has written, he recorded every dollar he spent in a Google Form. Coffee, meals and forgettable subscriptions all went into the ledger. On weekends he made charts and dashboards, looking for patterns in how small charges accumulated or quietly drained an account. Friends thought the ritual was excessive. He was interested in the flow.
That instinct found a larger canvas at the University of Illinois Urbana-Champaign. Choudhary studied Systems Engineering and Design, with a minor in Computer Science. He also led Illinois Business Consulting, a student-run organization that Y Combinator describes as having 250 students and $500,000 in annual recurring revenue. It was an education in systems with human components: teams, clients, deadlines and the diplomatic labor of getting people to move in one direction.
At Redfin, where he joined after college, the systems became consequential. Choudhary was the founding product manager for the Mortgage Marketplace at 22. Y Combinator says he grew its revenue from $3 million to $6 million in nine months. He later led the Search Experience team, responsible for 80 percent of Redfin’s traffic. Search taught him how quickly a consumer can express a need. Mortgage taught him how many operational steps still remain after the click.
The gap Kastle entered
The House That Named the Company
Before Kastle had customers or a Y Combinator batch, it had an improbable piece of real estate. Choudhary was working in Seattle and still paying for an apartment there when a mentor went skiing for four months and offered him a place to stay in San Francisco. The house sat on Twin Peaks with a view across the city. Startup founders lived around him. They called the place the castle.
He paid double rent for months to be there. It was a peculiar financial decision for someone who once graphed every expense, but the environment changed the conversations within reach. A friend connected him with Poddar, whom Choudhary had known at UIUC. Poddar brought experience from Verkada, where he had led infrastructure and work on a patented motion-search system. Choudhary brought mortgage product knowledge and a problem he had watched resist ordinary software.
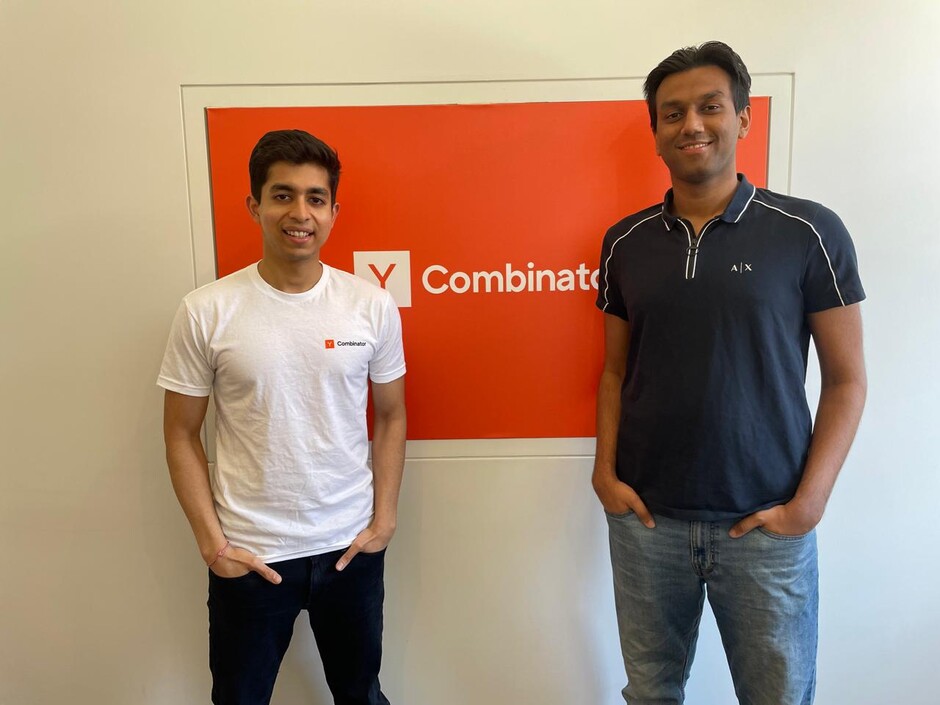
The name acquired a second meaning as the product developed. A castle promises protection, which is convenient when software is handling conversations about money. In consumer lending, a charming demo is only the lobby. The rest of the building needs permissions, data protection, monitoring, defined actions, escalation paths and records that can be inspected later.
Making the Demo Survive Tuesday
Choudhary’s product argument is grounded in control. He has compared the present moment in enterprise AI with the early era of consumer growth product management, when teams were inventing the conventions for activation and experimentation. Banks now need an interface that lets them deploy agents with guardrails without asking every employee to learn a new technical language. The teams that define those controls may shape how institutions use AI long after novelty has worn off.
This is why Kastle’s pitch is full of verbs rather than adjectives. The agent can answer, call, collect, qualify, route, record and score. Each verb touches an existing system or policy. A borrower asking about escrow does not care whether the underlying model is fashionable. The borrower wants an accurate answer. The lender needs the interaction to occur within authorization and quality rules. The institution’s audit team would like to know what happened afterward.
By 2026, Kastle’s recruiting pages said its agents had processed more than $1 billion in transactions and that the company worked with large banks and mortgage lenders. Choudhary told Y Combinator that his work had shifted from fighting internally to build new products at a large company to working directly with bank executives on their AI road maps. It is a change in proximity as much as pace: the product manager who once called lenders to ask why a funnel was breaking now sits with them to decide what software should do next.
The change also sharpens an old product-management lesson: shipping merely opens the door to adoption. Inside a bank, a new agent has many audiences before it has a borrower: operations leaders who need throughput, compliance teams who need boundaries, technologists who need dependable integration and frontline staff who need a clean handoff. Choudhary’s public writing returns to this coordination problem. He argues that enterprise product teams are still inventing the playbook for deploying agents quickly while preserving the controls a large institution expects. The problem is organizational design wearing a software badge. A useful interface must let each group see enough of the machine to trust its part in the workflow.
The Badge Collection
Software for old industries is built partly in conference hotels. Choudhary has admitted that he used to dread mortgage events. He was often the youngest person in a room of veterans who had spent careers learning the regulations, cycles and peculiar vocabulary of the business. Each conference began with unfamiliar faces and the sensation of starting from zero.
He kept going back. The conversations became more candid. People who once needed an introduction began making introductions for him. Choudhary now keeps the badges from those conferences bundled in his room. The stack has become a modest physical graph of trust: one lanyard per room entered before it felt comfortable.
“The conversations get more honest, the rooms start feeling smaller.”Rishi Choudhary
The anecdote corrects an easy misunderstanding about AI companies. A system can automate thousands of interactions, but its right to do so is earned one careful deployment at a time. Mortgage executives do not buy only a voice. They buy the promise that it will behave when call volume spikes, recognize the edge of its authority and leave evidence behind. Relationships carry that promise until performance can.
Studies systems engineering and computer science while leading Illinois Business Consulting.
Joins Redfin and becomes the founding product manager for its Mortgage Marketplace.
Co-founds Kastle with Nitish Poddar and joins Y Combinator's Summer batch.
Discusses production agentic AI for mortgage lending and servicing as Kastle expands its team.
A Company Hidden in the Handoff
Choudhary’s story is less about a sudden revelation than a habit of tracing systems until they become personal. The spending form asked where his own dollars went. The Redfin dashboard asked where valuable borrowers disappeared. The lender’s missed call exposed the handoff between digital intent and institutional action. Even the Twin Peaks house was an experiment in changing the inputs around him, costly enough to make an accountant wince and useful enough to name the result.
His stated ambition remains concrete: a borrower should not wait in a queue to make a payment or get an answer, and a lender should not lose a customer because nobody picked up. Achieving that requires more than teaching software to speak. It requires teaching it where to look, what it may do, when to stop and how to make its work legible to the humans responsible for it.
There is something fitting about a founder fascinated by the movement of money building in mortgage servicing. A home loan is money stretched across decades, paperwork and thousands of ordinary conversations. The industry’s future will still contain calls. Choudhary is betting fewer of them will end with a ring, a queue and the quiet disappearance of intent.