Buying a company gives its new owner an immediate temptation: rearrange the furniture. Merge the departments. Replace the habits. Make the acquisition look reassuringly like everything else already owned. Rob Vitale has spent much of his career examining that temptation, including the occasions when the sensible thing is to leave the furniture alone.
At Post Holdings, the question has practical consequences. A cereal factory, a British breakfast brand and a business supplying eggs to restaurants have different customers and different rhythms. Owning them together creates choices. How much should they share? Who gets the next dollar? When should a business leave? Those questions have followed Vitale from the finance office to the CEO’s chair and, this October, into the role of executive chairman.
A finance education, mostly in St. Louis
His route began with accounting and finance. He started at KPMG in 1987, later managed corporate finance at Boatmen’s Bancshares, and became a partner in Westgate Equity Partners in 1996. From 2006 to 2011 he led AHM Financial Group, an insurance brokerage and wealth management business. The succession of jobs is useful context: before he was responsible for familiar breakfast packages, he was learning how businesses were financed, bought and managed.
His formal education stayed close to home, too. Saint Louis University awarded him a business administration degree in 1988. He completed his professional MBA at Washington University in St. Louis in 1994. These were overlapping years of work and study, rather than a neat procession from classroom to corner office. The institutions would remain part of his public life long after graduation.
A private equity venture with Leo Haas brought him into contact with Bill Stiritz while financing Idaho Pacific, a dehydrated potato business. Vitale later called that mentorship “a second graduate degree.” Stiritz recruited him as Post’s chief financial officer in 2011. It was a relationship that changed both his job and the scale of his decisions.
- 2011Joins Post as CFO
- 2014Becomes president and CEO
- 2025Named board chairman in December
- 2026Becomes executive chairman on October 1
A cereal company starts opening other cupboards
Post emerged from Ralcorp as a separate public company in 2012, with cereal as its sole operating segment. Its subsequent purchases widened the menu: Premier Nutrition in 2013; Michael Foods in 2014; MOM Brands in 2015; Weetabix in 2017; and Bob Evans Farms in 2018. Vitale became CEO during that expansion, in 2014. Reading the names in sequence is like watching a shopping list turn into an organizational chart.
The distinction matters for understanding his work. A brand manager might ask what belongs next to a particular cereal on the shelf. A holding-company executive must also ask whether a business belongs under the same ownership at all. The answer can involve distribution, manufacturing, financing and the people capable of running it. A familiar logo is only the visible portion of the purchase.
By fiscal 2025, Post reported four segments: Post Consumer Brands, Weetabix, Foodservice and Refrigerated Retail. They covered cereal and granola, pet food and nut butters, as well as eggs, potatoes and refrigerated products. This is the context in which Vitale’s decisions should be read. The collection is deliberately broader than the cereal aisle; its parts still have to perform in their own markets.
The business that left, and the shareholders who kept it
BellRing provides a particularly clear example of ownership changing without the underlying business vanishing. Its 2019 initial public offering was followed by another separation in 2022. On March 10 that year, Post completed the distribution of 80.1% of its interest in BellRing to Post shareholders. A business could leave the parent’s consolidated accounts while remaining in those shareholders’ portfolios.
The distribution’s arithmetic was precise: each eligible Post share received 1.267788 BellRing shares. Post continued trading under its own ticker. For a shareholder, the practical result was ownership of two separately traded businesses. For an executive, it was a reminder that the perimeter of a company is a choice, rather than a permanent fence.
Vitale’s connection continued through BellRing’s executive chairmanship. That makes the episode more interesting than a simple story about buying and selling. It separates several things that often get bundled together: control, economic ownership, management responsibility and the identity of the parent company. Growth can change where it is housed. The paperwork is less photogenic than a new product launch, but it can change what investors actually own.
“We’re not afraid to become smaller.”Rob Vitale, 2023
Then the shopping list acquired a dog bowl
On April 28, 2023, Post completed its acquisition of selected pet food brands from J.M. Smucker, including Rachael Ray Nutrish and Nature’s Recipe. The financing combined cash, borrowing proceeds and approximately 5.4 million newly issued Post shares. Even a transaction with recognizable packages on the front had a more complicated set of ingredients behind it.
Later that year came Perfection Pet Foods, whose assets Post acquired effective December 1. That purchase added private label and co-manufactured pet food capabilities. The two announcements describe different ways into the same category: owning brands that shoppers recognize, and owning production that can serve other labels. Both sit comfortably within a career spent considering the business behind the package.
There is an obvious comic pleasure in a cereal company buying dinner for the family dog. The operational question is more sober. A new category brings another set of customers, factories and competitive pressures. It gives the parent additional ways to deploy capital, along with additional ways to be mistaken. A wider portfolio makes judgment more necessary.
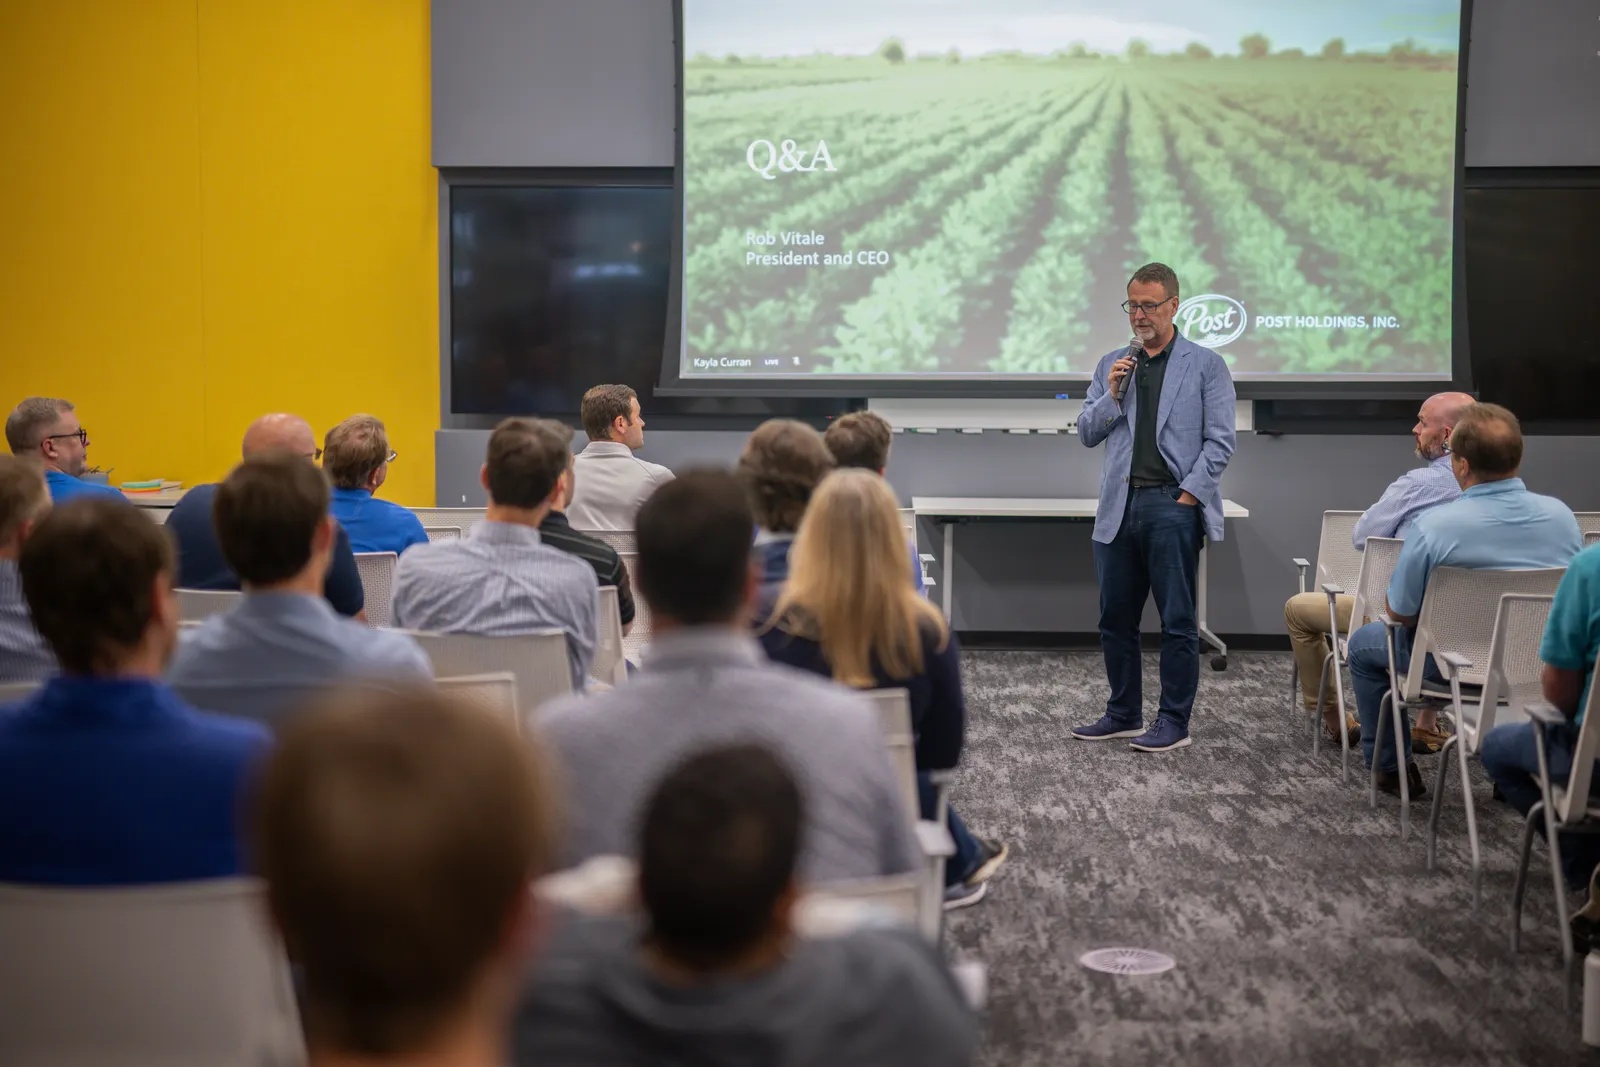
The awkward question belongs in the room
Vitale’s approach to employee questions offers a smaller, more personal view of his management. At quarterly town halls described in 2023, employees could submit questions anonymously, and he asked not to see them beforehand. Colleagues described him seeking out critical voices. The chief executive was making room for an answer he might not enjoy giving.
That arrangement has a useful symmetry with capital allocation. A purchase proposal can look beautifully orderly on paper. Someone still needs permission to ask about the uncomfortable assumption. Inviting that question does not guarantee a sound decision, but it gives the discussion a chance to improve before the money is committed. The same principle applies when the person holding the microphone also holds the most authority.
Buy the whole, sell a part
In June 2025, Post announced an agreement to acquire the remaining interests in 8th Avenue Food & Provisions and extinguish its net debt. The announced net payment was approximately $880 million, including assumed finance leases. The purchase brought Peter Pan peanut butter manufacturing inside Post and expanded its participation in granola. It closed on July 1.
Then came a subtraction. In August, Post agreed to sell 8th Avenue’s pasta business to Richardson for $375 million in cash, with the buyer also assuming approximately $80 million of leaseback financial liabilities. Post would retain nut butters, fruit and nut products, and granola. The pasta sale closed on December 1, 2025.
The sequence makes Vitale’s work unusually tangible. Buying a company need not mean keeping every operation indefinitely. Here, the acquisition and subsequent disposal changed the final combination. It is worth resisting the urge to turn the two announced prices into a tidy profit calculation: the transactions involved debt, leases and different assets. The meaningful point is the choice of what remained.
Transaction sequence, not a calculation of investment returns.
The numbers still have to answer back
Post finished fiscal 2025 with net sales of approximately $8.16 billion. Scale supplies context, rather than a verdict on every purchase. Acquisitions can increase reported sales; disposals can reduce them. A useful reading of a holding company requires attention to what changed inside the reporting perimeter as well as the number printed at the top.
The first quarter of fiscal 2026 illustrated the distinction. Sales rose 10.1% to $2,174.6 million, including $224.6 million from acquisitions. Post also reported cereal category declines and pet food distribution losses affecting Post Consumer Brands. These are less festive details than an acquisition announcement. They belong in the same account of the business, because operating performance is where a transaction’s assumptions meet customers.
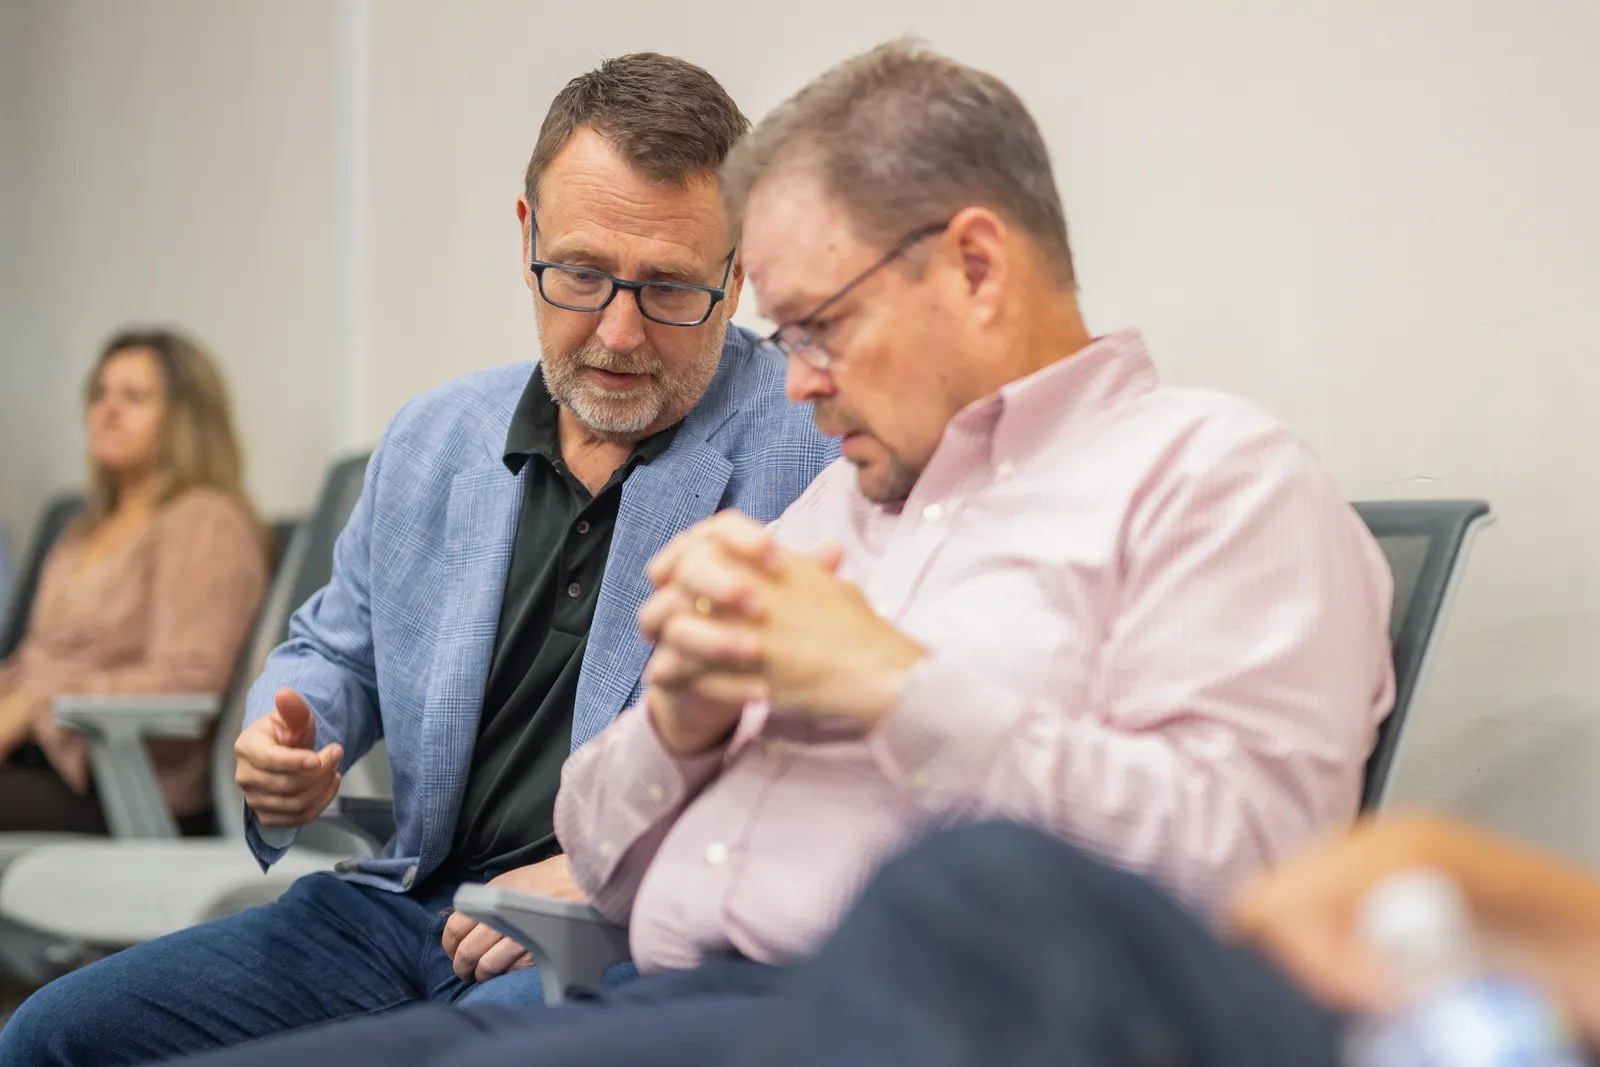
A different chair, a familiar set of questions
Vitale’s public commitments extend beyond Post. He joined Saint Louis University’s board of trustees in 2023, returning to the institution where he earned his undergraduate degree. He has also served on Energizer’s board since 2017. Junior Achievement recognized him in its St. Louis Business Hall of Fame in 2022, alongside World Wide Technology co-founder Jim Kavanaugh.
The CEO succession took effect on October 1, 2026. Nicolas Catoggio, previously Post’s chief operating officer and before that the head of Post Consumer Brands, became president and CEO. Vitale became executive chairman, with a remit to guide capital allocation and advise his successor. The company credited his tenure with more than 50 distinct capital markets and merger-and-acquisition transactions.
Counting transactions is straightforward. Judging them takes longer. For Vitale, the next chapter preserves a role in deciding where money should go while placing the chief executive’s daily responsibilities with Catoggio. The portfolio will continue to change. So will the circumstances around it. After years of purchases, separations and rearrangements, his recurring question remains a practical one: what is worth keeping?