A five-dollar bill lies on a sidewalk. Would you pick it up? Rich Guerrini used that small temptation to open a column about retirement saving. The money was a stand-in for employer contributions left unclaimed when workers skip their retirement plans. In his telling, an ordinary decision about a paycheck becomes a question almost anyone can answer. The expensive machinery of wealth management briefly gives way to a loose banknote.
It is a useful introduction to Guerrini, the Pittsburgh-based president and CEO of PNC Wealth Management. He spends his working life around investments, distribution channels, sales, operations, risk and compliance. Yet his public writing repeatedly returns to the decisions people make before any of those departments can help them: whether to begin saving, whether to sell, whether to ask a question. A retirement account requires paperwork. Leaving tomorrow to chance requires none.
His career has put him on both sides of that conversation. He worked as a financial adviser before becoming an executive, and helped develop PNC's telephone and web-based investment services before leading the business. Across those roles runs a practical concern: how to make financial advice available in the form a client will actually use. The answer has involved a branch, a telephone, a dashboard and, increasingly, the connections between them.
The adviser inside the executive
Guerrini's registration history places him at PNC Brokerage Corp in March 1994. It records earlier securities-industry registrations going back to 1989, followed by a succession of firms and roles. These dates give his career a longer runway than the CEO title suggests. He entered the business before online investing became an everyday activity, then remained involved as customers acquired the ability to inspect their portfolios whenever curiosity struck.
Before becoming chief executive, he served as executive vice president and managing director of alternative investments at PNC Investments. His responsibilities included developing and rolling out the PNC Investment Center and the bank's web-based investment offering. The Investment Center gave clients telephone access to licensed investment service associates. The design question was already present: a customer ought to have a useful route to help even when a branch visit was inconvenient.
By 2012, he had taken the president and CEO role. His remit encompassed the sales, operations, risk and compliance activities of the retail investments organization. It is a job description with several competing clocks. A client wants an answer now; a financial plan may run for decades; an operating process has to work every day. His earlier experience as an adviser gives the executive story its continuity. The subject of the conversation remains the customer's money, even when the responsibility becomes an entire organization.
- 1994Registration at PNC Brokerage Corp
- 2012President and CEO of PNC Investments
- 2014Total Insight pairs digital tools with advisers
- 2026Digital brokerage opening and Premier Client launch
Seven tabs, and somebody to call
In June 2014, PNC introduced Total Insight, combining online and mobile financial tools with access to a dedicated adviser. Customers could review investments, assets and liabilities together, including accounts held elsewhere. The dashboard organized the picture into seven tabs. A financial life scattered across institutions could, at least on screen, occupy one address.
The service also offered meetings at a bank branch or access through Advisor Direct by telephone. Guerrini described the adviser as a companion to the analytical tools. This was a specific operating choice: the client could use software without surrendering the option to talk. A chart might show where the money had gone. A conversation could address why it was there.
That launch matters because it makes the later strategy easier to understand. The current emphasis on connected banking and investing has a documented predecessor more than a decade earlier. Guerrini was already working on a combination that would become a recurring feature of his leadership: give customers a clearer view of their finances and a person who can help interpret it. There is a modest courtesy in that arrangement. Nobody has to pretend that seven tabs constitute seven answers.
A writer with a five-dollar opening
His articles offer a view of how he explains the business when he has more room than a launch announcement allows. In a 2023 series on retirement income, he moved through managed accounts, annuities, bonds, brokered certificates of deposit and cash reserves. The subjects are familiar, but the sequence reveals his focus: how different financial tools might serve different jobs after a paycheck stops arriving.
The cash-reserve installment explored bank sweeps, money market funds and short-term CDs. Its attention went to access, potential income, fees and restrictions. This is the unglamorous territory of financial planning: making sure money is available when it is needed, while considering what it might earn in the meantime. There are few dinner-party bragging rights in an efficiently organized reserve. Guerrini nevertheless gave it a whole installment.
His May 2024 retirement-saving column began with the five-dollar bill and went on to illustrate how the same monthly contribution can produce very different outcomes depending on when saving begins. The point was time. The opening did something more subtle: it translated an employer match from a benefit buried in workplace documents into an opportunity a reader could picture passing on the pavement.
Another column examined exchange-traded funds. He considered convenience, fees and the choice between active and passive strategies, then returned to the investor's goals. In a separate discussion of Roth and traditional retirement accounts, he allowed for a combination rather than insisting on one universal winner. Read together, these pieces suggest an explanatory habit: start with the tool, ask what it is supposed to accomplish, and leave room for circumstances to change the answer.
“There is a difference between what you're invested in and what you've invested for.”
Rich Guerrini, March 2025
Finding room between ordinary banking and private banking
By late 2024, the business was putting more emphasis on clients described in banking language as mass affluent. PNC hired Brendan Krebs to lead and expand its Wealth Advisor team, reporting to Guerrini. The announcement tied the appointment directly to that client segment. Hiring a leader with advisory, recruiting and management experience gave the strategy a human counterpart to its technology.
The phrase mass affluent can sound as though somebody has misplaced the word people. The underlying problem is recognizable: an individual or family may accumulate meaningful savings, several accounts and increasingly complicated decisions before qualifying for private-bank service. The business opportunity lies in bringing those pieces together earlier, while the relationship is still taking shape.
In February 2026, PNC introduced Premier Client. It paired personal bankers and financial advisers, adding enhanced servicing and a plan to transform 200 existing locations into Premier Branches through 2027. The offering addressed customers with more than $100,000 at PNC. Those are program details, rather than measures of Guerrini's personal wealth; they describe whom his organization was setting out to serve.
Guerrini framed the next phase around increasingly complex client finances. The ambition was to combine guidance, service, technology and products in one experience. That carries an organizational challenge as well as a marketing promise. Banking and investing have to work together closely enough that the customer does not have to act as the messenger between them.
banker+Financial
adviser
through 2027
A screen that leaves the conversation open
A few weeks before Premier Client's launch, PNC enabled online banking customers to open and fund individual brokerage accounts digitally. The January 2026 announcement emphasized less paperwork and fewer obstacles. The investing platform included online stock and ETF trades with no commission, fractional shares, tax-lot trading and easier transfers between banking and investment accounts.
Customers retained the ability to work with a financial adviser. Guerrini's description of the change stressed meeting clients at their particular stage of investing. The implementation required collaboration between Wealth Management and other teams across PNC. Underneath the easy account opening was the less visible work of making departments cooperate.
In July, he returned to the relationship between technology and advice, saying that technology should help the adviser-client relationship function more effectively. His emphasis was on access and perspective. A digital service can make a conversation easier to arrange and give both participants a current view of the accounts. The difficult judgment about what a decision means for a family still requires attention.
There is a consistent business argument here, stretching back to the telephone service and the 2014 dashboard. Each new channel adds another opportunity to engage. For Guerrini, the screen is part of the service architecture. Its usefulness grows when the customer can move from looking at a number to asking a question about it.
The check outside the office
Another public record puts Guerrini in a different setting. In 2019, Make-A-Wish Greater Pennsylvania and West Virginia listed Richard R. Guerrini as its board chair. Its spring newsletter also described a PNC Investments donation from the eighteenth annual PNC Golf Outing and Dinner, led by committee chair Walter Scheide and Guerrini. The accompanying photograph shows the team gathered around a presentation check for $80,000.
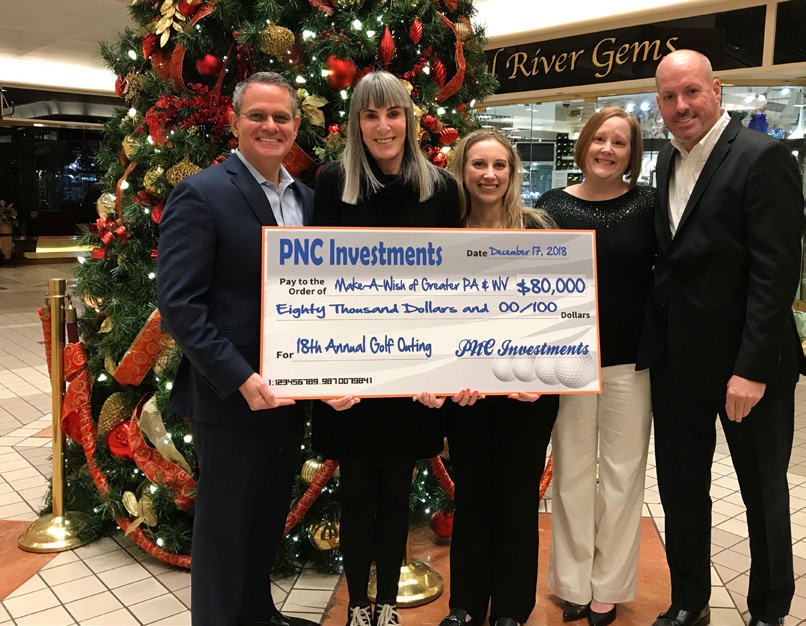
The image supplies a useful change of scale. The work is local, the participants are standing together, and the amount has an immediate destination. It places a community board role alongside the executive responsibilities. Here the connection between an organization and the people around it is visible without a dashboard.
The next expense, the longer plan
In July 2026, PNC Wealth Management added a securities-based lending offering for eligible Premier Client customers. In September, Guerrini wrote about borrowing against investments, including circumstances in which it may be unsuitable. He discussed repayment, interest-rate exposure and the possibility that a falling portfolio could require more collateral or force a sale. Keeping investments in place carries obligations when those investments secure a loan.
That combination of product development and explanation brings his career into focus. Guerrini has spent years helping build ways to reach investors, while writing about the choices those investors face once they arrive. The five-dollar opening, the seven-tab dashboard and the paired banker and adviser belong to the same practical ambition: help people connect today's decisions with the future they intend to finance. The next useful step may be a click. It may also be a second conversation.
Follow the conversation
- PNC · employer website
- Rich Guerrini · LinkedIn
- Read his financial columns
- The 2014 Total Insight launch
- Brendan Krebs joins the Wealth Advisor team
- Digital brokerage opening · January 2026
- Premier Client · February 2026
- Digital delivery and adviser relationships
- Borrowing against a portfolio · September 2026
- Listen · Money Life with Chuck Jaffe, 2019
- Community newsletter · spring 2019
- Career and registrations · FINRA
- Executive appointment · FINRA firm record
- The five-dollar opening · May 2024
- Retirement cash reserves
- Roth and traditional accounts
- Exchange-traded funds
- Planning through market swings
- Securities-based lending launch
- Coordinated wealth planning