Payday has always enjoyed the authority of weather. It arrives when the calendar says it will, and everybody else is expected to make plans around it. Quan Nguyen looked at that arrangement and noticed a peculiar delay. The worker had completed the shift. The money had been earned. Yet the cash remained on the far side of Friday, while rent, school fees and household bills showed no comparable respect for the payroll cycle.
That interval became the raw material for Gimo, the Hanoi company Nguyen co-founded in 2019. Its first proposition was earned wage access: connect with an employer, track wages already accumulated and let an eligible employee draw a controlled portion before the scheduled payday. The idea sounds almost impolite in its simplicity. If the work is finished, why should the worker’s own income remain locked behind a date?
Nguyen came to the question from the formal side of money. He had spent more than a decade across consumer banking and investment, including work connected with Citibank Vietnam, Leadvisors Capital and IDG Capital. He had managed banking business and worked on capital raising and debt-market investments. An Executive MBA at the University of Hawaii at Manoa’s Shidler College of Business added another respectable line to an already respectable career.
Respectability, however, can be a very well-upholstered chair. Nguyen has spoken about feeling demotivated by corporate life even while work was going well. The degree changed his mindset. Eventually, he left in search of something he considered more meaningful. The pivot was not from failure to adventure. It was from success to uncertainty, a transaction for which no spreadsheet offers a comfortable discount rate.
A problem hiding between two dates
Vietnam’s expansion of banking access did not make every banked person financially included. Formal credit remained out of reach for many low-income and rural workers. A surprise expense could push someone toward informal lenders even when that person held a steady job. Gimo’s own early worker research reported that only 27 percent of more than 700 blue-collar respondents could handle a financial emergency. The company was not searching for an exotic habit to invent. It was responding to a familiar pressure.
Earned wage access works only if its limits are as carefully designed as its convenience. Gimo has described caps on the share of monthly earnings that can be withdrawn, fixed transaction fees arranged in tiers and financial education inside and outside the app. It partners with employers in industries including textiles, electronics and mechanical manufacturing, where the payroll relationship provides both distribution and a record of wages earned.
The employer channel is a quiet strategic advantage. Consumer finance companies often pay dearly to find each customer, then must establish trust from a cold start. Gimo arrives through a workplace relationship already in motion. The employer gains a benefit intended to support retention and engagement. The worker gains an app built around income that actually exists. Gimo gains a route to groups of users without buying their attention one advertisement at a time.
“Technology is what helps us solve the problems of ourselves, our target customers and society as a whole.”Quan Nguyen
A finance founder learns to build technology
Nguyen did not arrive pretending to be an engineer. He has been candid that starting a technology company without a technology background was difficult. His answer was complementary talent. Co-founder Nguyen Van Ngoc brought technology and product experience; Nguyen brought finance, markets and the instinct to begin with the user’s problem. This is less cinematic than a solitary genius at a whiteboard, but considerably more useful.
His formulation is straightforward: understand the user’s pain point, then create products and features that answer it. Technology is an instrument, not a personality. That view helped Gimo pivot toward early wage access and later widen its product frame. By 2025, Nguyen was describing a comprehensive employee benefits platform with payments, insurance, education and other services around the worker. The humble wedge was access to earned pay; the broader ambition was a useful financial relationship.
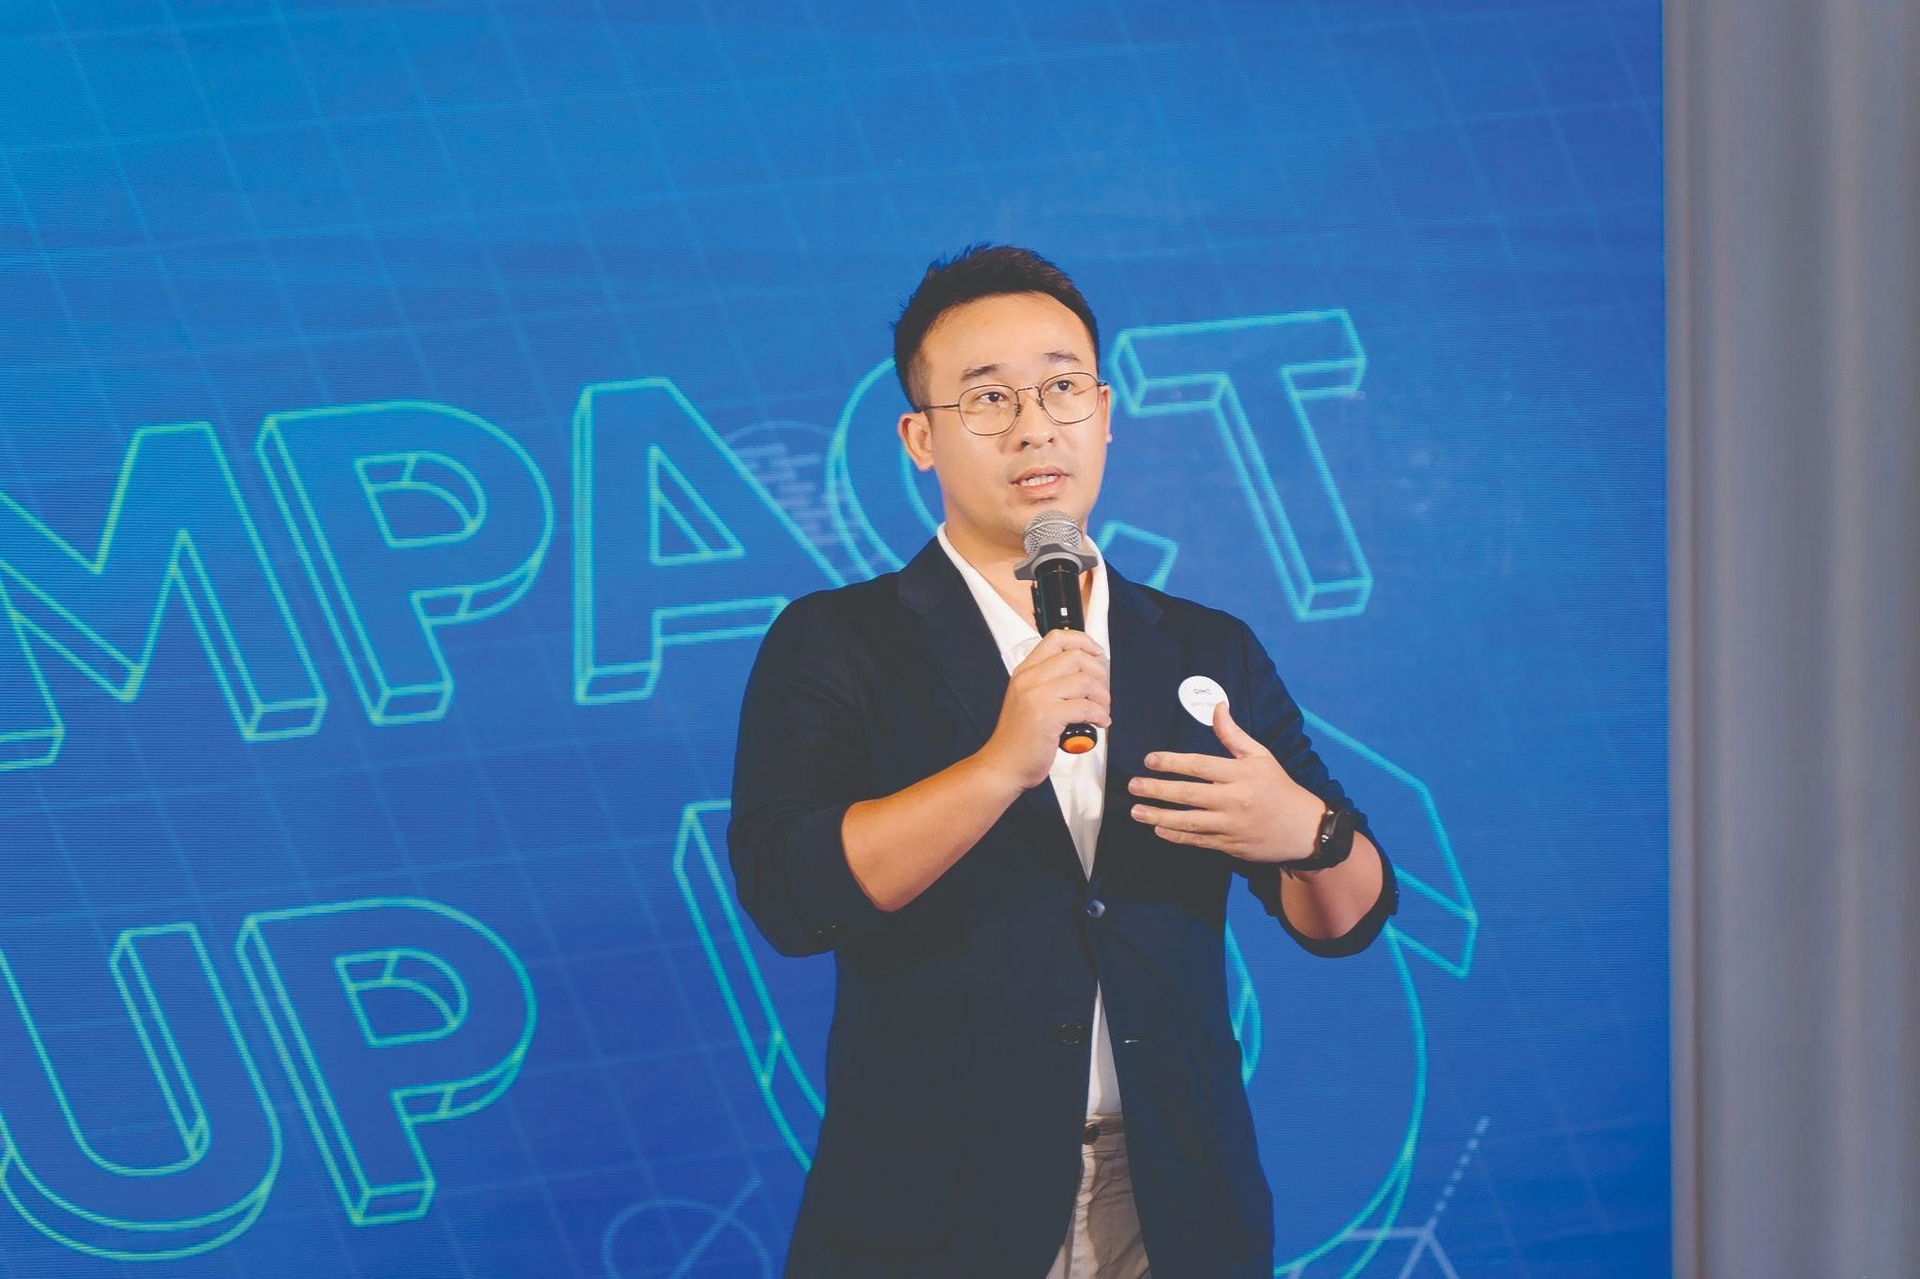
Gimo formally launched its app in early 2021. By mid-2022, it said the service covered 35,000 workers and carried a year-end target of 180,000. The company joined Y Combinator’s Winter 2022 batch, a credential that brought attention but no exemption from local execution. Payroll integrations still had to work. Employers still had to sign. Workers still had to trust the service. Regulation, information security and credit risk did not become less Vietnamese because an accelerator was based in California.
Capital followed the operating case. Gimo raised a US$1.9 million seed extension in 2021. In 2023, it announced a Series A totaling up to US$17.1 million in equity and debt financing, with TNB Aura leading and existing investors participating. Nguyen’s praise for that investor focused on something telling: its detailed thesis on earned wage access and hands-on work around financial inclusion, ESG risk and disclosure. He was looking for aligned scrutiny, not merely an impressive wire transfer.
The useful art of asking
Nguyen’s advice to young founders is gloriously short on incense. Ask. Ask accelerators and investors for what the company needs. Ask for as much useful support as possible. Do not let embarrassment decide the runway. His reasoning moves the question away from personal pride: if the founder stays shy, the company may not have the money to pay the people who trusted it enough to join.
It is easy to mistake this for a license to become a nuisance. The deeper point is responsibility. A founder’s reluctance can be expensive for everyone else. Specific requests create motion: an introduction to an employer, an objection from a regulator, a careful investor’s challenge, a co-founder whose skills cover your blind side. Resourcefulness is often social before it is technical.
“If we are shy, it will be very difficult to reach our opportunities.”Quan Nguyen
He has summarized Gimo’s origin with three absences: no revenue, no customer and no fear. The line is tidy; the years after it were not. The company moved through a pandemic, fundraising cycles and the slow sales rhythm of employers. It had to explain that early access to earned income differs from a conventional loan, then prove that distinction through product limits, transparent charges and measured risk.
Growing people, widening the platform
The most personal glimpse of Nguyen’s operating style arrived in a promotion announcement. Five years earlier, Amanda Do had joined Gimo as his executive assistant after returning from more than seven years in Canada. She knew little about fintech startups. She moved through roles including chief of staff and project director, then became chief growth officer and a board member in 2026.
Nguyen framed her rise as the culture he wanted: leaders developed through ownership, learning and the opportunity to grow. It is a useful counterpoint to the familiar startup obsession with recruiting finished products. Gimo’s version of talent appears closer to its version of finance. Give people responsible access to something they have already begun to earn, then let capability compound.
By the company’s fifth anniversary, Nguyen said Gimo had 72 team members in Hanoi and Ho Chi Minh City, served more than 800,000 workers at more than 200 companies and was averaging 80 percent year-on-year revenue growth while keeping credit risk in what he called a healthy range. These are company-reported figures, but the direction is clear: a single payday feature has become a distribution base for a wider set of worker services.
That widening brings tension. More products create more ways to help and more ways to lose focus. Nguyen’s stated safeguards are conventional because conventional safeguards matter: legal compliance, transparency, information security, investment in people and flexibility in execution without abandoning the long-term vision. Fintech’s sharpest edges are rarely softened by clever copy.
A 2025 partnership with EVNFinance placed that approach inside a larger institutional relationship, aimed at expanding accessible and responsible digital financial products. In the same year, Gimo’s app received a Top 10 Sao Khue award in the category for solutions promoting digital access. Awards decorate the shelf. Partnerships, integrations and repeated use determine whether the shelf has an office around it.
The calendar is the product
Nguyen’s aspiration is to reach millions of workers with fair, transparent and sustainable access to digital financial services. The language is broad, but the origin remains wonderfully concrete. A person works on Monday. A bill arrives on Wednesday. Payday is Friday. Gimo asks whether finance can acknowledge the first event before the third.
The company still has to navigate the hard, unromantic work of risk, regulation and employer adoption. Its future will depend on whether a broader benefits platform remains as intelligible as its first proposition. Yet the founding observation endures. Some of the most consequential design choices are not hidden inside code. They are hiding in the intervals that institutions have taught everyone to accept.
Nguyen left a career built around moving capital at institutional scale to work on the timing of an individual wage. The distance between those jobs is smaller than it looks. Both are arguments about who gets money, when they get it and what trust must exist first. One came with polished offices and established rules. The other began with no revenue, no customers and an admirably inconvenient question for the calendar.