Progress Software began with four people, a dining-room table and a PC-AT that had a 256K floppy drive but no hard disk. Forty-five years later, the Burlington, Massachusetts company owns a collection of software that sits in places most consumers never look: inside business applications, beneath websites, between databases, across networks and in the pipes that move sensitive files. The old machine is gone. The instinct to work below the surface is not.
Progress is difficult to explain in one clean noun. It is a developer-tools company through Telerik and Kendo UI, an application platform through OpenEdge, a content-management vendor through Sitefinity, a DevOps supplier through Chef, a data company through MarkLogic and Semaphore, a network operator’s toolbox through WhatsUp Gold and Kemp, and a document-workflow business through ShareFile. The pieces do not resemble a seamless consumer ecosystem. They resemble a very organized hardware store.
That is the point. Progress buys specialist products that enterprises and software vendors already depend on. It gives them R&D, global sales coverage and a larger customer base, while retaining the practical job each product was hired to do. The corporate target is blunt: double the size of the company every five years.
A portfolio built around expensive goodbyes
The best way to understand the business is to ask how annoying it would be to leave. OpenEdge applications can encode years of industry logic. UI components sit throughout a front end. Chef policies touch fleets of machines. A CMS accumulates templates, permissions and content. MOVEit or ShareFile becomes part of how regulated documents travel. Replacing any one of them is possible. Doing so is rarely a pleasant quarter.
That embeddedness produces the recurring revenue Progress wants. In fiscal 2025, maintenance supplied 42 percent of revenue, SaaS 29 percent, software licenses 24 percent and professional services roughly 4 percent. ShareFile made the mix look dramatically more cloud-like: SaaS revenue rose to $287.9 million from $44.6 million a year earlier. This was not a sudden invention in Burlington. It was purchased.
Progress paid a headline $875 million for ShareFile in October 2024, funding the deal with cash and its revolving credit line. Net cash paid at closing was $852.7 million. The board suspended the quarterly dividend and redirected capital toward debt repayment. In fiscal 2025, ShareFile contributed $261.6 million of revenue, the main reason total company revenue jumped 30 percent.
Progress shops with a large cart
The proposed next purchase is Domo’s AI and data platform business. Progress agreed in July 2026 to pay $400 million in cash for substantially all Domo assets and certain liabilities. If regulators approve it, the deal adds more than 2,400 business customers plus tools for preparing, visualizing and automating data. It also makes the company’s new AI language less cosmetic. MarkLogic brings a multi-model database, Semaphore brings semantic metadata, Nuclia brings retrieval technology, and Domo would add a broad cloud data layer.
“Effective AI starts with accurate, trusted data and content.”Yogesh Gupta · Chief executive officer
What customers are actually buying
A bank’s digital team can use Sitefinity to run governed websites while developers use Kendo UI components to build the interface. An independent software vendor can build a vertical application on OpenEdge and sell it for decades. An infrastructure group can use Chef to automate configuration and compliance across cloud and on-premises machines. A law or accounting firm can give clients a ShareFile portal for documents, signatures and workflows. A government agency can use MarkLogic to retrieve information spread across sensitive, messy data.
The customer list therefore ranges from software vendors and systems integrators to finance, healthcare, retail, professional services and public agencies. Progress says more than 200,000 organizations and over 4 million developers and technologists use its products. Customers do not need to accept an all-or-nothing platform. They can buy one sharp tool, which is a meaningful difference from the grand-suite pitch made by Microsoft, Oracle, IBM or Adobe.
The alternatives vary by aisle. OutSystems and Mendix compete in low-code development. DevExpress, Syncfusion and open-source libraries compete with Telerik. Adobe Experience Manager, Sitecore and Acquia face Sitefinity. HashiCorp, Red Hat Ansible and Puppet overlap with Chef. GoAnywhere, Axway and IBM Sterling compete in managed file transfer. F5 competes in application delivery. Box, Dropbox and Microsoft 365 compete in document collaboration. Progress’s advantage is breadth of distribution across narrow markets, not undisputed leadership in one giant category.
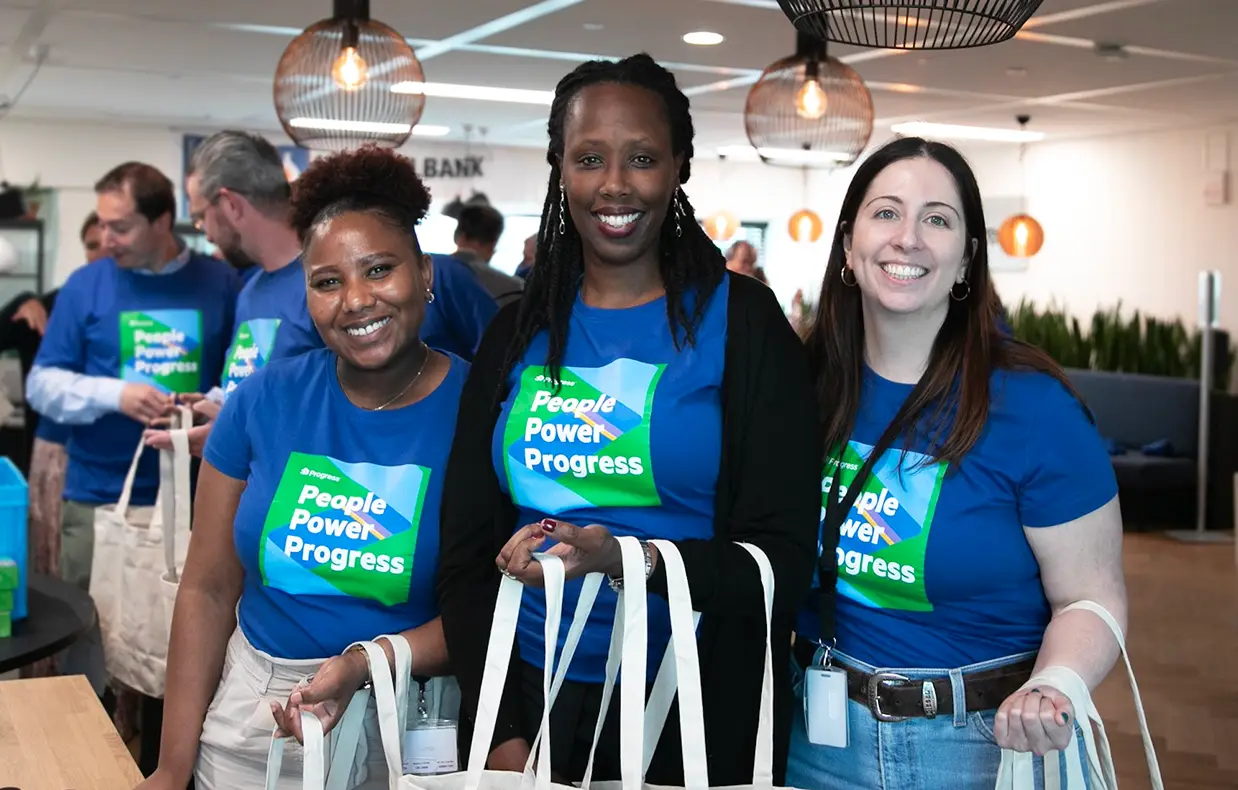
The company supports that reach with 2,801 employees as of November 2025: 1,048 in product development, 932 in sales and marketing, 523 in customer support and services, and 298 in administration. Its stated culture centers on courage, teamwork and accountability, with flexible work and offices treated as collaboration spaces. The 2025 responsibility report says more than 90 percent of employees adopted AI-powered tools, and the company ran more than 40 well-being initiatives and supported over 290 charities.
The small product that created a giant problem
Infrastructure software sells trust, which is why the MOVEit breach matters beyond one product. On the evening of May 28, 2023, Progress learned that attackers had exploited a zero-day vulnerability in MOVEit Transfer and MOVEit Cloud. The Cl0p group used the flaw to exfiltrate data from customer-controlled environments. Organizations ranging from corporations to government and healthcare entities later reported exposures.
What failed first was not the acquisition strategy or the balance sheet. It was a security boundary in a product designed to move sensitive information safely. Progress patched the flaw and additional vulnerabilities, brought in outside specialists, supported customers and cooperated with regulators. The incident still produced multidistrict litigation and years of legal and professional work.
The disclosed net bill through fiscal 2025 was $9.9 million: $1.5 million in 2023, $5.6 million in 2024 and $2.8 million in 2025, after insurance recoveries. That is not the final cost. Progress said it could not reasonably estimate eventual judgments, settlements or penalties. MOVEit Transfer and Cloud represented less than 3 percent of fiscal 2025 revenue, a useful reminder that portfolio risk does not arrive in proportion to portfolio revenue.
The incident also changed the terms of the company’s promise. Progress now frames AI around context and control, with security, governance and verifiable answers at the center. The shift is commercially convenient, but it is also rational. If the company wants customers to entrust more documents, workflows and enterprise data to its products, proof of control matters more than another chatbot button.
The playbook worth stealing - carefully
Operators can copy several parts of the Progress method without copying the deal size. Start with products that solve a specific, recurring problem and have users who know exactly why they pay. Look for retention, maintenance economics and distribution overlap before promising technological synergy. Give the acquired team a clear integration path. Preserve the product identity long enough that loyal users do not feel purchased and abandoned. Then use cash flow to reduce leverage before returning to the market.
Four filters before buying “boring” software
- Customers renew because the product performs a job, not because the contract traps them.
- The acquirer can improve distribution without scrambling the product roadmap.
- Security and support investment grows with the installed base.
- Debt still works if integration takes longer than the spreadsheet predicts.
The model will not work under every condition. It breaks when churn is disguised by long contracts, when maintenance becomes neglect, when debt removes the freedom to invest, or when too many independent products overwhelm sales and security teams. It also struggles when a fast-moving market rewards a coherent platform more than a useful cabinet. Open-source alternatives can squeeze pricing, and larger rivals can bundle competing features into existing agreements.
Progress has avoided pretending those pressures do not exist. Its annual filing says it faces rivals with deeper technical and marketing resources and does not claim a dominant position. The bet is more modest: there will remain a large market for proven tools that fit the systems companies already have. In enterprise software, modest can be durable.
The old Progress was a product company born before the modern PC market. The current Progress is a capital allocator with a product-development department, a global channel and a practiced integration team. ShareFile showed how quickly one acquisition can rewrite the income statement. MOVEit showed how one narrow product can rewrite the risk section. Domo, if it closes, will show whether the cabinet can become a credible data foundation for AI.
That makes Progress interesting precisely because it is not fashionable. It is a company built around software’s least cinematic fact: once a useful tool is wired into real work, the boring choice is often to keep it. Progress wants to own that choice, collect the renewal and buy the next one.