For more than twenty years, Ed Smith built Agile Fleet without outside funding. Then came a different kind of engineering problem: finding the next owner. His company made software for managing and sharing vehicles. Choosing a buyer meant deciding what would happen to a business he had spent decades assembling. Progress Partners advised on the sale.
- Progress advises businesses on selling, buying and raising capital.
- Its roots are in media and advertising technology; its mandates now stretch into fleet software and government technology.
- The practical lesson: decide what you want ownership to accomplish before choosing a transaction.
The buyer after twenty years
In June 2025, Agile Fleet’s sale to Banyan Software was announced. Progress says it ran a process that attracted several qualified buyers. Banyan brought a particular proposition: long-term ownership of software companies serving specific markets. For a founder, that changes the conversation. Price matters. So does the buyer’s plan for the thing being bought.
This is where Progress becomes easier to understand. Investment banking can sound like an elaborate way of moving numbers between spreadsheets. Here, the work included understanding a fleet-management business, explaining its value to prospective buyers and creating choices for its founder. A software company with years of operating history needed someone who could translate that history into an acquisition argument.
Progress was founded in 2002 by Nick MacShane, whose background and relationships sit in media and marketing technology. His biography connects the firm’s beginnings to a belief in the importance of free media. The resulting practice has advised businesses around advertising, software and digital distribution. Its transaction list also contains less obvious names. Bose hired Progress as its exclusive financial adviser for the sale of Bose Professional to Transom Capital in 2023.
A network with a day job
Progress offers four routes: acquisitions, capital raising, strategic growth advice and exits. Its customers are founders, executives, investors and corporate owners facing consequential choices. This is a professional-services business built around engagements. A client brings a transaction or strategic problem; Progress contributes advice, market knowledge and execution.
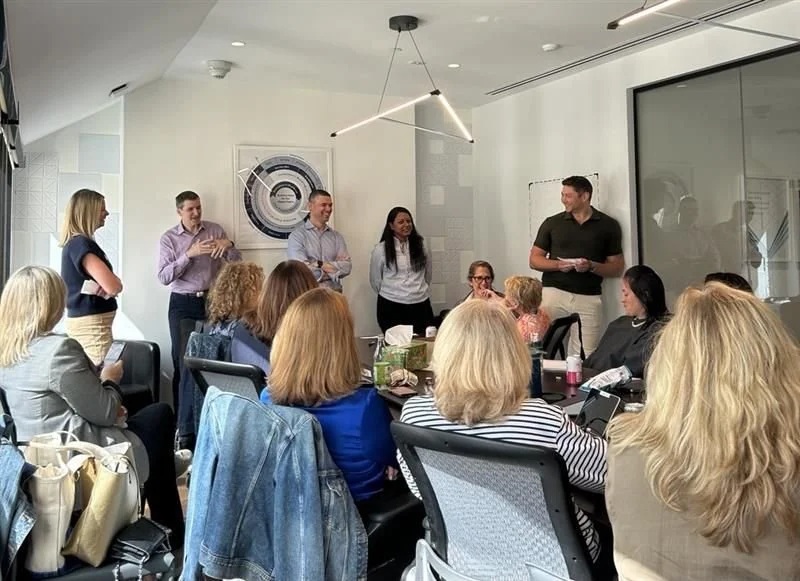
Its more distinctive piece is the Executive-in-Residence network. The current directory lists 125 active executives across seven sectors. These are operators, investors and industry leaders whose experience extends beyond the bankers’ desks. Jessica Straw directs the network, which brings members together through discussions and events.
Consider the difference between knowing that advertising technology is consolidating and knowing how an agency actually buys software. An operator may see switching costs, awkward workflows or customer dependencies that a financial model cannot explain on its own. That is the logic of the network. It gives Progress more people to consult about what a business does and why another company might want it.
Relationships alone do not separate Progress from the field. LUMA Partners, another specialist in digital media and marketing, also emphasizes sector knowledge and access to decision-makers. Progress’s proposition combines its advisory team, executive network and related venture platform. A founder comparing advisers should examine relevant experience and the people doing the work.
Forty million reasons to keep building
In March 2026, Keynes announced a $40 million minority investment from Volition Capital. Keynes works in connected-TV advertising, helping brands target audiences and measure results across streaming television. Progress advised on the financing. The announced plan put money toward technology, data, measurement and hiring while maintaining continuity in leadership and strategy.
“it’s turned out to be what we really want”
Dan Larkman, founder and CEO of Keynes, in a Progress-published testimonial
Larkman’s testimonial on Progress’s website mentions having considered a strategic deal before this investment. The useful detail is the eventual structure: minority growth capital. A founder can bring in an investor without selling the entire company. Ownership has degrees, and the decision about how much to sell belongs alongside the decision about how much money to raise.
March 2026 · transaction capital
That $40 million is capital invested in Keynes. It says nothing about Progress’s fee. It also illustrates why counting every financing as an “exit” misses something. For Keynes, the announced transaction supplied resources for further expansion. The founders’ next task was still to operate the business.
The same question, different businesses
Other assignments show the range. In 2024, Progress advised Pathlabs on its acquisition by MiQ. Pathlabs supplied digital-media execution services to independent agencies. The announced arrangement kept its brand and made it an independent business unit within MiQ. The combination paired a service operation with a larger programmatic advertising business.
In September 2026, Progress advised Moonshot Partners on buying CustomWeather. Moonshot wanted to build around earth, weather, climate and geospatial data. CustomWeather supplied forecasts and data covering more than 85,000 locations worldwide. The buyer cited cultural alignment and the platform’s distinctive value. Here, Progress represented the acquirer, helping turn an investment thesis into a specific purchase.
The related Progress Ventures platform adds another activity: investing in early- and growth-stage B2B technology companies. It dates its investing to 2008 and focuses on advertising, marketing, commerce and media. Advisory clients and venture investments are different relationships. Both draw on familiarity with how these markets work.
Sometimes the assignment is to draw a boundary inside an existing company. Bose sold its commercial installation and conferencing businesses while retaining portable PA systems. In September 2026, Apriva divested its government-technology subsidiary to ITC Federal while keeping its commercial payments division. Progress advised on both transactions. A company does not always need a single future for everything it owns. Separating businesses can give each a different owner, investment plan and set of customers to concentrate on.
What a founder can borrow
The repeatable idea is to write down the desired outcome before choosing the financial instrument. Agile Fleet’s process emphasized a long-term owner. Keynes brought in minority capital. Moonshot acquired a foundation for a broader strategy. Each transaction answered a different operating question.
That approach requires a business counterparties can understand, credible information and priorities that survive negotiation. Introductions cannot resolve every disagreement over price, control or timing. A useful first conversation with an adviser therefore begins with what must be true after closing. The right next meeting follows from that answer.