Oren Bass had a fairly specific answer to the question of how to get something done. In 2013, he described beginning his day at six, writing down goals and working backwards through the steps required to reach them. He preferred a short list. Too many intentions could leave a person with plenty to contemplate and nothing accomplished. It was a practical account of ambition, offered while he was helping build a business that asked strangers to put money behind someone else’s future.
That business was Pave. Its early customers were young people with plans that conventional finance could struggle to accommodate. A career might be promising before it was profitable. A person might need money precisely when their record was too short to make borrowing straightforward. Bass and his co-founders wanted backers to consider what came next.
The proposition would change. So would the customers, the institutions and the scale of Bass’s work. Follow his career into corporate inventory finance and the scenery becomes almost comically different: a young person asking for a chance gives way to a multinational trying to manage its stock. The connecting question is an interpretation of that route, rather than a motto he supplied: can finance become more useful by looking harder at the circumstances behind the application?
Twenty-two people willing to take a chance
Pave’s December 2012 pilot started with eight prospects and 22 backers. Bass was its chief operating officer. The arrangement combined money with introductions and advice; backers would receive a share of the recipient’s future income. It was a funding relationship with rather more conversation built into it than the average repayment notice.
The intended audience extended beyond technology entrepreneurs. Art, music, athletics and architecture appeared in the launch announcement. The founders were asking whether the sort of support routinely discussed around businesses could also be organized around an individual career. For an aspiring professional, a useful introduction could matter alongside the cheque. For a backer, participating meant having something to offer beyond cash.
“Pave is for everyone”
Oren Bass, Pave pilot announcement, 2012
By February 2014, Bass was discussing another version of the proposition: funding groups. People with an interest in a particular field could support a collection of emerging professionals. The idea addressed both sides of the marketplace. Applicants needed flexible support early in their careers; experienced backers wanted a connection to the work and people they were helping.
During a March 2014 interview, Bass described about 7,000 registrations, split between roughly 5,500 applicants and 1,500 prospective backers. Those were registrations, with all the distance that can separate signing up from completing a transaction. Even so, the split gave the experiment a recognizable shape. There were many people ready to explain their potential, and a smaller population considering whether to finance it.
The contract changes
In August 2014, Pave introduced the Pave Loan. Bass and Sal Lahoud described a broader access problem than they had first understood. They argued that traditional underwriting could overstate the risk presented by young adults with limited credit histories. The company’s answer now used a familiar lending agreement while continuing to question how the applicant should be assessed.
The distinction mattered. An income-linked agreement asks a backer to participate in an uncertain future salary. A personal loan specifies a debt to repay. Both can provide money for a career move, but the promises are different. Changing the agreement changes what each participant needs to understand, and what the business must administer afterwards.
Investor access remained part of the discussion. In early 2015, Pave’s investors committed at least $10,000 to a pool of loans. Bass wanted regulatory changes that would permit participation by people outside the accredited-investor category and allow investors more choice over the loans they funded. The original interest in connecting people to capital survived inside a more conventional product.
A nationwide platform announcement followed in July 2015, identifying Bass as co-founder and CEO. The pitch emphasized a clearer borrowing experience and a product suited to millennial careers. It was a substantial change in presentation from the intimate language of prospects and backers. The operating challenge now included reaching borrowers across the United States.
Capital arrived too. An $8 million investment round was reported in spring 2016, with Maxfield Capital among the investors. A March securities filing carries Bass’s signature as CEO. These are useful, unromantic milestones in a founder’s story: money raised, a role formalized, responsibility attached to a name. The paperwork has its own narrative voice, though nobody has ever mistaken it for a page-turner.
By October 2017, Pave reported close to $23 million lent to nearly 1,700 people with limited credit histories. It was also proposing a Global Credit Profile, intended to let people build a fuller financial picture using information beyond conventional credit records. A token presale was announced to help fund the product. The proposal deserves its proper tense: it described what Pave intended to build.
Across those changes, Bass kept returning publicly to borrowers whose history could leave lenders with an incomplete picture. That continuity helps explain the sequence without making every revision look inevitable. The contractual machinery changed considerably. The question of which information deserved a place in a lending decision remained.
A founder gives the banks their due
Bass’s own education had followed a route through history and law. He graduated from the University of Leeds in 1999 and completed a law conversion course in 2001. His career included Clifford Chance, Goldman Sachs and GLG Partners before Pave. Later came Founders Intelligence, where his work included thinking about the institutions that fintech companies wanted to challenge.
In a June 2018 essay about British banking, he criticized cumbersome customer experiences and old technology while acknowledging the advantages of established banks. They had customers, funding and trust. His argument left room for reinvention within an incumbent institution. The customer’s experience, he suggested, should determine whether the changes actually amounted to progress.
That essay gives the career a useful hinge. The vocabulary of disruption can make an established bank sound like an inconvenient antique. Bass was considering what its assets might enable if its technology and organization changed. The position makes his later work with large financial institutions easier to understand, without requiring a conversion story.
On 1 May 2020, he became CEO of Amsterdam Trade Bank, subsequently known as FIBR. The mandate was a digital bank serving small and medium-sized businesses across Europe. Its 2020 report described revised strategic plans, an executive team with technology and SME experience, and partnerships intended to broaden lending across European markets.
That chapter ended painfully. Amsterdam Trade Bank was declared bankrupt on 22 April 2022. The bank said American and British sanctions had created operational difficulties as counterparties struggled to continue supporting it. The Dutch central bank activated the deposit guarantee scheme. The outcome belongs in the career alongside the plans: a banking transformation has dependencies that reach far beyond its product team.
Now the customer has a warehouse
Bass joined Pemberton in 2022. His work moved into working capital, the finance that helps companies manage the interval between spending money and receiving it. Pemberton and Santander CIB announced their partnership to launch Invensa in December 2024, focused on inventory solutions for large and mid-sized businesses.
The commercial problem was quite physical. Companies wanted reliable access to goods and raw materials while keeping flexibility over the money committed to them. The announcement described a move from just-in-time supply chains towards just-in-case arrangements. Extra reassurance can occupy considerable warehouse space. It can also occupy considerable capital.
By 2025, Bass was CEO of Invensa and a Pemberton partner. In announcing his promotion, he thanked Symon Drake-Brockman and Mark Hickey for advice that had helped bring him to the firm. The acknowledgment adds another relationship to a career that began its entrepreneurial chapter talking about the value of backing and counsel.
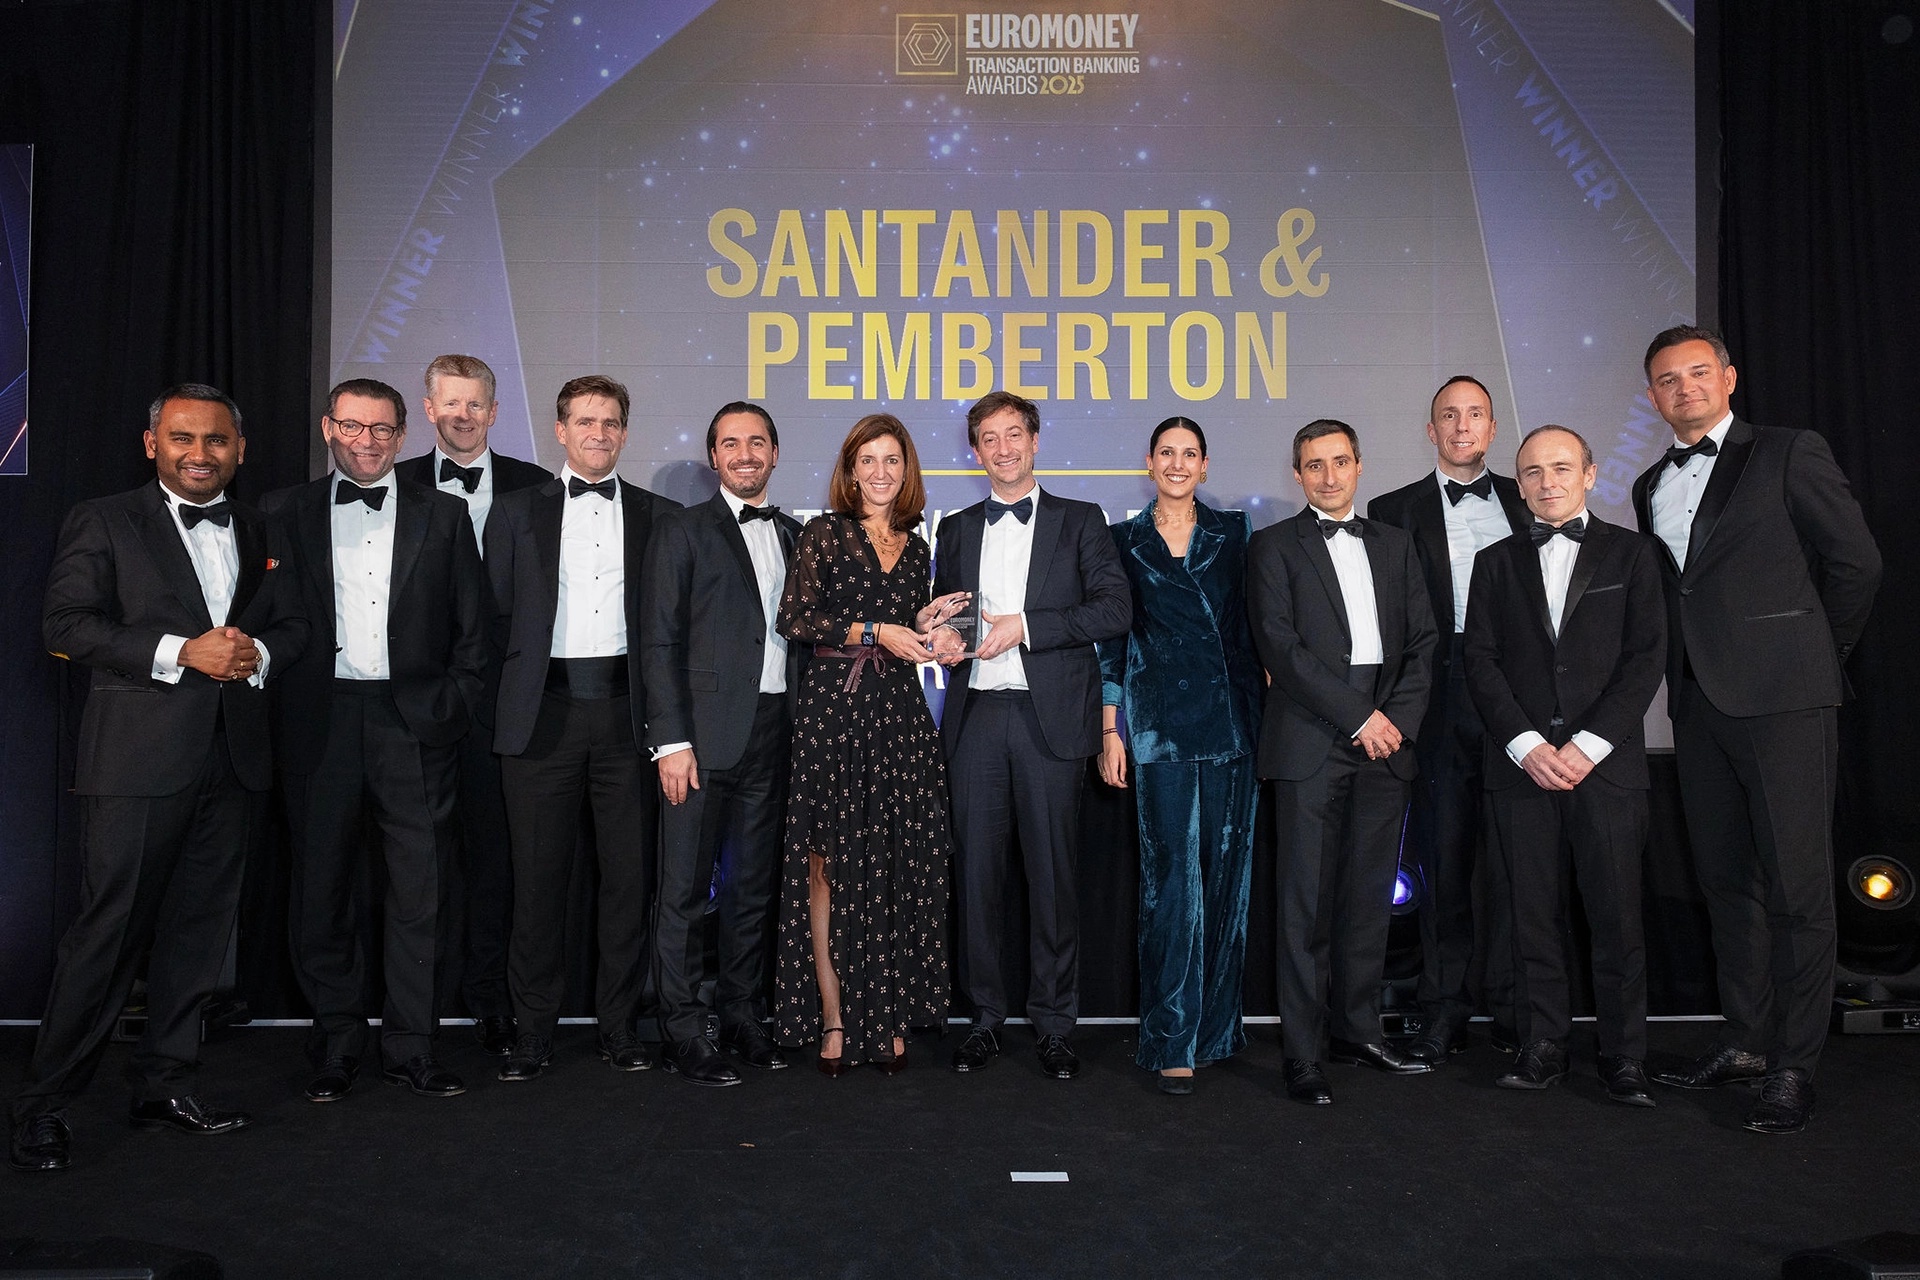
Invensa’s proposition involves owning inventory while allowing clients to maintain operational flexibility. Bass has emphasized the need to fit into existing supply chains. A corporate customer can admire an ingenious financing structure and still have a factory that needs its materials on Tuesday. Procurement, sales and treasury each have a stake in whether the arrangement works.
“The last thing corporates want is to disrupt a corporate’s supply chain.”
Oren Bass, 2025
The modesty of that operational requirement is revealing. After years spent in businesses associated with financial innovation, Bass was describing the value of letting a customer carry on. In the same 2025 discussion, he set out an ambition for Invensa to lead its market within five years. The ambition was large; his qualification concerned execution.
The short list, revisited
One earlier detail gives those business decisions a human scale. Bass’s interests included golf, and he admired Seve Ballesteros’s ingenuity. He also credited his first headmaster, Basil Flashman, with encouraging his work ethic, and named lawyer Malcolm Sweeting as a mentor. Alongside the institutional names are people he chose to remember.
His working rule in 2013 was to keep goals manageable. Read against the later career, it is a reminder of how small the next practical step can be even when the proposition is ambitious. Find a backer. Change an agreement. Make a product easier to use. Keep the goods moving. Tomorrow still needs financing; someone has to arrange what happens before it arrives.
Follow the conversation
Essays, interviews and the businesses along the way.
- Oren Bass at PembertonCurrent professional biography
- Invensa TradeInventory solutions
- LinkedIn · Twitter / X · FacebookPublicly listed social profiles
- Bass’s 2018 essay on the future of British bankingHis writing on Medium
- Listen: investing in students, with Oren Bass2014 interview with Zack Miller
- Watch: Oren Bass at the 2025 transaction banking awardsInterview video on LinkedIn
- Pave’s original pilot announcementDecember 2012
- Inside the Santander-Pemberton partnership2025 interview and award coverage
- Amsterdam Trade Bank’s 2022 closureDutch central bank announcement
- The Pave company storyA closer look at the lending experiment