An insurance policy is a frozen opinion about a person. It decides which facts matter, which risks belong together and how much uncertainty ought to cost. Most customers meet that opinion as a form, a price and a set of clauses. Omar Said López Tronco met it first as an actuary. He learned the mathematics, managed financial and technical risk, taught the subject and won prizes for researching it. Then he did the impolite thing that founders do to settled systems: he asked whether the opinion was paying attention.
Consider the driver who uses a car twice a week. Or the motorcycle that leaves its garage only on weekends. Conventional coverage can flatten both into familiar categories, because categories are tidy and reality is not. López Tronco’s company, Clupp, built its proposition around the messier evidence of movement - how far someone travels, how they handle the vehicle and what else might be exposed along the way.
That sounds obvious once stated. Many interesting businesses do. The difficulty lies in carrying the observation through regulation, pricing, fraud controls, customer service and the less glamorous Tuesday afternoon when an app must read an odometer photograph correctly.
A risk career looking for a product
López Tronco studied Actuarial Science at the Instituto Tecnológico Autónomo de México, then earned a master’s degree there in risk management. He became a CFA charterholder in 2013. Before startup life, he spent roughly a decade in the institutional world: financial planning and risk leadership at the transportation group IAMSA, followed by technical and financial risk at Seguros Monterrey New York Life. He also taught at ITAM and UNAM.
The biography matters because Clupp was not software tourists visiting insurance. Its founder knew what could go wrong, how a portfolio behaves and why caution becomes structural inside a financial institution. Y Combinator would later describe him as CEO, actuary, CFA charterholder and full-stack developer - a combination that makes a spreadsheet sound like it might deploy itself.
Begins a long run in planning and risk leadership at Grupo IAMSA.
Earns the CFA charter while teaching and working in risk.
Wins a national insurance research award for work on flexible life-insurance guarantees.
Builds Clupp and wins first place in Mexico’s Insurance Innovation Award.
Clupp enters Y Combinator’s Winter 2022 batch.
Insurance Boosters emerges from tools developed around Clupp’s operations.
His research habit did not vanish when the company appeared. In 2015, his work on valuing risk in flexible life insurance with rate guarantees received the Antonio Minzoni Consorti award. In 2017 came the innovation prize. Years later, he won the Asociación Mexicana de Actuarios’ fourth Premio Fundadores for a quantitative study of insurance-agent compensation, price elasticity, brand preference and discounts. His own explanation is admirably practical: research earns its value when it becomes useful.
I firmly believe that research gains its true value when it is translated into practical applications.Omar López Tronco
The smartphone was already a telematics device
Clupp began in 2016 as a mobile app designed to monitor driving style and reward good habits. The clever choice was not to demand another object for the dashboard. The ordinary smartphone already contained accelerometers, location signals and enough computing power to detect abrupt braking, acceleration, speeding, sharp turns and phone use while driving. A driver could choose to record trips and receive rewards or a better price.
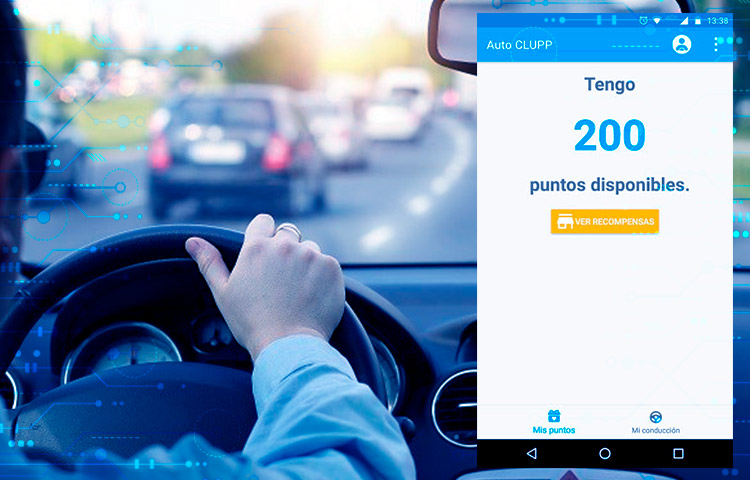
By 2020, the company had collected information from more than 10,000 app users and launched its own mobility insurance. Rather than behave only as a digital broker, Clupp operated through a Mexican mutuality, grouping members with similar risks and retaining parts of that risk. The structure gave the team room to vary a product around customers who drove less or demonstrated better habits.
The odometer became part of the interface. Customers on mileage-based plans periodically upload a photograph through the app. Clupp checks the reading, and if the plan and behavior drift apart for two consecutive months, the tier can move up or down. This is not the cinematic version of technology. Nobody has commissioned a film about administrative fairness. Yet the ability to pay for the mobility one actually uses is where the argument becomes concrete.
When you give them the option, they take it as added value, not as an invasion of their privacy.Omar López Tronco, on voluntary trip tracking
How Clupp changed the unit of insurance design
A motorcycle, a mobile phone and the limits of a category
An industry interview from 2022 contains a small, instructive detail. Clupp asked customers what risks they faced while moving. Many answered that their phone might be stolen. The answer did not fit neatly inside “auto insurance,” but it fit perfectly inside the customer’s trip. Clupp tested device-theft coverage. At the time of that interview, nearly 60 percent of its insured customers were reported to add it.
The same conversation revealed another correction to the obvious story: Clupp’s portfolio was mainly motorcycles, not cars. In Mexico, motorcycles were numerous, growing and rarely insured. For a company able to price and operate the risk, the overlooked category was not a footnote. It was the market announcing itself.
This is López Tronco’s recurring move. Begin with a formal system, then let observed behavior argue with it. The actuarial training provides respect for evidence. The developer supplies a way to capture it. The operator waits to discover whether the whole mechanism survives customers.
The customer experiences insurance as a reply
Insurance is peculiar because its product is partly a promise and partly a conversation about that promise. López Tronco has described WhatsApp as indispensable for continuous customer contact, especially after remote service accelerated. Social platforms can spread a brand; email preserves formal traceability; a CRM keeps the fragments coherent. But the customer asking whether a payment arrived or a change took effect mostly wants a clear answer without entering a telephone labyrinth composed by a sadist.
That operational concern leads to Insurance Boosters, a newer venture linked closely to Clupp. Software originally developed to handle Clupp’s internal needs was packaged for agents, brokers and distributors: omnichannel contact tools, AI-assisted calls and email, policy administration and quoting. The origin is pleasingly economical. Solve a daily problem. Make sure it works. Notice that other people have the same Tuesday afternoon.
Doing a demo with GPT is easy; the hard part is making it work every day with thousands of leads, without freezing or going off script.Omar López Tronco
His view of artificial intelligence is narrower, and therefore more useful, than the customary prophecy. He has publicly argued that deterministic processes should not be decorated with AI when rules and integrations already solve them predictably. Use the newer tools where ambiguity exists - reading unstructured documents, spotting missing information, explaining coverage or sustaining a conversation. Choosing the technology is part of the intelligence.
Nor does his version dispense with the insurance agent. López Tronco imagines automation taking repetitive calls, messages and follow-ups so the human can advise, establish trust and handle valuable decisions. In his phrasing, AI frees the agent to return to helping people protect what they value. It is a calmer future than the robot apocalypse and considerably easier to add to a product roadmap.
A founder who keeps translating
López Tronco’s professional life contains several worlds that usually exchange suspicious glances: academia, financial institutions, startup engineering, industry associations and customer support. He has served as president of Asociación Insurtech México, sits as secretary of CFA Society Mexico and has advised students in the CFA Institute Research Challenge. One ITAM team he helped advise won the 2019 Americas regional final and reached the global final in New York.
The connecting skill is translation. A risk model must become a decision. Sensor data must become an understandable benefit. A regulation must become an operating structure. An internal tool must become a product another broker can use without requiring its inventor to stand nearby. Translation lacks the glamour of invention, but it is how invention acquires customers.
Clupp’s public ambition has evolved with the evidence. Its current offering spans cars, motorcycles, bicycles, electric bikes, scooters and personal devices. Insurance Boosters carries the operating lessons outward toward distributors across Latin America. The original question still hums beneath both: what is actually happening in the customer’s life, and what would insurance look like if it noticed?
A policy will always be an opinion about risk. López Tronco’s contribution is to make that opinion less frozen - informed by the distance traveled, the behavior chosen, the object carried and the message waiting for an answer. The future of insurance, in this version, is neither dazzling nor cold. It is observant.