A potato-chip order is a modest place to begin a story about international finance. It does, however, have the advantage of being edible. In 2015, a small manufacturer landed shelf space at Whole Foods and needed money to deliver the goods. Drip Capital provided the capital. Neil Kothari and his co-founder, Pushkar Mukewar, were testing a proposition with very practical consequences: a business with an order in hand might deserve a better hearing from a lender.
That early example catches the problem neatly. Winning a customer creates expenses before it creates cash. Ingredients must be bought, production paid for, deliveries arranged. A promising order can make a bank balance look rather less promising. Kothari’s career as a founder grew around this awkward interval, where commercial success can arrive wearing the disguise of a funding shortage.
Drip would change its market and cross borders before finding its footing. The underlying question survived: how much could a lender learn by looking more carefully at the business actually taking place? For Kothari, a Stanford computer-science graduate with experience at Goldman Sachs and BlackRock, it was a question that joined two parts of his working life.
Two roommates, several possible companies
Kothari and Mukewar met at Wharton, where they were classmates and roommates. Both graduated in 2011. They shared an interest in entrepreneurship before they had settled on an enterprise. This is a useful detail in a business culture fond of giving every successful company an immaculate conception. Their partnership preceded the answer.
Kothari brought experience in fixed-income trading at Goldman Sachs and portfolio management at BlackRock. He also worked in corporate and business development at Cisco. Computer science, institutional finance and corporate development made a substantial collection of tools. Choosing what to build with them proved to be its own occupation.
By 2014-15, the two were discussing a venture together. Mukewar came to California and stayed with Kothari. They researched possibilities, consulted people and assembled spreadsheets. In Mukewar’s later account, they could abandon a direction upon discovering a competitor or hearing a discouraging assessment. About a year and a half passed in this manner. A spreadsheet is excellent company until one expects it to become a customer.
The eventual company began with US small businesses. The attraction was understandable: orders and the information around them offered something concrete to examine. An actual transaction could supply evidence that a general application form missed. The founders were looking for a way to make the evaluation of a smaller borrower worth doing.
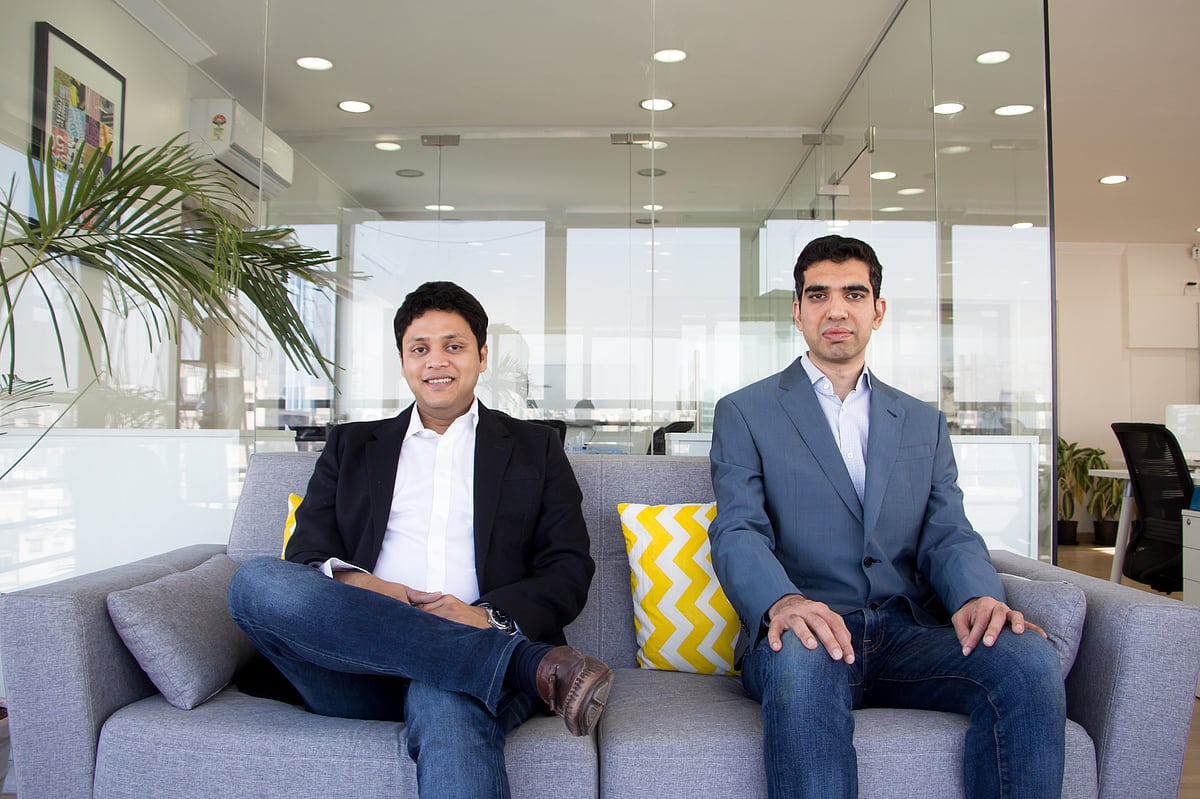
A bank’s smallest customer still has deadlines
Drip joined Y Combinator’s Summer 2015 batch. Its launch described an online lending service for American small businesses, evaluating orders they still needed to fulfil. Loans were expected to be repaid over one to four months. The Whole Foods supplier belonged to this early version of the business, before the emphasis moved to exporters in emerging markets.
Kothari drew attention to banks’ standardised products and the sharply different experience of obtaining money depending on the size of the applicant. Large clients could command attention. Smaller ones still had wages, suppliers and buyers with calendars of their own.
“Banks have an almost one-size-fits-all product.”
Neil Kothari, 2015
The US market also contained competitors with more capital. For a young lender, raising money and finding people to lend it to are separate problems, and each can obstruct the other. Drip’s early demand did not settle the question of where it could build a durable business. The founders had to look again at the route money was taking.
American buyers needed funds to pay overseas suppliers. Those suppliers had their own financing difficulties. Following the transaction backwards suggested a different customer: the exporter waiting for payment. The journey from a US purchase order to an Indian export invoice was a change in geography and commercial focus, with the same concern about time underneath.
The invoice travels; the cash takes its time
India operations took shape in 2016. Mukewar pursued exporters directly, including a business in Anand, Gujarat, called Dhara Foods. It supplied processed and packaged food to American grocery stores. Without collateral to offer, conventional finance was difficult to secure. Drip financed its export invoices, and Dhara Foods became an early proving ground for the exporter model.
The sales work in that episode was Mukewar’s. Kothari’s story sits alongside it as the other half of a company being built across California and India. The distinction matters: a founding partnership is made of particular contributions, and a good anecdote need not be reassigned to the person whose name appears above the article.
The appeal of invoice finance becomes clearer when one follows a shipment. Goods leave the exporter, but the buyer may pay weeks or months later. An advance against an eligible invoice can bring some of that money forward. It gives the seller cash to put back into operations while the buyer’s payment terms continue to run.
There is a temptation to call this simple and stop there. The explanation is simple; assessing whether a transaction merits financing is demanding. The buyer matters, the seller matters, and the documents must describe a trade that can withstand scrutiny. Software is useful precisely because small transactions can carry a great deal of administrative work.
A computer scientist looks at a shipment
Kothari’s description of Drip’s technology in 2019 was specific: electronic information fed proprietary algorithms that assessed the risk of individual shipments. The unit of attention was revealing. A lender could look beyond a business in the abstract to the particular transaction for which it wanted money.
For an exporter, the interface promised less paperwork and quicker handling. Behind it sat the less photogenic labour of bringing information together and deciding what to trust. Kothari’s earlier work with financial assets gave this part of the company a familiar vocabulary: risk, repayment and the quality of evidence. His computer-science background supplied another: systems that can repeat a process.
Drip also needed capital to fund those transactions. In 2018, Kothari explained that debt raised from Silicon Valley Bank and other US investors would help build its lending book. Equity could finance the business itself; lending capital was needed to finance customers. The distinction helps explain why a trade-finance company’s fundraising announcements can contain quite different kinds of money.
The work required persuading people on both sides. Exporters needed to understand an unfamiliar alternative to their bank. Capital providers needed confidence in a portfolio of receivables. A frictionless button on a screen was the visible result of a business with rather a lot happening out of sight.
What half a billion actually measured
By July 2019, Drip reported facilitating $500 million in trade and extending credit to more than 400 Indian exporters. It announced a $25 million Series B led by Accel, with existing and new investors participating. Kothari was then publicly identified as co-founder and co-CEO alongside Mukewar.
Trade facilitated by Drip Capital at that point. Transaction volume measures financed commerce; it is separate from revenue, valuation and a founder’s personal wealth.
Those distinctions are worth keeping even when a headline would be shorter without them. The money moving through a financing platform belongs to a different story from the money earned by the platform. For Kothari, the achievement was helping establish a service that businesses used repeatedly to support trade.
In October 2020, he discussed Drip’s path to $1 billion in transactions with early backer Garry Tan. The conversation gives the early pivots a useful place in the story: finding the market took experimentation. The result can look inevitable once attached to a large number. The route there was considerably less tidy.
More room in the warehouse
Another 2020 product illustrated how the founders were examining the buyer’s side as well. GoTrade addressed the money tied up in imported inventory. Kothari explained that an importer could release inventory in portions as orders came in, rather than buying everything back at once. The example used to describe it involved 40,000 pounds of shrimp. International finance occasionally has a surprisingly specific menu.
The product made the timing problem tangible. Paying a supplier, holding stock and collecting from customers happen at different moments. Financing that fits those moments can give an operator more room to work. Kothari’s explanation stayed close to that operational detail, where an abstract credit facility becomes a decision about what can leave a warehouse.
It also shows why the company’s ambition extended beyond a single loan format. Trade presents a sequence of related obstacles. Learning where money becomes stuck can reveal the next service a customer might need. Each additional product, however, still has to earn its place in the customer’s working day.
A founder’s title, and the next chapter
Kothari’s co-CEO title belongs to Drip’s earlier chapter. His current public LinkedIn headline reads “Working on Something New,” with Palo Alto as his location. Mukewar leads Drip as CEO. The company Kothari helped start has continued to develop beyond the operating partnership described in those early interviews.
In 2026, Drip reported more than $9 billion financed and over 11,000 businesses served. Those are company milestones, reached over a longer history than Kothari’s time as co-CEO. They show the subsequent scale of the enterprise without turning every later result into a personal accomplishment.
The lasting interest in Kothari’s founding chapter is more concrete than a title. Two roommates wanted to start something. Their first market required reconsideration. An overlooked stretch of the trading cycle supplied a better direction. The work became useful when it addressed the interval between doing business and being paid for it.
There is a certain elegance in that modest ambition. A manufacturer who has won an order should be able to think about making the next batch. An exporter should have a chance to pursue the next buyer. Kothari helped build a company around giving those plans a little more money and a little less waiting.