Over their first coffee, Moti Cohen told Tamir Kessel he intended to replace NetSuite and SAP. Kessel’s first reaction was disbelief. He later became Cohen’s coach and strategic thought partner, which is one way of ensuring an ambitious founder gets regular appointments with someone prepared to question him. The proposal was large enough to sound implausible before anyone had finished discussing it. Cohen wanted to rebuild the machinery that finance departments use to do their jobs.
The interesting part is what had made him so dissatisfied. Cohen had worked in audit and served as a CFO. Finance itself held his interest. The recurring chores bothered him: calculations performed again, reconciliations repeated, reports reconstructed because the calendar had advanced another month. A profession concerned with judgment was spending an inconvenient amount of its time reproducing yesterday’s homework.
His eventual rule was brief enough to fit on a sticky note. It would become a product principle at Viewz, the company he co-founded with Omer Aviad and Liran Kessel. There is a whole career’s irritation packed into those four words.
Cohen’s operating rule“I don’t do twice.”
The second time around
Cohen describes his early professional life as junior audit work at EY, followed by CFO roles in complex organizations. He could find finance fascinating and still resent its habits. The objection was specific: repeating an analysis, calculation or report that a system could be made to produce. Once the same task returned, he believed automation should take over.
That gives his founder story a recognizable starting point. People who work inside a process learn its exceptions, deadlines and reasons for caution. They also learn which inconveniences have acquired the status of natural law. Cohen’s account suggests he had begun to question the assumption that recurring financial work had to demand recurring human effort.
The rule has an almost comic severity. Twice is a very low threshold for declaring a task intolerable. Yet it also supplies a practical test: when work returns, ask whether the person doing it needs to exercise fresh judgment or merely repeat the mechanics. A calculation can deserve careful design without deserving a fresh performance every month.
Viewz turns that impatience into an organizing idea. Its ambition is to keep financial information current and recurring work moving, so people can spend more time understanding the business. Cohen’s professional background makes the choice of problem legible. He had occupied the jobs whose routines he now wanted to change.
A coffee with a very large proposal
Kessel’s recollection places the scale of Cohen’s ambition near the beginning. Replacing established enterprise systems is a substantial proposition for a startup. Those systems hold records, support workflows and sit inside organizations that have learned to depend on them. Persuading a customer to move involves more than showing a pleasing screen.
By the time Kessel publicly recalled that coffee, he was describing a year spent as Cohen’s coach and strategic thought partner. His initial skepticism had changed. That does not settle the competitive question. It gives the story a useful human relationship: a founder with a broad plan, and someone close enough to challenge the plan as it becomes a business.
Cohen has described similar skepticism in early investor conversations. The scope of the proposed replacement kept drawing attention. In his account, Viewz was taking on the intake of financial information, its recording and the preparation of reports within one system. Professionals would remain involved in approving automated work.
His account of 2025 identifies March as the launch of the All in Viewz offering. He said the company entered 2026 managing more than $500 million in activity and supporting payroll calculations for over 2,500 employees. Those are his reported measures of operating scope. They describe customers’ activity, rather than Viewz’s own revenue, a distinction an accountant would appreciate.
The ledger beneath the promise
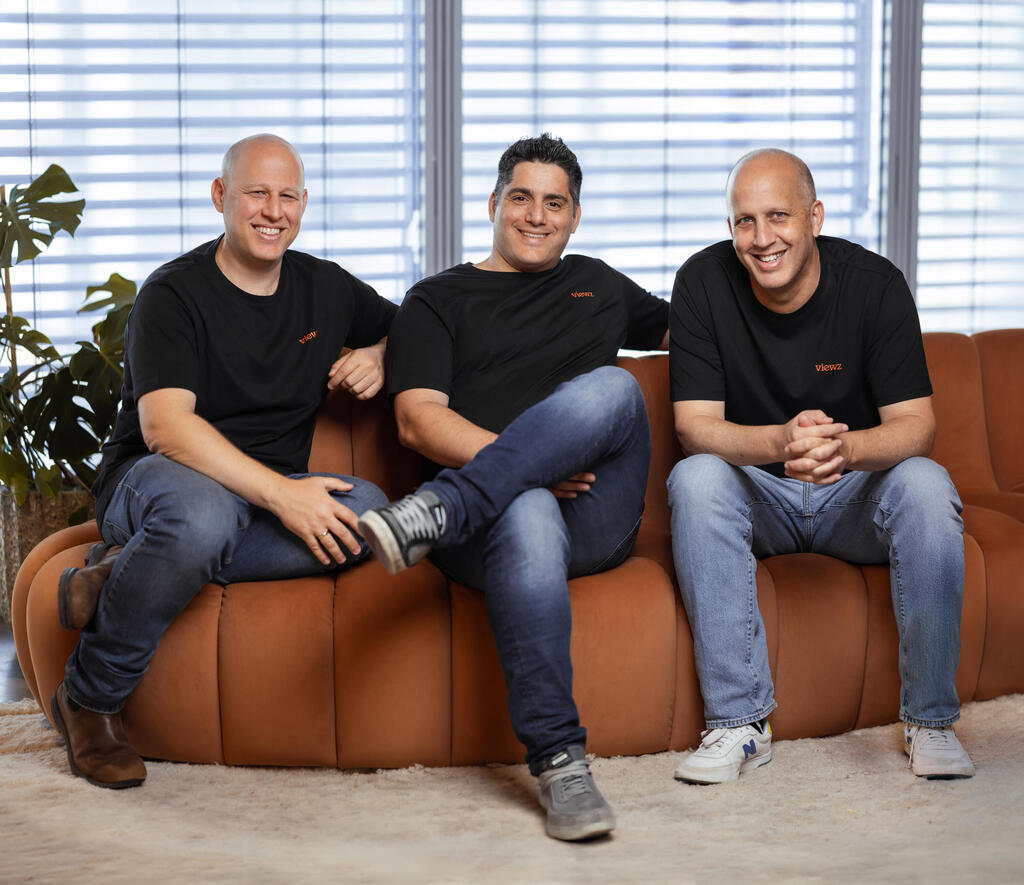
The founding division of labor is straightforward: Cohen is CEO, Aviad is CMO and Kessel is CTO. Viewz presents their combined experience across audit, transactions, finance leadership and operations as the basis for its approach. The group’s shared diagnosis is that financial information exists in abundance, but connecting it into dependable working numbers requires too much intervention.
A ledger is the central record of a business’s accounts. Viewz puts that record at the center of its design, alongside AI agents and a layer of finance expertise. The intended operating model covers bookkeeping, financial planning and analysis, payroll, compliance and reporting. The breadth explains both the attraction of Cohen’s proposal and the early raised eyebrows.
That choice also makes the product a commitment about responsibility. When several finance tasks share a system, the customer has to understand how the work moves between them. Cohen’s experience gives him a reason to care about those handoffs: the person signing off still needs an intelligible account of what happened.
The public funding announcement arrived in May 2026: a $7 million seed round led by Ibex Investors and Flint Capital. Viewz reported multi-million-dollar annual recurring revenue and zero voluntary churn after a quiet launch about a year earlier. These were company-reported results at the announcement, rather than a promise about what would happen next.
For Cohen, the money gave a public milestone to work that had already been under way. His argument was that finance teams spent too long preparing information before they could analyze it. A continuously updated ledger was meant to shorten that distance. The funding could support the building; customers would still judge the daily operation.
Led by Ibex Investors
and Flint Capital
A number someone can stand behind
One of Cohen’s more revealing accounts concerns a potential customer who had connected Claude to bank and email data and produced a cash-flow dashboard. The customer wanted to extend that approach into bookkeeping. Cohen described a conversation about the difference between assembling a useful view of information and building an accounting operation people could rely on.
In his telling, the discussion came back to trust in the numbers reported to investors and tax authorities. He argued that human responsibility remained necessary. That is a consequential position for someone selling automation: the proposed result includes people who can stand behind the work, even as software performs more of it.
The question gives the article’s opening ambition its proper weight. An established finance system has inertia partly because switching creates a new burden of confidence. Someone must decide that the replacement records the right things, catches the right exceptions and produces results worth using. A quick demonstration cannot answer every one of those questions.
Cohen’s public language at the funding announcement returned to a simpler expression of frustration: “why does this still feel so hard?” It is a fair question to ask of an ordinary report. It is also a demanding brief for the team trying to build the answer. Every removed handoff has to leave the financial result dependable.
- 01ConnectFinancial inputs
- 02StructureA unified ledger
- 03AutomateRecurring accounting
- 04ReviewHuman accountability
The person doing everything
His writing offers another route into the problem. In April 2026, Cohen published an article about running a finance department of one. Its concerns are practical: defining the job, documenting recurring processes, protecting time for forward-looking work and recognizing when specialist support is needed. The reader is someone carrying several responsibilities under one title.
That advice sits comfortably beside his product ambition. A smaller finance function still needs clear ownership. A process needs to be written down well enough that it can be followed and checked. A person responsible for the whole function needs to know the boundaries of their expertise. Automation does not make those organizational questions disappear.
He had already written about AI agents in October 2025, discussing applications including invoice processing, consolidated reporting and forecasting. His interest extended to asking questions of financial data and using agents to explore possible business scenarios. The common thread is giving people access to useful information while reducing the work needed to prepare it.
He was also listed to speak at a March 2025 finance meetup at EY Israel in Tel Aviv. His allotted topic concerned whether financial data was ready for AI. It is a compact expression of a concern that keeps surfacing in his work. Before admiring the answer a system produces, examine what the system has been given.
A different appointment with the books
By August 2026, Cohen was developing the argument further. In an essay published that month, he described the hidden operational expense of fragmented finance systems: the people and effort needed to keep them connected. Hiring can address the immediate workload while leaving the underlying arrangement intact. His proposed measure of progress was a simpler connection between data, execution and decisions.
That argument brings the story back to his original irritation. Repeated work can look like an individual’s responsibility when it is also a consequence of how the operation has been assembled. Cohen’s bet is that a different arrangement will let a finance team accomplish more without continually adding people to bridge its gaps.
There is something appealingly accountant-like about the ambition. However broad the proposal becomes, it eventually has to resolve into work performed correctly and numbers that hold together. Cohen can raise money, explain the ledger and persuade a skeptical coach. The recurring examination comes when a customer opens the books again.
His rule makes the desired experience easy to understand. The same business process returns. This time, the system has done more of the preparation. The finance professional can begin closer to the decision. For someone who disliked repeating the homework, that would be a satisfying use of the next month.