Consider the car that spends Monday through Friday outside an apartment. Its owner takes the train to work. On Saturday, it carries groceries. On Sunday, perhaps, it goes nowhere. An insurance company still needs to cover it. But should its bill resemble the bill for a car crossing the city twice a day? Metromile turned that ordinary question into a company.
- The proposition: a base rate plus a charge for actual miles.
- The complication: measuring usage did not remove the costs of running an insurer.
- The afterlife: Lemonade took the insurance business; EIS took the enterprise software.
The customer was the person who barely drove
Founded in 2011 by David Friedberg and Steve Pretre, Metromile aimed at people conventional car insurance could make feel invisible: the occasional driver, the transit commuter, the owner of a second car. The company commonly defined low mileage as 10,000 miles or fewer a year. Its argument was easy to grasp. Less time driving should show up in the price.
The product combined familiar coverage with unfamiliar billing. Customers could choose coverage limits and deductibles, then pay a recurring base charge and a rate for each mile. A device called Pulse plugged into the car’s diagnostic port. The insurance bill acquired a measuring instrument.
The meter had a minimum
In July 2021, Metromile advertised base rates starting at $29 a month, plus a few cents per mile. That was a starting point, not a universal price. A driver’s actual quote depended on the policy and underwriting. Even a car that never moved incurred the base charge. A parked car can still be stolen.
There was also a thoughtful exception. Metromile stopped charging for additional miles after 250 in one day, or 150 in New Jersey. The occasional road trip would not keep the meter running indefinitely. That small rule addressed an obvious worry: what if a low-mileage driver wanted one very long weekend?
The arithmetic also reveals the boundary. At those invented rates, 1,500 miles costs $130. Against an otherwise equivalent $100 fixed monthly policy, the break-even point is 1,000 miles. Beyond it, the fixed bill wins. Coverage, deductibles and fees must match for the comparison to mean anything. The product rewarded a pattern of use; it could not promise every driver a bargain.
The plug learned a second job
Pulse did more than count. The accompanying app offered trip information, car location and vehicle diagnostics. Insurance, usually something people remember at renewal or after a collision, could become useful between those events. Finding a parked car is a modest benefit. It is also more tangible than another reassuring slogan.
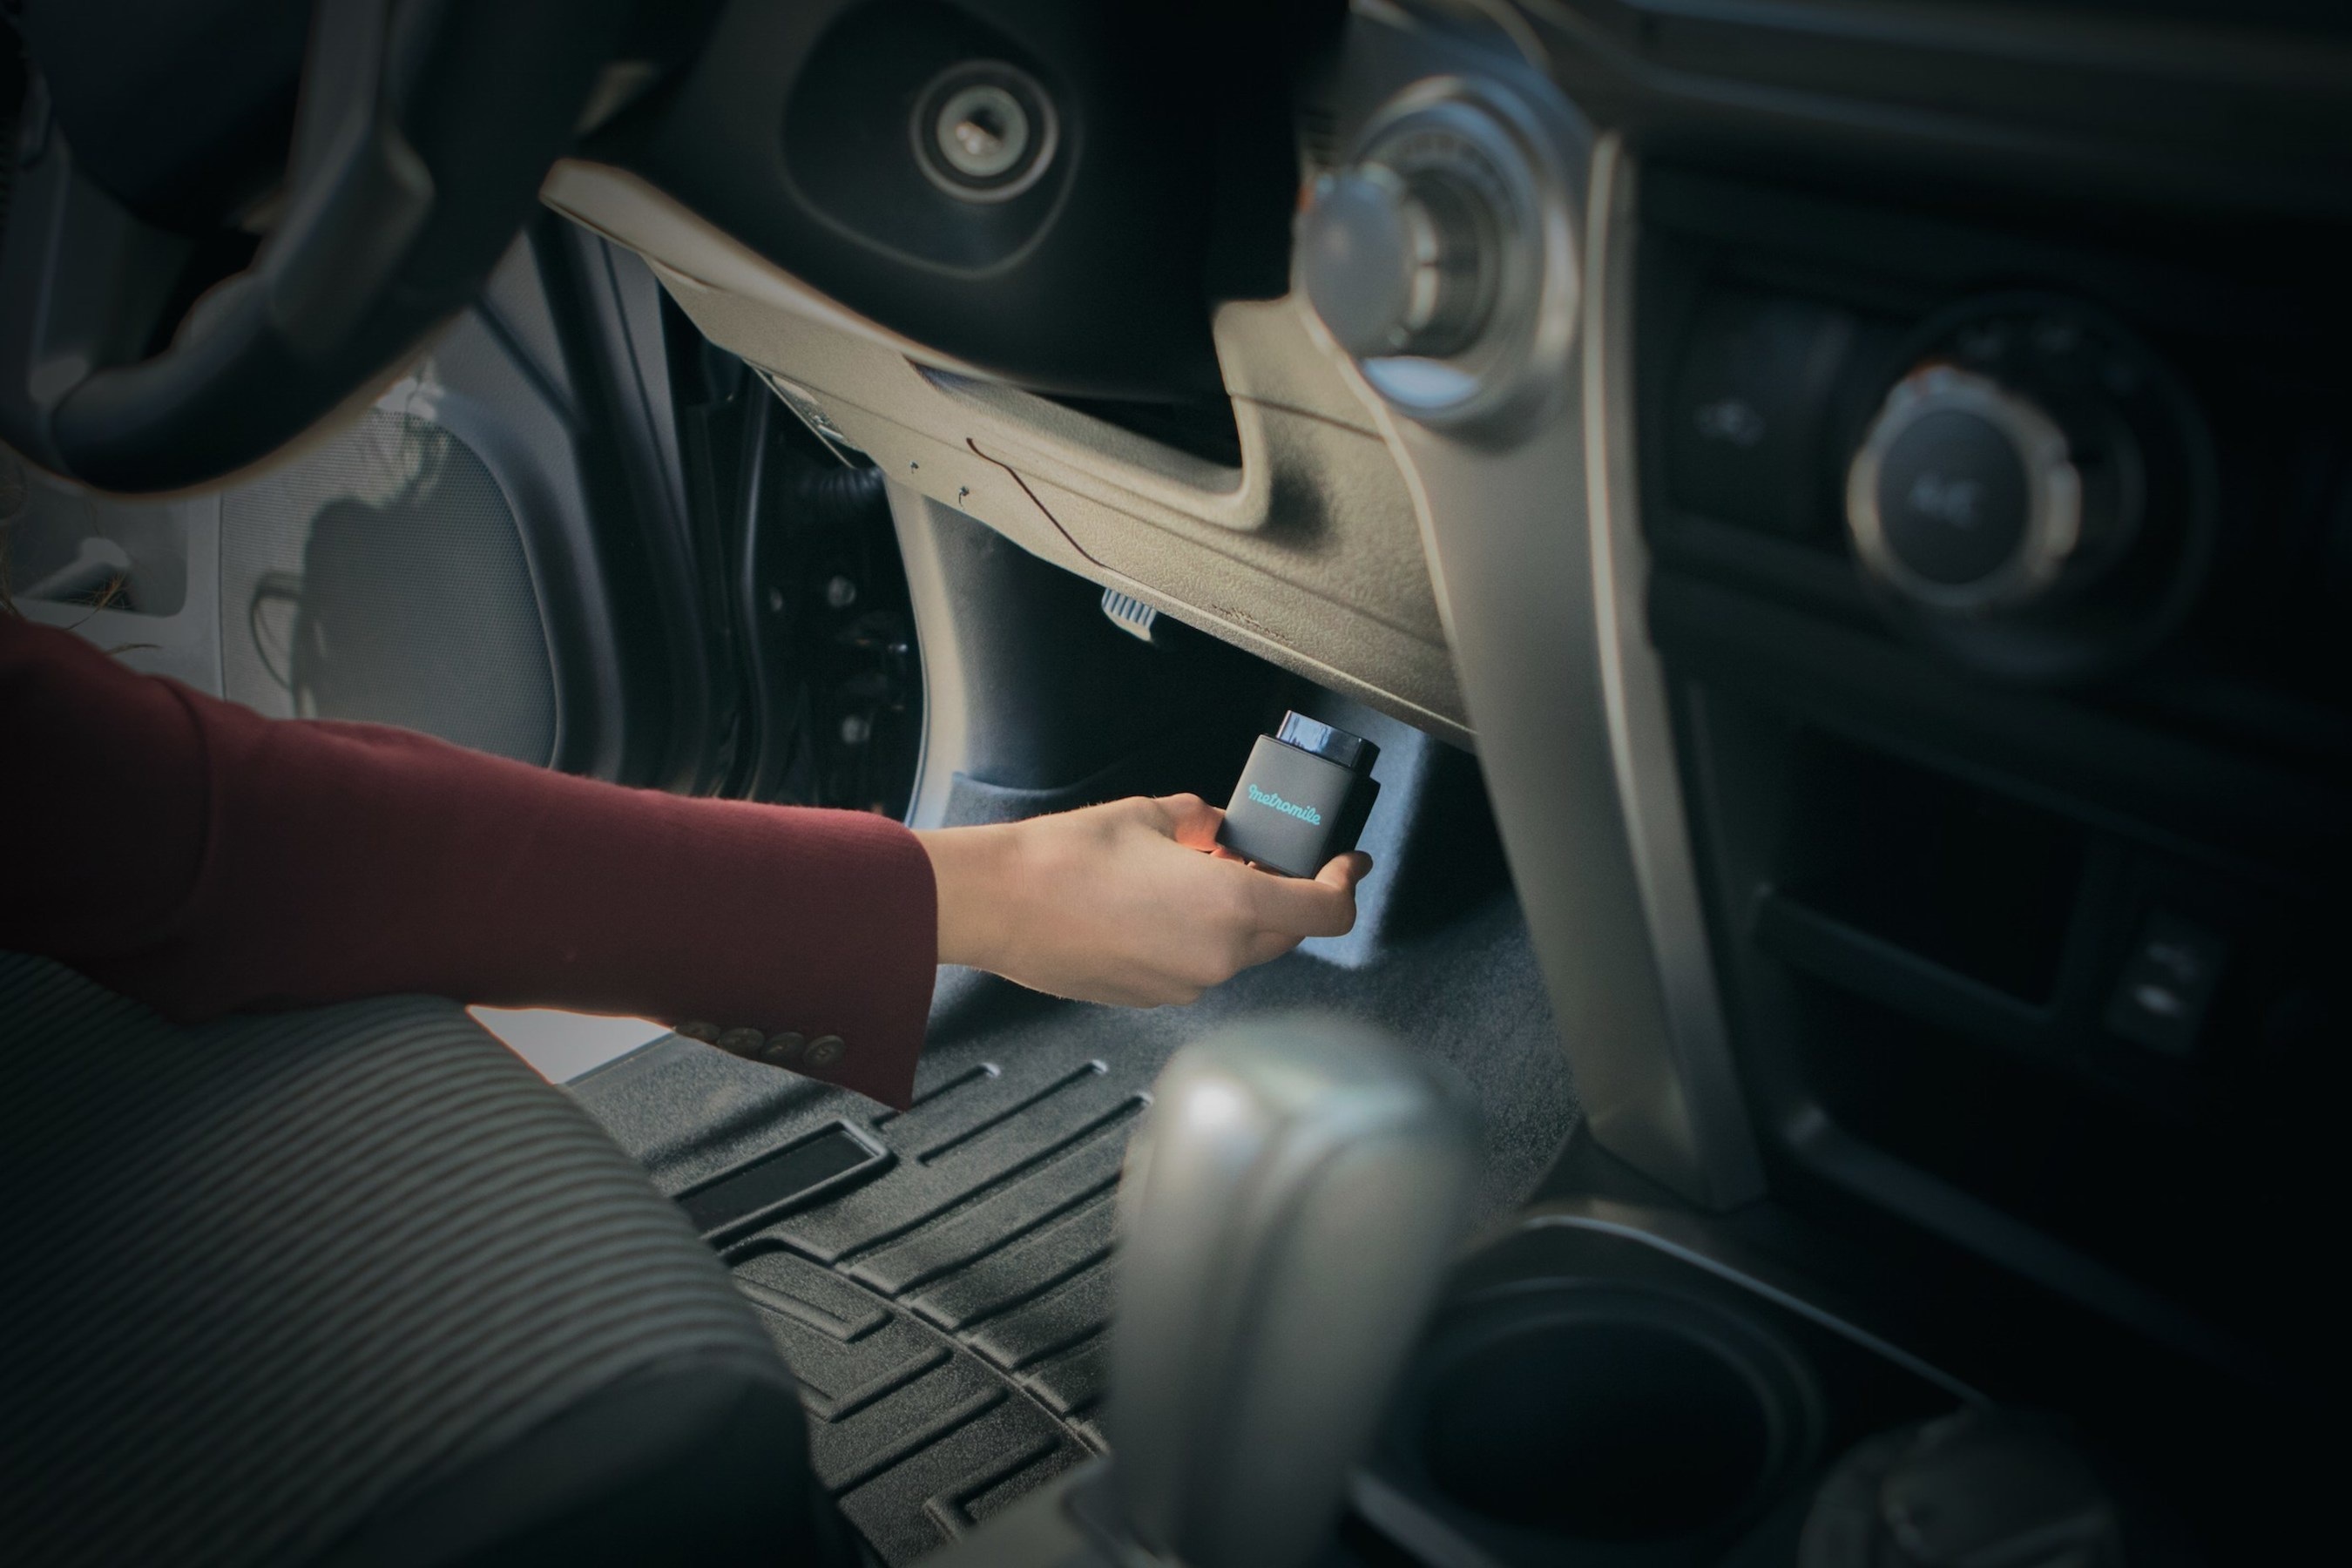
There was a privacy bargain inside that convenience. Pulse’s published terms described collecting location, speed, acceleration and collision information, among other data. Customers could turn off long-term GPS storage, with exceptions including fraud prevention. Measuring insurance exposure required letting the insurer see more of the car’s life.
That visibility fed AVA, Metromile’s claims technology. In a 2017 interview, chief executive Dan Preston called it “the unified AI platform that drives the decisions.” He described shared capabilities spanning pricing, underwriting and claims. Certain claims could move through automated checks; that did not mean every collision received an instant payout.
The engineering could be wonderfully literal. In 2018, Metromile described staging crashes at roughly five miles per hour, collecting sensor readings to study low-impact accidents and fraud. Training a system to understand a fender bender involved bending some fenders. In 2019, the company gave that work another customer: other insurers, through Metromile Enterprise.
The bill was easier to redesign than the business
Metromile kept seeking ways to reduce friction. Its 2020 Ford agreement aimed to let eligible connected vehicles transmit odometer readings with the owner’s consent, avoiding extra hardware. Investors saw promise too: Tokio Marine and Intact co-led a $90 million Series E in 2018. The company entered public markets through a SPAC combination in February 2021.
The growth timetable was ambitious. Early in 2021, Metromile projected 125,000 to 133,000 policies by year-end. Its eventual full-year release reported an increase of only a little over 5,000 policies. A comparison of those disclosures suggests that scaling the customer base was proving harder than the expansion story implied.
A better way to measure the customer still needs an affordable way to find the customer.
The pressures were concrete. In November 2021, management cited rising customer acquisition costs and additional capital requirements when explaining the advantages of joining Lemonade. Metromile’s annual accounts later recorded $104.9 million in 2021 revenue and a $216.5 million net loss. Those are company-wide accounting figures, not a verdict on the economics of every individual policy.
This is where the original promise met a larger system. Insurance requires reserves, claims handling, regulatory approvals and enough premium to absorb losses. A cleaner bill helps the customer understand the product. It does not, by itself, finance the institution behind it.
The company split. The question stayed.
Lemonade announced the acquisition in November 2021 at an implied equity value of about $500 million. At closing in July 2022, it described stock consideration worth under $145 million and an acquired business holding over $155 million in cash. These were different dated measures, not interchangeable price tags.
Lemonade also emphasized data from more than 500 million car trips. The buyer gained experience that a newcomer could not simply manufacture on launch day. EIS then acquired the enterprise software operation. By December 2024, Lemonade said migration of Metromile customers to its platform was substantially complete. Today, Metromile’s website sends quote requests to Lemonade.
The useful thing to copy is the starting question: find customers whose actual use differs from the category’s assumptions, then make that difference legible in the price. Check the cost of serving them just as carefully. For drivers, the corresponding lesson is practical: count your miles, compare equivalent coverage, and read the data terms. The parked car deserves a calculation.