Lagos, Nigeria · The machinery beneath the market
A supplier payment is a small sentence with a long backstage. Money leaves one account, changes currency, crosses jurisdictions, satisfies compliance checks, finds a local rail, and arrives before somebody loses patience or margin. If it works, no one applauds. A shipment simply moves. Maxwell Obi has built a career in that quiet interval between “pay” and “paid.”
His route into finance began at the keyboard. Obi studied computer science at Nnamdi Azikiwe University, where his public record includes a spell as director of software for the university's computer-science student association. Early projects were practical and institutional: school-management software, examination systems, payment gateways. The sort of code that has to survive contact with administrators, records, and real money tends to cure a person of decorative thinking.
By 2012 he was working as a software engineer at Unified Payment Services. A product role at Platform Technologies followed. Then, in 2015, a waiting room supplied the plot twist. During recruitment for the Meltwater Entrepreneurial School of Technology, Obi began talking with another applicant, Segun Adeyemi. The subject was payments. Neither knew that the conversation would become a company.
The first difficult transfer
At MEST in Accra, Obi and Adeyemi developed Amplify, a Nigerian fintech built around recurring payments. Its central problem was ordinary enough to sound absurd: subscription businesses struggled to collect automatic payments cleanly. Integrations were expensive, user experiences were rough, and legacy processes still wandered into bank branches carrying paperwork.
Amplify built a recurring-payment gateway, AmplifyPay, and a keyboard-banking product called mTransfers. The latter put financial actions inside chat conversations. Its bank partnerships included Zenith Bank's Qwerty Banking and Fidelity Bank's Flashkey. Before the company was acquired, its tools had supported more than 1,000 merchants and transactions for four large Nigerian banks.
OneFi, the company behind the lending service now known as Carbon, was Amplify's first major client. It tried twice to invest. In 2019, it bought the company outright. Obi described the negotiations with a metaphor that made corporate finance sound unexpectedly domestic: an acquisition was like “courting before marriage,” deliberate, anxious, full of back and forth.
“It was less about the amount involved, and more about the strategic thinking and new vision for the company.”Maxwell Obi on Amplify's undisclosed acquisition price
He stayed with the buyer to oversee payments. Asked why he did not take the post-exit break his co-founder chose, Obi gave an answer with no management-consulting perfume on it: “I wanted the action.” It is a useful line because his career after Amplify was not a retreat into advising from a handsome chair. He moved closer to the institutional machinery.
A request with nowhere to go
At Sendwave, Obi led West African partnerships and later global business development. The company moved remittances between people; his work brought him into negotiations with banks, fintechs, partners, and regulators across Africa, Asia, and Latin America. The view from there was wider than a product dashboard. It showed which corridors worked, where liquidity thinned, and how much human coordination hid inside an “instant” transfer.
One request kept recurring. Businesses wanted help paying overseas suppliers and vendors. Sendwave was built for person-to-person remittances, so the need sat awkwardly outside its frame. Obi did not confuse a product boundary with a market boundary. He went looking.
and currency
and settlement
and shipment
He spoke with importers, exporters, large companies, and enterprises. The conversations turned a recurring request into a detailed picture. A delayed transfer was not merely a bad financial experience. Exchange rates could change while a business waited. A supplier could withhold goods. Inventory could arrive late. The payment fee was only the visible part of the cost.
“It was a bigger problem than I imagined, and I decided to do something about it.”Maxwell Obi on the research that led to Waza
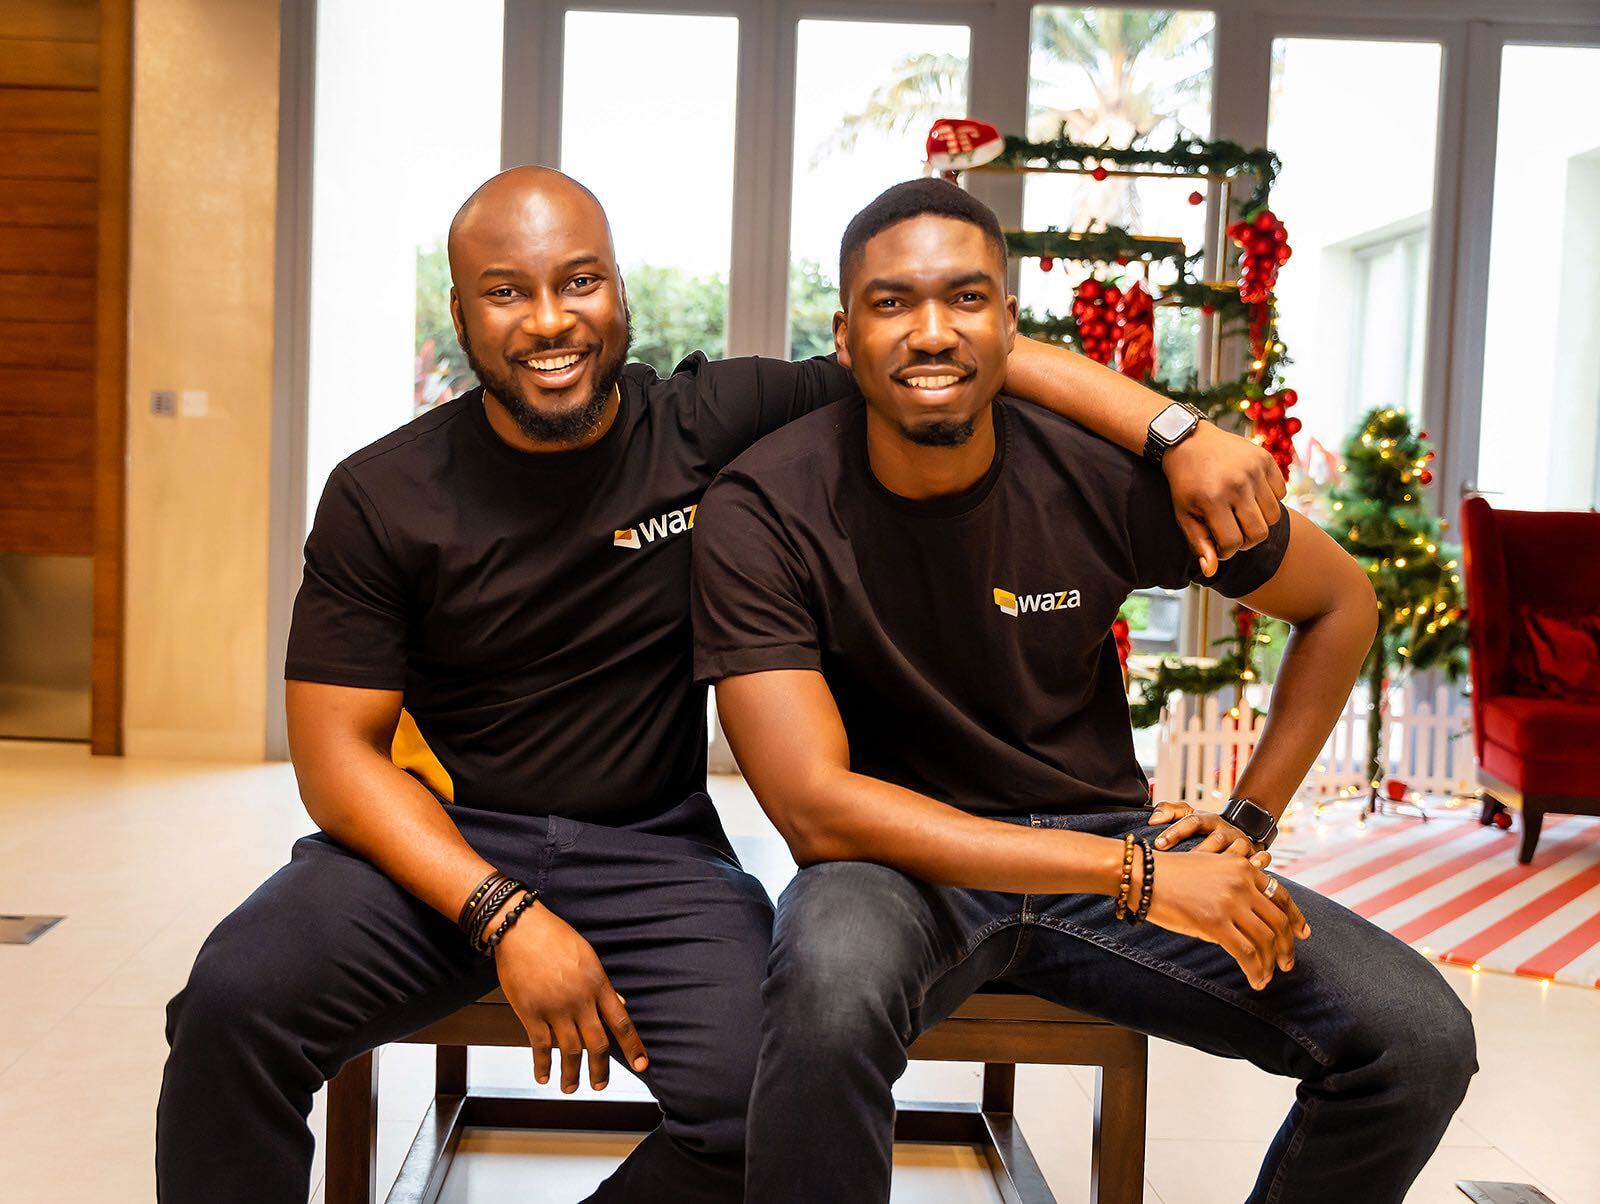
Obi founded Waza with Emmanuel Igbodudu, an engineer whose path included Revolut, Carbon, Moniepoint, and FairMoney. The pairing had a practical symmetry: Obi had moved from engineering into the commercial and regulatory edges of payments; Igbodudu had built financial products from deep inside engineering teams.
Do one thing well
Waza began operating in January 2023 and joined Y Combinator's Winter 2023 batch. Its first-month payment volume was $280,000. By May 2024, the company said it processed $70 million in a month, equal to more than $700 million on an annualized basis. It served hundreds of businesses across six continents, with active operations in Nigeria and Ghana.
Reported monthly payment volume
The customers fell into three broad groups. Multinationals operating in African markets needed liquidity. Importers and traders needed to pay suppliers in places such as China, India, and the United Kingdom. Fintech developers needed infrastructure on which to build their own cross-border products. Waza made money through foreign-exchange spreads and transaction fees.
In August 2024, Waza announced $3 million in seed equity from a group including Y Combinator, Byld Ventures, Norrsken Africa, Heirloom VC, Plug and Play, and Olive Tree Capital. Timon Capital supplied another $5 million in venture debt, assigned to a trade-finance pilot for larger clients. Equity would help widen the network; debt could begin financing the trade moving across it.
Obi's public description of the strategy is notably sequential. First, move money from point A to point B as quickly and affordably as possible. Then add adjacent services. “We want to do one thing and do it well before evolving into other verticals,” he said. This is restraint in its natural habitat: not a smaller ambition, but an order of operations.
A request that does not fit your current product may still fit your accumulated experience. Obi heard “supplier payments” at a remittance company, researched the gap, and built the next company around it.
From a rail to a station
The next layer arrived in January 2025. Waza launched Lync, a multi-currency platform for businesses incorporated in the United States, United Kingdom, or European Union while serving emerging markets. It offered accounts in dollars, euros, pounds, and naira, plus international routes including ACH, Fedwire, SWIFT, and the United Kingdom's Faster Payments. The purpose was less exotic than the acronym parade: let a company receive, hold, convert, reconcile, and send money from one place.
The launch also returned Obi to a motif from Amplify. Financial infrastructure should not make the user reenact the infrastructure. At Amplify, that meant dragging recurring payments away from paper-heavy processes. At Lync, it meant giving businesses accounts in their own names rather than hiding transactions inside a provider's pooled wallet.
In June 2025, the Central Bank of Nigeria granted Waza an International Money Transfer Operator licence. That allowed the company to facilitate inward remittances into Nigeria and connect another regulated rail to its platform. Obi called the licence a validation of the infrastructure his team had been building. The less ceremonial meaning was more capacity: another route by which businesses could receive money from abroad.
That same year he joined a future-finance panel in Nairobi and Waza collaborated with Lagos Business School on a report about business payments in Africa. By March 2026, Obi was making a broader argument in public writing: Africa's immediate technology opportunity is not simply more artificial intelligence, but coordination and integrated systems. The claim fits the career. Intelligence can optimize a system. First, the system has to connect.
The dignity of plumbing
Fintech prefers the language of disruption because plumbing has poor lighting. Yet Waza's work is plumbing in the honourable sense. Pipes create possibility by becoming boring. A reliable rail lets the trader think about goods, the airline think about routes, and the finance team think about cash rather than where a transfer vanished.
Obi's story is also a study in changing professional distance. The engineer began with the transaction. The first-time founder learned the merchant. The acquired operator learned consolidation. The partnerships executive learned corridors and regulation. The second-time founder could finally see the whole awkward procession from local currency to global supplier.
He has not abandoned the personal amid all that infrastructure. His compact public bio mentions fintech, remittances, and cars, then adds that he cooks, drives, and loves. It is an unusually warm footnote for someone whose working vocabulary includes liquidity pools and settlement speeds. Useful systems, like good dinners, are noticed most keenly when they arrive late.
The wager behind Waza is that businesses in emerging markets should not pay a permanent penalty for where they began. They should have accounts, foreign exchange, credit, and payment routes adequate to their ambitions. The work advances one transfer at a time, largely invisible, until a supplier ships and a company gets on with its day. That is the funny thing about successful financial plumbing. The grand achievement is ordinary motion.