A price looks wonderfully simple when it reaches a screen. One number, perhaps two decimal places, and an invitation to do something regrettable before lunch. Maxim Shen’s working life runs through the machinery behind that number. He has made markets, worked on trading software, joined a decentralized-finance business, and founded a trading firm of his own. Each step takes him closer to the practical question underneath the display: what has to work for a market to work?
Shen is the founder and CEO of Anti Capital. The company operates across New York and Taipei, combining proprietary trading with venture activity. Its name supplies a small joke before the business gets serious. Capital is very much involved. The objection, in the firm’s stated philosophy, is to the institutional weight around it: bureaucracy, cumbersome systems, and the assumption that a larger organization necessarily has a better answer.
That is a proposition about how to build a firm. Shen’s earlier career gives it a particular context. Before he was responsible for an organization, he worked in the places where trading ideas have to become executable instructions. A view of the market may sound persuasive over dinner. An order has to survive contact with the system.
A trader’s education in machinery
His public work history includes a market-making role at Traditum Group and an options market-making software engineering role at OptionsCity, later known as Vela. Those entries put software alongside trading early in the career. The distinction matters. Choosing a trade and building the mechanism that carries it out involve different work, even when the two eventually meet on the same desk.
The more firmly documented later stops are Blue Fire Capital and Tower Research Capital. At Blue Fire, Shen worked as a quantitative trader. At Tower, he worked as a quantitative market maker. Blue Fire subsequently became part of Galaxy Digital, which explains why the Galaxy name also appears in accounts of his background. A career history can acquire a new corporate surname without the person moving desks.
In 2021, Shen joined Injective’s financial-markets team. Contemporary accounts described the appointment as leading its trading desk or heading financial markets. The titles place him at the working intersection of trading expertise and a business developing decentralized financial infrastructure. His experience with high-frequency derivatives market making belonged to the appointment, rather than merely decorating the biography.
There is a useful continuity here. Markets may differ in how they organize access and execute transactions, but a trader still needs usable information and a workable route to an order. Shen’s move into Injective put an established trading craft into another setting. Founding Anti Capital then enlarged the responsibility again: the surrounding institution became part of the job.
The price has somewhere else to go
In November 2024, Anti Capital joined Pyth’s market-data provider network. The announcement widened the picture of Shen’s business. A trading firm can use a price to make its own decisions. It can also contribute information that other applications need. The same market expertise becomes relevant at another point in the chain.
The partnership announcement described coverage across crypto, equities, and commodities, with market data delivered in less than a second. That describes the partnership’s intended service, rather than a scorecard for the firm’s trading results. Shen spoke about bringing dependable information into decentralized finance and connecting it with traditional markets. The ambition was expressed in the vocabulary of a usable system.
“bring reliable, real-time data to the DeFi space”
Maxim Shen, on Anti Capital joining Pyth
The distinction between trading and distributing data is easy to lose when both appear under the heading of finance. They have different audiences. A trader needs information for a decision. A data-dependent application needs information it can receive and use. The partnership gives Shen’s story a concrete example of work that reaches beyond the internal trading desk.
It also suggests a less theatrical way to look at digital finance. Before the grand argument about its future comes the smaller question of whether the information arrives. Infrastructure has a peculiar social life: people notice it most when it interrupts them. When it works, the number simply appears, looking as if it had never needed anyone’s help.
A spreadsheet enters the plot
There is another revealing detail in Anti Capital’s operating history. The firm adopted SoftLedger for crypto accounting after working with multiple software solutions and trying to reduce its dependence on spreadsheets. An automated API workflow helped with reconciliation and reporting, including income statements and balance sheets. Permissions across multiple entities were also part of the setup.
Shen endorsed accounting that could give a clear picture of a digital-asset business. It is an unusually practical detail to find in a founder story, and a useful one. A business has to understand the consequences of its activity as well as perform the activity itself. The ledger eventually wants an answer, however interesting the algorithm may have been.
Execution produces activity. Reconciliation makes the records agree. Reporting makes the results legible.
A conceptual sequence, not a measurement of Anti Capital’s performance.Seen alongside his trading background, the accounting episode changes the scale of Shen’s responsibilities. The founder has to concern himself with systems that do not make trades at all. They make the company understandable. That work carries less romance than a market forecast, although romance has rarely been a reliable method of preparing a balance sheet.
Three chairs in Taipei
At Taipei Blockchain Week 2024, Shen appeared on a panel about advanced trading tools and the next generation of Web3 users. Vincent Liu and Hank Huang of Kronos Research joined the conversation. The setting was public and straightforward: three practitioners onstage, discussing tools in a field where the experience of using them matters alongside the technology beneath them.
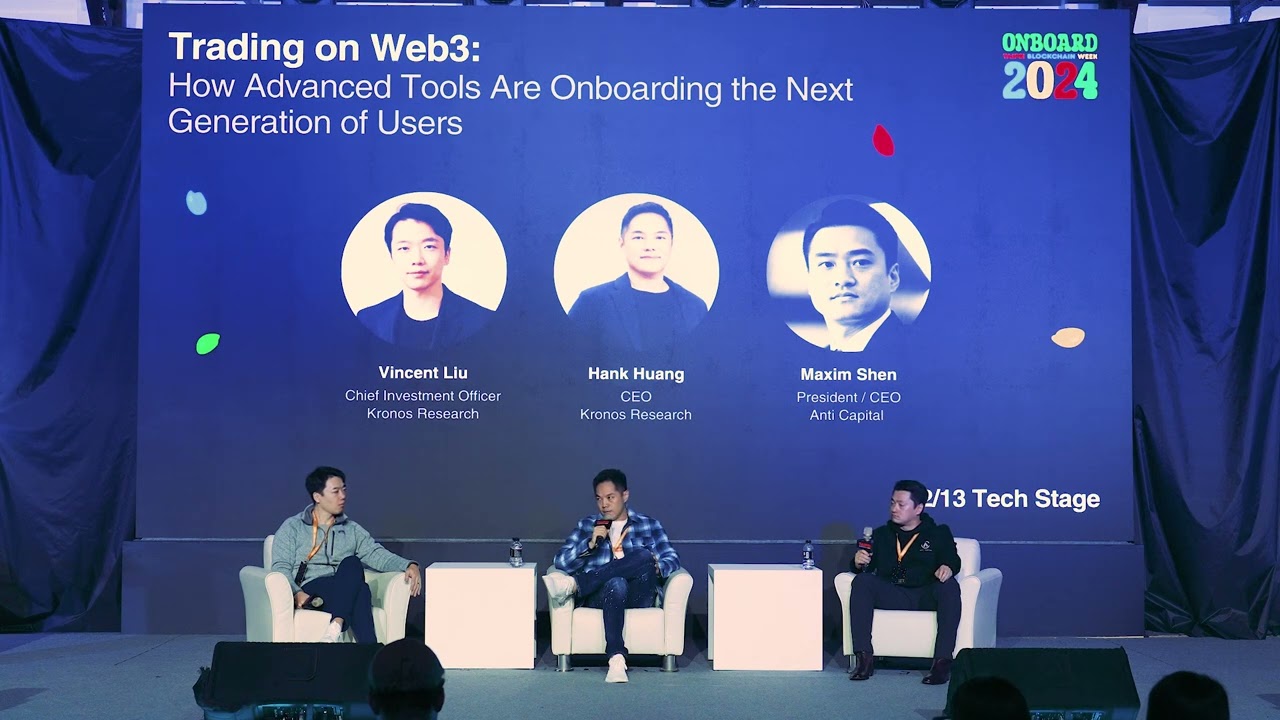
The photograph supplies a welcome change of scale. Market infrastructure sounds abstract until the people building and operating it sit down to talk. Shen is at the right of the stage, beneath a screen carrying the panel’s title. The subject brings a user into a story that might otherwise stay entirely among systems, algorithms, and firms.
His own announcement of the appearance emphasized connecting Web3 with traditional finance through high-frequency trading and market making. The published 2025 program returned him to a related subject: how trader frustrations shape the next generation of trading infrastructure. That September panel listed him alongside Liu, Youngsun Shin of Flipster, and Bella of Caladan.
The progression in the panel titles is interesting on its own. One asks about bringing people in; the other asks what bothers people already trying to trade. Both make room for the human consequences of technical choices. Neither requires inventing a personality for Shen. His participation gives the profile a public setting and a recurring professional subject.
A firm with two clocks
Anti Capital’s current description of its trading activity emphasizes systematic strategies, statistical arbitrage, and market-neutral modeling. Those are statements of approach. They describe how the firm intends to pursue opportunities, without turning the description into evidence of a particular return. For Shen, the company places the technical work of trading at the center of its identity.
Its venture activity works on a different schedule. Anti Capital says it supplies early capital and stress-testing expertise to founders developing DeFi protocols and exchange infrastructure, and brings portfolio companies into its internal research environment. The proposition puts practical trading conditions into the development process, where an investment relationship can include questions about how the software behaves.
Trading and venture investing therefore give the firm two clocks. One measures the immediate demands of execution. The other allows for a product and an organization to develop. The diagram below separates those purposes without pretending to quantify either one. It is a picture of the stated business, rather than a graph of success.
The next execution
Systematic strategies
Market connectivity
Internal trading book
The next working system
Early-stage capital
Technical stress testing
Protocols and exchange layers
For a founder with Shen’s background, the relationship between those clocks is the interesting part. A firm can encounter infrastructure through its own trading and also take an interest in the companies building it. That leaves him with a broader set of responsibilities than the individual market-making role with which his public career began.
The result is a story of successive working settings: trading firms, Injective, Anti Capital, a data-provider network, and conference stages in Taipei. Shen’s public ambition around Pyth adds a clear direction: making traditional-market information useful to decentralized finance. The achievement is concrete enough to follow through an announced partnership, rather than a prediction about the future.
And the accounting detail belongs beside it. Fast execution, useful information, and intelligible records are separate pieces of a functioning business. Shen’s story moves among them. The price on the screen remains pleasantly compact. Behind it, the founder has considerably more to keep in order.