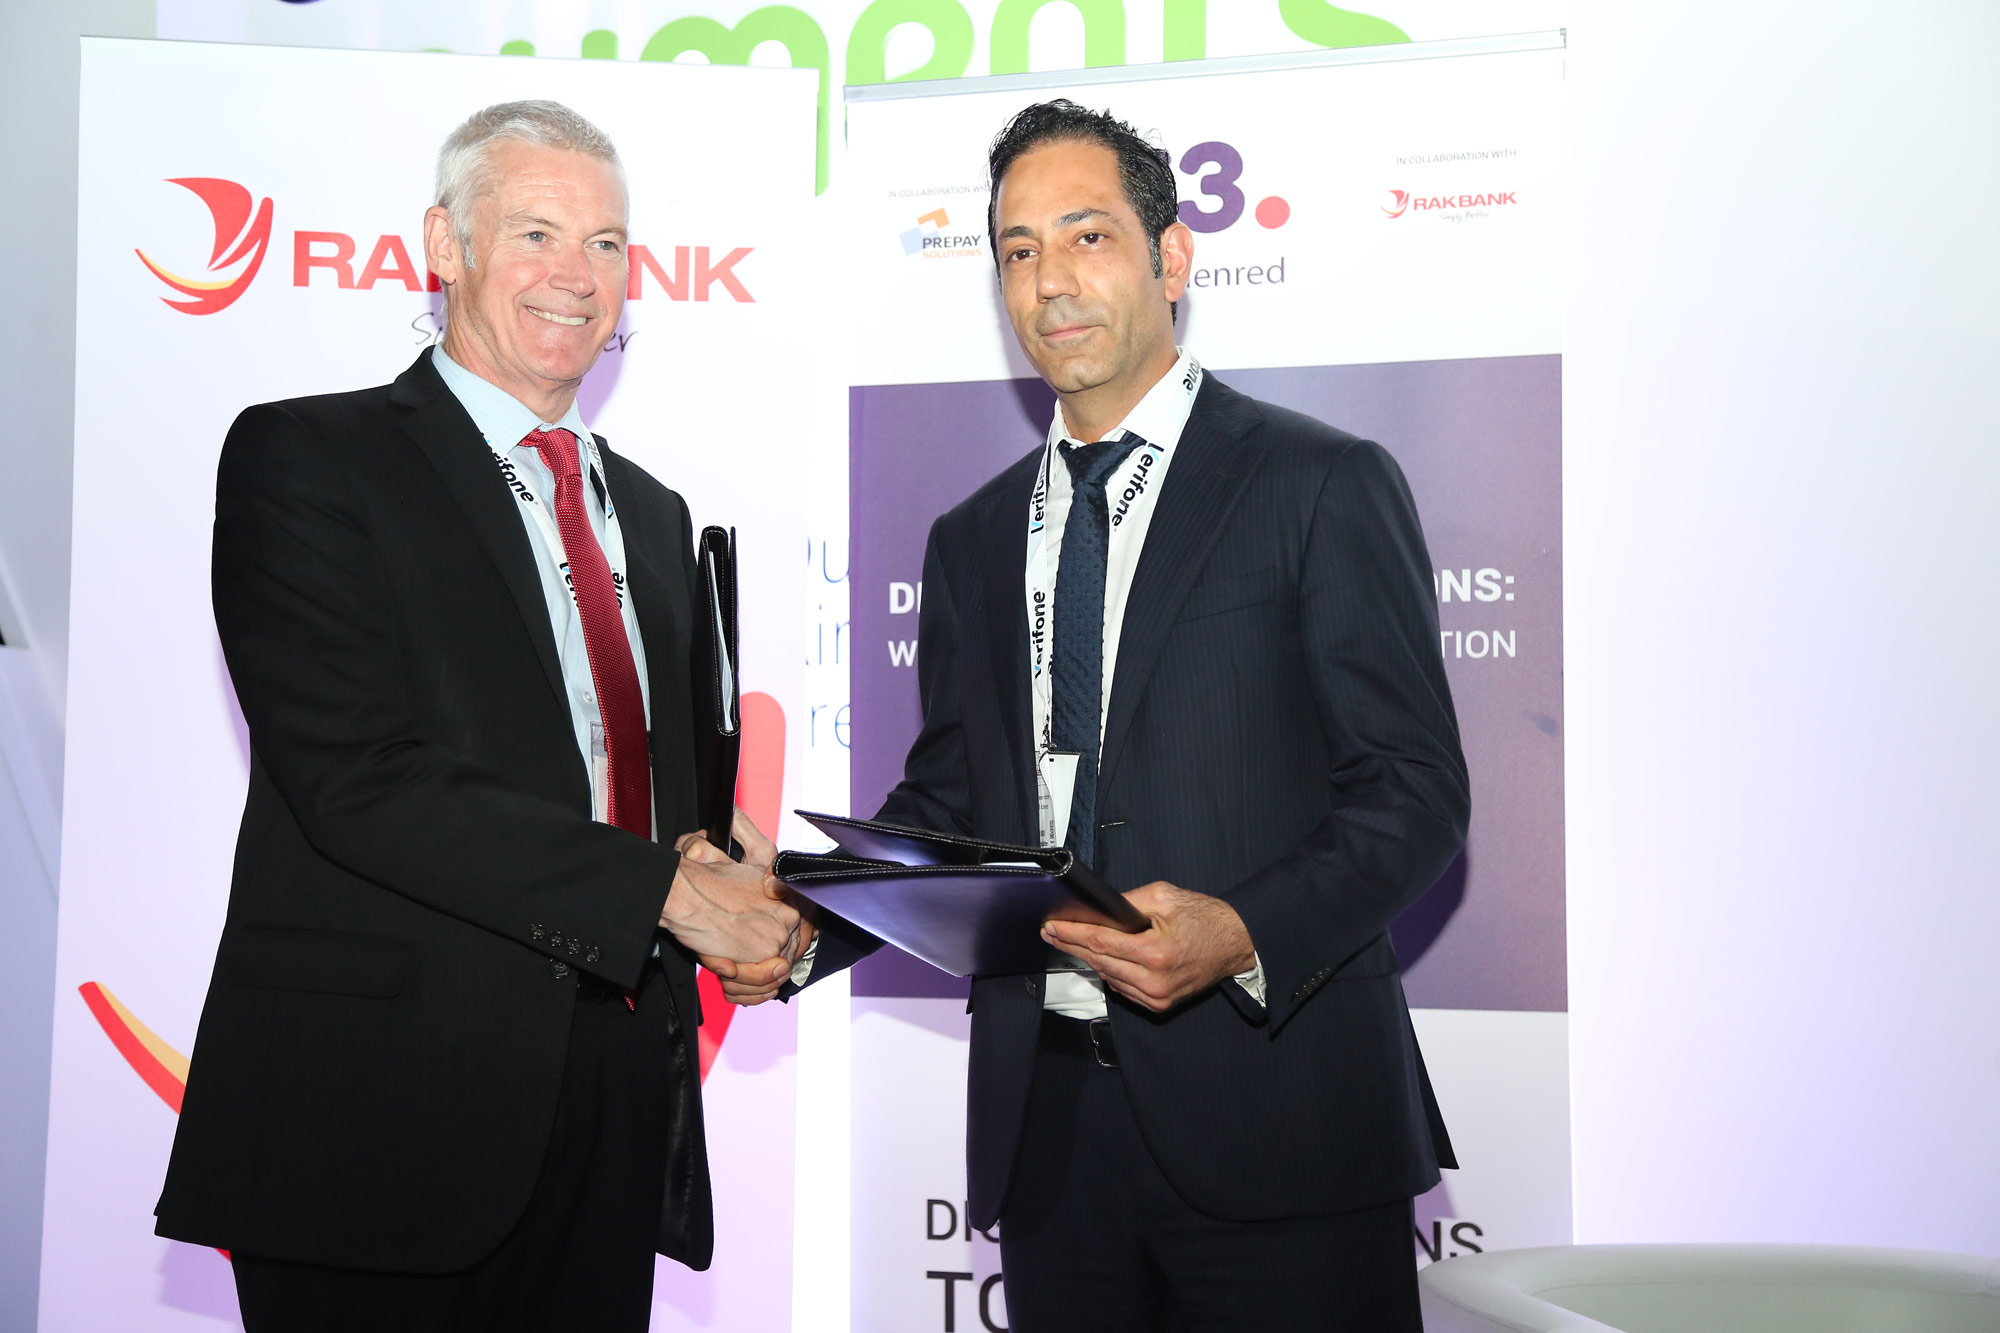
Four years before YAP’s UAE launch, Marwan Hachem stood beside a bank chief with a signed agreement and the sort of presentation folders that make a handshake official. The occasion was a C3 partnership with RAKBANK in Dubai in May 2017. Hachem was then an Edenred executive. The business concerned salary cards, payments and access to services for people without conventional bank accounts. In March 2021, YAP would launch with RAKBANK as its banking partner. A new app had arrived. The relationship behind it had some mileage.
That earlier photograph offers a useful entrance into Hachem’s career. Startup stories often begin at the moment someone decides to start a company, as though every previous job were merely a lengthy commute to inspiration. His story rewards a longer view. Before the banking app came the payment programs, the regional management role and the work of fitting a service around the people who needed to use it.
The payments apprenticeship
Hachem’s education included Collège Notre-Dame de Jamhour, the Sorbonne and Université Saint-Joseph. His professional route then took him through three cities. He worked at Accor Services in Lebanon from 2000 to 2006, with responsibility for introducing Ticket Restaurant. He moved from Beirut to Paris in 2006, continuing with the company, and headed to the UAE in 2015. There, his career included leading C3-Edenred across Africa and the Middle East.
The sequence matters because prepaid payments are a rather practical apprenticeship. They ask a product to do a particular job with money already assigned to a purpose. The appeal rests on whether the payment works, whether the recipient can use it and whether the arrangement makes sense to the organization paying for it. There is less room for a decorative promise when someone is waiting to spend their wages.
Looked at through that history, YAP becomes easier to understand. Hachem had spent years in the business of connecting payment services to ordinary needs. His move into consumer banking widened the setting. It brought the same basic questions into a phone: where is the money, what can the owner do with it, and how much effort stands between the two?
- BeirutAccor Services
2000-2006 - ParisContinued with Accor
From 2006 - UAEC3-Edenred leadership
From 2015
A familiar hand across the table
The 2017 C3 agreement was signed in the presence of Hachem and RAKBANK chief executive Peter England at Seamless Middle East. C3’s salary-card service addressed workers who lacked access to conventional banking. The partnership added a route to further financial services, including international transfers. Anas Zaidan, then C3’s managing director, also participated in the event’s discussion of salary payments and financial inclusion.
Both Hachem and Zaidan later became YAP co-founders. The continuity is striking without needing to turn it into a secret origin myth. Familiar colleagues and a familiar banking partner appear in the earlier chapter. They had already worked around the meeting point between a financial institution and a payments service. YAP gave that relationship a different consumer-facing form.
A partnership also makes the founder’s job more complicated than the phrase “build an app” suggests. The customer encounters one screen, while the service depends on several organizations doing their parts. A button can look wonderfully simple. The agreement that allows it to work may require rather more pages.
A bank account, minus the velvet rope
At YAP’s UAE launch, Hachem described an application that complemented conventional banks. RAKBANK provided account and card sponsorship. YAP offered spending information, transfers, bill payments and purchase notifications. Customers could freeze cards and set spending limits inside the app. There was no minimum balance or salary requirement for onboarding.
Those last conditions give the proposition its human scale. A minimum balance is a product rule with a very personal consequence: it decides whether an account fits someone’s circumstances. Removing that condition was part of the original offer. So were controls that let a customer act immediately rather than leave every adjustment to a later conversation.
For Hachem, the user experience was a stated priority. In a public post about YAP’s Best User Experience award at DIGIBANK2022, he described the founding goal of putting users in control of their finances. Awards are one way to recognize a product. The more revealing part of his explanation was the emphasis on what the person using it could actually do.
“User experience is key.”
Marwan Hachem, on YAP’s DIGIBANK2022 recognition
Consider the modest usefulness of a spending notification. It cannot improve a decision already made, but it can make the decision visible. A card limit can give a preference a boundary. A transaction history can turn a hazy recollection into something legible. These are small powers, which helps explain their appeal: they can be exercised on an ordinary day.
Pocket money gets a product brief
In April 2022, Hachem described another ordinary setting for the idea: children’s money. YAP’s youth proposition included parent-funded sub-accounts, cards, allowances, earnings from chores and savings goals. He discussed separate approaches for younger children and teenagers. Parents would remain involved, while the child would have a more direct experience of managing money.
The chores were called “missions,” a touch of product vocabulary that gives tidying up a promotion without necessarily improving its appeal. Under the label was a recognizable sequence. Do something, receive money, decide where it goes. The savings goal added the option of waiting. Banking here could be explained through choices a family already understood.
A parent funds an allowance.
A chore becomes a paid mission.
Money moves toward a chosen goal.
The youth plans sit comfortably beside the earlier salary-card work. Different customers, different responsibilities, but a familiar interest in making access useful. In one case, a worker receives wages. In another, a child receives an allowance. The amounts and permissions differ. Both situations give a financial product a job beyond displaying a balance.
The money arrives. The map gets bigger.
On July 4, 2022, YAP announced $41 million in funding. The investors included Aljazira Capital, Abu Dawood Group, Astra Group and Audacia Capital. More than 130,000 users had signed up for the app. The money was intended to support product development and expansion, and the company aimed to finish its Series A later that year.
Capital for the company’s next stage.
A dated funding announcement, not a valuation or a measure of personal wealth.Hachem discussed Saudi Arabia, Egypt, Pakistan and Ghana as intended destinations. Pakistan’s remittance market was a particular interest: workers in the Gulf sending money to families at home. It was a concrete reason to think across borders. The transaction starts in one country, but its usefulness is often waiting in another.
Forbes Middle East’s 2022 startup list subsequently recorded 190,000 onboarded users and 8,000 SME partners for YAP. It also described a relationship with Emirates Development Bank for small businesses. The numbers show the company’s reported reach at that point. They do not, by themselves, answer how often those accounts were used or how the economics worked.
That distinction was already part of Hachem’s public thinking. In a 2022 conversation about building a neobank, he emphasized active customers, budgeting and the need to adapt during expansion. Raising money gave the company resources. Turning a registration into a recurring relationship remained a separate piece of work.
The distance between a plan and a country
In his early 2023 discussion of YAP, Hachem addressed country-specific identity checks and the close coordination required between the company, central banks and partner banks. A recognizable product could travel, but its local arrangements still had to be built. The same conversation emphasized team alignment and a product that reduced difficulties for customers.
In January 2024, YAP’s Pakistan expansion acquired a harder chapter. Reporting based on people who had worked with the company described layoffs affecting almost all of a team of about 50. It also raised concerns about meeting requirements attached to the country’s preliminary electronic-money approval. YAP had not responded to the publication’s questions at the time.
The reported cuts belong in the story alongside the earlier ambition. They concern the company’s Pakistan operation; they do not establish what happened across every market. They do, however, show why an expansion announcement should keep its date attached. A destination on a plan and a functioning local service are different stages of a business.
Hachem’s long experience makes this tension particularly interesting. The earlier career demonstrates familiarity with payments and partnerships. The later setback demonstrates that familiarity does not remove the work of execution. A cross-border financial product must earn its place repeatedly, under different rules and with different practical demands.
The ordinary Tuesday test
Read together, Hachem’s public remarks keep returning to useful service, team coordination and customers who actually use the product. His professional story gives those concerns some context. It begins with payments work, continues through regional operations and reaches a banking platform built in collaboration with financial institutions.
The appealing part is how little ceremony the end customer should need. A salary arrives. A bill gets paid. A parent sends an allowance. Someone checks what they spent. Those are the moments around which his product ambitions have been described, however large the map behind them becomes.
The 2017 photograph remains an apt closing image. It shows the formal beginning of a partnership: folders, a handshake, people standing still long enough for a camera. The service itself would have to move. Years later, YAP placed a version of that challenge inside an app. The test continues wherever a customer has something more pressing to do than admire the banking.
Read, watch, follow
- YAP website
- Marwan on LinkedIn
- PwC interview · 28 minutes
- PYMNTS fireside chat · 23 minutes
- CFTE founder conversation
- C3 partnership video on YouTube
- 2017 partnership announcement
- 2021 launch interview
- 2022 funding coverage
- Early career in Lebanon and France
- YAP Young, April 2022
- Forbes Middle East, 2022
- Pakistan reporting, January 2024