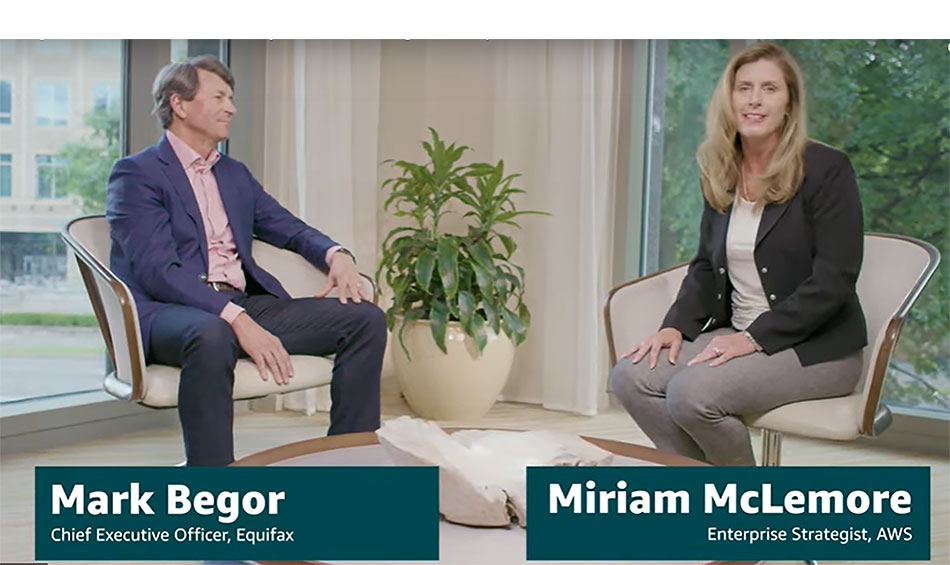
Mark Begor was nervous about making a video. He had run large businesses, dealt with complicated financial decisions and learned the language of corporate presentation. Yet an informal message to employees presented a small, awkward problem: there would be less machinery between the executive and the audience. No reassuring procession of takes. Less opportunity for someone else to tidy up the delivery. The business leader would have to sound like a person.
By 2013, while running GE Capital Real Estate, he had made a habit of it. Each week brought a five-to-ten-minute video about the business, a deal or something he had learned. Employees received recognition along the way. “I also add comments about employees that I want to recognize,” he said. He found that the routine clarified his thinking. A brief account of the week can be an unforgiving editor.
It is an appealing detail in a career otherwise measured in billions. Five years later, Begor would become chief executive of Equifax, an institution whose name had become inseparable from a breach of personal information. He would need to explain a much larger undertaking, to audiences with considerably less reason to give him the benefit of the doubt.
Five minutes without the polish
The videos offer a modest way into Begor’s public character. They establish a willingness to practice an unfamiliar form of communication, and a practical interest in making strategy intelligible. They do not tell us how he spends a Sunday or what every employee thought of him. Their value is more precise: here was an experienced executive discovering that a useful explanation required work.
A weekly message also gives leadership a timetable. There will be another week, another account of what happened, another opportunity for employees to compare the message with the business they recognize. It is an unusually ordinary discipline for someone whose later assignments would come with an abundance of extraordinary numbers.
An education in other people’s businesses
Begor’s formal education combined finance and marketing at Syracuse University, followed by an MBA at Rensselaer Polytechnic Institute. The combination suits the career that followed: understanding the economics of a business and understanding how that business reaches somebody else. His professional biography moves through industries that would seldom share a shop window.
He spent 35 years at General Electric. His assignments included chief financial officer at NBCUniversal Media and GE’s investor relations leadership. Television finance and investor communication are useful reminders that his background extends beyond the credit industry. A balance sheet may travel comfortably between sectors; the people, customers and operational problems require a fresh introduction.
He led GE Capital Retail Finance, the business now known as Synchrony Financial, and later GE Capital Real Estate. The first put him close to the everyday mechanics of consumer borrowing. The second involved a different set of assets and risks. He then led GE Energy Management, moving into an industrial business. The résumé has the range of a department store, with rather fewer opportunities for an impulse purchase.
When GE announced his retirement in 2015, it traced his career back to 1980. He had become a company officer in 1996 and a senior vice president in 2005. Those dates give the career its scale: decades spent inside a large organization, with changing responsibilities and different businesses to understand.
Warburg Pincus followed in 2016, where he became a managing director. He also served on FICO’s board from 2016 to 2018. By the time Equifax approached, he had experience as an operator, an investment-firm executive and a director at a credit-scoring company. More unusually, he knew the bureau’s world from the customer’s side through consumer lending.
The job after the breach
Equifax announced his appointment in March 2018; he took over in April. The 2017 cyberattack had occurred before he arrived. That distinction matters to the chronology. For the incoming chief executive, however, the consequences were part of the job waiting on his desk.
A credit bureau has an unusual relationship with the public. Its information can help a lender evaluate an application, while the person described by that information may have little occasion to think about the company until a consequential moment. A house purchase or car loan makes an abstract database suddenly personal. Confidence, in that setting, has practical content.
Begor’s early response combined changes in leadership, spending and incentives. In his 2019 congressional testimony, he described hiring nearly 1,000 full-time technology and security professionals during 2018. Jamil Farshchi became chief information security officer, reporting directly to him. Bryson Koehler joined as chief technology officer after serving in a technology leadership role at IBM Watson and Cloud Platform.
There was also a detail with less visual appeal than a new executive appointment: a company-wide security goal in the annual bonus plan for eligible employees. It moved responsibility into the calculation of rewards. Security had a place in the compensation conversation, including for people outside the security department.
“I take this responsibility very seriously.”
Mark Begor, Senate testimony, April 2023
The rebuilding effort eventually became an extensive cloud transformation. Equifax’s June 2025 biography described a $3 billion investment over seven years and said the North American cloud transformation had been substantially completed in 2024. For Begor, modernizing the infrastructure became part of the argument for the company’s future products as well as its security work.
A bigger engine, with obligations attached
Annual revenue provides one way to follow the changing business. Equifax generated approximately $3.4 billion in 2018. Its 2025 annual report recorded $6.075 billion. Those endpoints describe substantial expansion during Begor’s tenure. They cannot, by themselves, separate every contribution from acquisitions, product development, pricing or market conditions.
Two annual snapshots. Revenue is a measure of business scale, not a consumer-trust score.
Acquisitions also widened the company’s capabilities. When Equifax announced in November 2024 that Begor would continue as CEO beyond 2025, it reported more than $4.5 billion invested in 25 bolt-on acquisitions since 2018. The term sounds delightfully manageable for expenditure of that size. Each addition still has to become part of a functioning business.
Begor has connected the company’s development to wider access to credit. In his April 2023 Senate testimony, he discussed using information beyond conventional credit histories, including telecommunications and utility payments. The stated ambition was to give lenders a fuller picture of people whose traditional files provided limited information.
The idea has a straightforward human appeal: somebody’s financial life contains more than the evidence in a familiar credit file. Turning that proposition into useful lending information raises demanding questions about accuracy, responsible use and whether the resulting decisions help consumers. Begor’s aspirations sit inside those questions. Adding information increases the importance of handling it well.
The numbers still have to be right
The rebuilding story includes a failure during his tenure. In June 2022, Fannie Mae notified lenders of an Equifax coding issue that could cause errors in credit scores and credit data. Its notice said approximately 12% of credit scores issued during the identified period, when based on Equifax data, might have been affected.
That episode belongs beside the investment figures. A consumer encounters an individual decision, rather than the average condition of a company’s technology estate. A system can be undergoing an expensive transformation while a particular output is wrong. The existence of a rebuilding programme does not settle the question that matters to the person applying for a loan.
Equifax’s September 2026 quarterly filing said the company and plaintiffs’ attorneys had reached an agreement in principle in June to settle related nationwide class claims, with a motion for settlement approval filed in August. An agreement in principle and a request for approval are specific stages, rather than a reason to write the episode out of the account.
Begor’s work therefore invites two kinds of examination. One concerns the business he has expanded and the infrastructure he has changed. The other concerns the reliability of the service that reaches people outside the organization. Both belong in a fair account of his leadership. Revenue is a useful number; an accurate credit decision has its own importance.
The next quarter arrives anyway
His experience continues to find an audience elsewhere. In May 2025, Raymond James elected Begor to its board and placed him on its Audit and Risk committees. Those assignments fit the long-running combination in his career: financial oversight and the practical business of managing risk.
At Equifax, the next test is already measurable. On October 20, 2026, the company reported third-quarter revenue of $1.693 billion, up 10% on a reported basis. It also lowered its full-year revenue guidance midpoint to $6.661 billion, citing a weaker U.S. mortgage market. Growth and constraint arrived in the same announcement.
The company reported a new-product Vitality Index above 17%, compared with its long-term goal of 10%, and continued pursuing a $150 million AI productivity goal. These are different kinds of numbers: a reported product metric, a benchmark and a target for work still to be delivered. Begor’s next chapter depends partly on keeping those distinctions clear.
The executive who once learned to condense his week into a short employee video now has a longer story to explain. It contains expanded revenue, rebuilt infrastructure, mistakes and unfinished obligations. The audience includes investors and employees, but also people whose next financial decision may depend on the information Equifax provides. For them, the explanation becomes persuasive when the ordinary transaction works.