Julie Stephenson brought Kevin Leidwinger a resignation letter. Her daughter was still a baby, and she was trying to reconcile a career she loved with being a parent. He handed the letter back. As she later recalled his response: “we’re going to solve this problem.” An alternative work arrangement followed. She stayed.
It is a revealing place to begin a story about an insurance executive. The useful question was whether the arrangement could change before the relationship ended. A resignation is usually filed as a conclusion. Here it became a subject for negotiation.
Years later, in January 2023, Stephenson became executive vice president and chief operating officer of UFG Insurance. Leidwinger had become its president and CEO the previous August. Their working lives had crossed at Chubb and CNA; now they would share responsibility for changing a company based in Cedar Rapids, Iowa. The old conversation about keeping someone in a job had acquired a much larger setting.
A political science graduate in a world of risk
Leidwinger’s undergraduate degree was in political science, from Dickinson College in Carlisle, Pennsylvania. His career subsequently became an education in the many ways businesses can incur losses. At Chubb, his responsibilities included global liability and U.S. field operations, before he became global casualty manager.
The portfolio he oversaw in that last role amounted to $3.3 billion worldwide. It covered general liability, workers’ compensation, excess umbrella, auto, errors and omissions, and environmental business. Each label represents a different collection of obligations. Managing them together requires an appreciation of the differences, as well as a view of the whole.
CNA appointed him president and COO of its commercial operation effective June 22, 2015. He reported to chairman and CEO Tom Motamed. The assignment was to execute underwriting and profitable growth strategies. Motamed singled out his consistency in selecting risks and managing underwriting processes, alongside his ability to build working relationships. That combination would recur throughout his career: technical judgment, exercised through other people.
President & COO
Board chair
President & CEO
At CNA, the team around him also took shape. Stephenson became commercial chief underwriting officer in September 2015, reporting to him. John Beckman moved into a chief transformation officer role. Their responsibilities joined the assessment of exposures with the search for products and business opportunities. A commercial insurer has to decide both what it wants to write and how it will manage the promises it makes.
In May 2021, NCCI’s members elected Leidwinger board chair. The organization gathers insurance data, studies trends and develops rate and loss cost recommendations. It was a governance role close to the industry’s analytical machinery. Lisa Corless succeeded him effective April 30, 2022. By that summer, his next operating assignment had been announced.
The first results were uncomfortable
UFG chose Leidwinger to succeed Randy Ramlo, who had been CEO for 15 years. His first day was August 22, 2022. He arrived with more than three decades in insurance and a mandate that combined continuity with change. The board wanted the company’s culture maintained while its capabilities developed.
“It is an incredible honor to lead UFG,” he said when his appointment was announced. His priorities included sustained profitability, agency relationships, growth across different parts of the business and innovation. Those are easy ambitions to announce. The difficulty lies in the sequence of decisions required to make them compatible.
The second quarter of 2023 supplied a difficult early test. UFG recorded a $56.4 million net loss. Its combined ratio reached 132.9%, with reserve strengthening and catastrophe losses weighing on the result. Leidwinger explained that deeper actuarial analysis had changed the company’s estimates of ultimate losses. Improving the view of the business had produced an uncomfortable immediate number.
In the same period, UFG created distinct underwriting business units for small business and middle market customers. Leidwinger described a move from generalist operations toward greater specialization. The organizational change mattered because businesses of different sizes bring different exposures and service demands. A broader menu of insurance requires people who understand what each item entails.
This was the less photogenic portion of a turnaround: revisiting estimates, changing responsibilities and developing expertise. There is little ceremony in discovering that an old promise may cost more than expected. Yet an insurer’s future decisions depend on how accurately it understands the promises already on its books.
“we’re going to solve this problem.”
Kevin Leidwinger, as recalled by Julie Stephenson
The arithmetic begins to change
By the end of 2024, the annual results showed a different direction. UFG’s combined ratio was 99.2%, an improvement of 10.1 percentage points over 2023. Net written premiums rose 15% to $1.2 billion. Net income reached $62 million. The company was growing while its underwriting result moved back below the 100% line.
A combined ratio gives this story some unusually legible arithmetic. It adds an insurer’s loss and expense ratios. Below 100% indicates an underwriting profit; above 100% indicates an underwriting loss. Investment results sit outside that particular measure. For anyone accustomed to corporate success being described through adjectives, a number with a dividing line is a welcome courtesy.
Less of each premium dollar
going to losses and expenses
The following year brought a further improvement. For 2025, the combined ratio fell to 94.8%. Net income was $118.2 million, and return on equity was 13.7%. Net written premium increased 9% to approximately $1.3 billion. The board also raised the quarterly dividend from 16 cents to 20 cents a share.
Leidwinger connected the performance to changes in expertise, capabilities, actuarial insight and relationships with distribution partners. The distinction matters: a favorable outcome can reflect several forces at once. In 2025, the company’s catastrophe loss ratio also improved. The operating changes and the year’s loss experience belong in the same account.
The second quarter of 2026 continued the progress. UFG reported $33.4 million in net income, net written premium of $406.4 million and a combined ratio of 95.3%. Catastrophe losses were lower than in the comparable quarter. The underlying combined ratio, which removes catastrophe losses and prior-year reserve development, edged up 0.1 point to 92.6%. Even a good quarter contains details worth keeping in view.
Who gets to do the work?
The public record of the transformation includes some wonderfully unglamorous job descriptions. In March 2026, Michael Shneibaum took charge of UFG’s middle market business unit, with strategic responsibility across its 32-state footprint. In June, Greg Francis became vice president of field operations, responsible for market strategies and support for agency partners at national and local levels.
Then, in July, Nathan Root became vice president of underwriting enablement. His remit included workflow efficiency, technical expertise and the product set. These appointments give substance to the word “capabilities.” Someone has to own the processes, someone has to understand the risks, and someone has to make the relationship work when an agent brings in business.
Leidwinger’s board had already evaluated the human side of that work. Its assessment of his 2023 goals included recruiting a strong team, executing strategic initiatives and improving communication among underwriting, claims and actuarial leaders. Expertise becomes more useful when the people holding it can compare what they see.
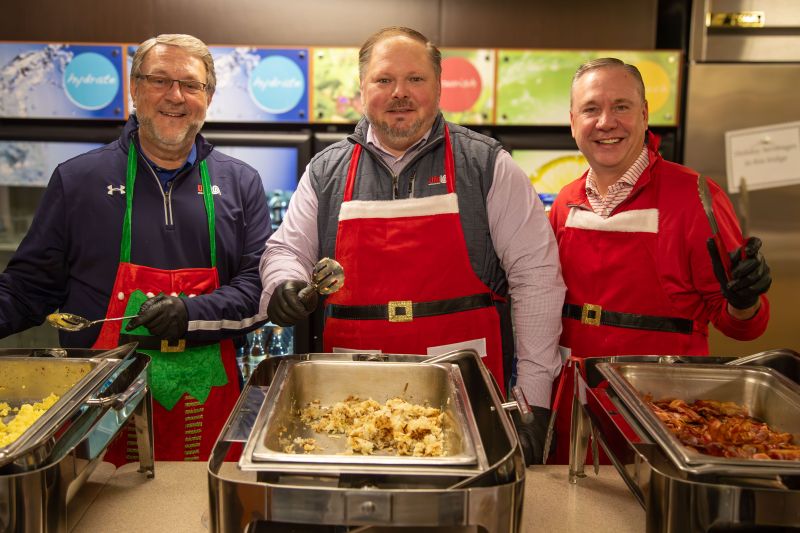
A December 2025 employee breakfast offers a lighter view of the leadership team. Leidwinger joined Brian Rawlins and Eric Martin in serving breakfast, with festive aprons included. Insurance has many specialized functions; that morning, the available evidence suggests the buffet required a few generalists.
Eighty years, and another quarter to prove it
UFG marked its 80th anniversary on January 2, 2026. Founded in Cedar Rapids by Scott McIntyre Sr., it had grown to more than 850 employees and approximately 850 independent agency partners. Leidwinger was its sixth leader. The anniversary also fell 40 years after the company began trading on Nasdaq.
He used the occasion to emphasize his respect for the company’s people and values. Its community commitments had a practical anniversary expression too: the UFG Foundation awarded $80,000 in additional grants to nonprofits recommended by employees who volunteered with them. The grants were separate from its regular funding cycles. That was a company initiative, with employees helping identify where the money would go.
His responsibilities also extend to questions that cannot be settled in a single reporting period. In UFG’s 2025 climate disclosure, he described incorporating climate considerations into corporate planning and communicating how the company manages those risks. For a property and casualty insurer, understanding changing exposures is part of understanding the business it agrees to insure.
As of October 22, 2026, the next scheduled public checkpoint was already on the calendar: third-quarter results on November 3, followed by an earnings call on November 4. An anniversary permits reflection. A reporting calendar is rather less sentimental.
The question running through Leidwinger’s career is practical: how should the work be arranged so that people can do it well? It appears in specialist teams, in the connections among departments and in a colleague’s recollection of a returned letter. At UFG, that question now has employees, agents, policyholders and shareholders waiting for the answer, one decision at a time.