The credit card is a pocket-sized argument about ownership. A bank’s logo sits on the front. Behind it hum processors, networks, risk models, call centers, compliance teams and settlement files. The customer sees one name; the transaction may pass through a small republic of specialists. For much of Keith Floen’s career, his work has lived inside that gap - between the institution the customer knows and the infrastructure the customer should never have to think about.
Floen is the Chief Marketing Officer of Atlanta-based CorServ, a company that helps banks and fintechs issue credit cards. His title sounds like the job begins with a message. His record suggests it begins much earlier, with the operating facts that make a message believable. Can a bank keep its economics? Can it see its program data? Can it decide the difficult applications? Can the technology sit quietly enough for the bank’s own relationship to remain in the foreground?
These are current fintech questions, decorated now with virtual cards, tokenization and APIs. Floen has been working on their older versions since 1984. That date matters. It puts the beginning of his card career before the commercial web, before mobile banking, before a frozen card could be thawed with a thumb tap. The machinery changed extravagantly. The human concern underneath it barely moved.
The card school before the internet
Floen joined Credit Union Card Services, then wholly owned by CUNA, in 1984. He moved from vice president to executive vice president, then general manager, and became president in 1992. By the end of his tenure in 1996, the organization serviced about 2,500 credit unions and roughly seven million cardholders. Those numbers are not trivia. They describe the school in which his view of payments was formed: many institutions, millions of account holders, and a business where a tiny operational failure can be repeated at industrial scale.
While working in the industry, Floen attended Northwestern University’s Kellogg School of Management from 1986 to 1988 and earned an MBA. He had previously completed an undergraduate degree at Winona State University. The overlap between study and operating experience is telling. Card issuing does not divide politely into marketing, finance and technology. It is a product, a loan, a regulated service and a daily customer ritual. Learning the business means learning to hold several truths at once.
In 1996, Floen moved into managing-director work at InfiCorp and InfiBank. A 2002 corporate filing placed him in Atlanta as Managing Director for Credit Union Business Development. InfiCorp bought and managed card portfolios from credit unions and community banks. The arrangement created an awkward question: when an institution sells a portfolio, has it also sold a piece of the member relationship?
“Everybody wants a silver bullet in this credit card business but there aren’t any.”Keith Floen, 2002
Floen’s answer was unusually demanding of his own side. He said a partnership had failed if, after two years, the credit union did not have “better and deeper relationships” with its cardholders. InfiCorp had no reason to put its own brand in front of those members, he explained. It made money from the card business, not by slipping other products across the counter. The ideal provider, in this formulation, was essential backstage and nearly invisible out front.
It is a sophisticated marketing position because it refuses the usual vanity. The provider’s success is measured partly by how convincingly the client remains the star. Credit unions kept branded websites and relationship managers who could address problems. The member could experience a better card program without learning the name of the company operating underneath it. There are businesses that rent attention. This one aimed to return it.
A platform arrives; the question stays
Floen joined CorServ in 2010 and is publicly listed as its Chief Marketing Officer. CorServ itself was established in Atlanta in 2009 by veterans of card banking and technology. The continuity is visible in the cast as well as the subject. Jerry Craft, an InfiCorp founder and president, became CorServ’s chairman. Other leaders brought experience from InfiCorp, large issuers, processing companies and bank-card operations. Institutional memory became part of the architecture.
CorServ’s contemporary language is different from the portfolio debates of 2003. It offers turnkey issuing for banks, self-issuing technology and a Payment Cards-as-a-Service API platform for financial institutions and fintechs. Its systems cover applications, underwriting, real-time authorization, physical and virtual cards, controls, alerts, reporting, rewards, disputes, fraud, KYC and settlement. The software is modern. The proposition still turns on a question Floen was already asking: how much of the program can the institution truly call its own?
In a turnkey arrangement, a client bank can keep its brand and participate in decisions while using shared issuing, compliance and servicing infrastructure. In a self-issuing arrangement, the bank takes fuller ownership and configures products on established technology. With APIs, a fintech can construct a new experience while relying on the less photogenic necessities behind it. The routes differ. Each separates what must be owned from what can be expertly supplied.
Joined Credit Union Card Services.
Became president after progressing through senior operating roles.
Moved into managing-director work at InfiCorp and InfiBank.
Set out a relationship-first test for card-portfolio partnerships.
Joined CorServ, where he is listed as Chief Marketing Officer.
The CMO’s challenge here is peculiar. A consumer marketer can sell a feeling and let someone else worry about the pipes. A payment-infrastructure marketer must know which pipes can burst. Every clean promise sits downstream from credit decisioning, network rules, fraud controls, security certifications and the ugly choreography of a disputed charge. The copy may say “simple.” The organization has to earn that word by absorbing complexity rather than denying it.
Floen’s old silver-bullet warning belongs here. Payments periodically falls in love with a single answer: a new rail, a new interface, a new distribution trick. His public remarks point in the opposite direction. Good card programs are assembled from aligned incentives, operational patience and a clear division of responsibility. A platform can shorten the distance. It cannot repeal the terrain.
What he notices when he is off the clock
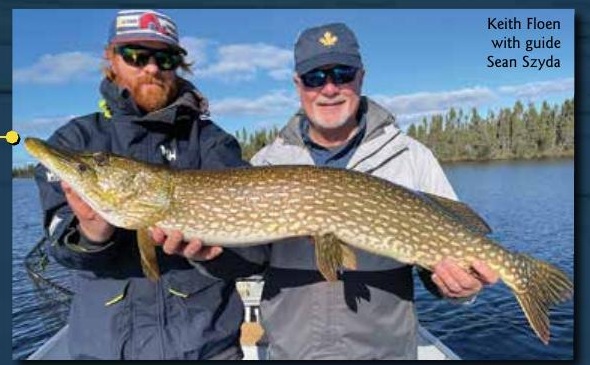
One recent public photograph places Floen far from payment rails. He stands beside guide Sean Szyda, both men holding a northern pike wide enough to require cooperation. The accompanying comment is not a boast about the fish. Floen praises a staff member who noticed his fishing partner had wet clothes, collected them without being asked and returned them the next morning with the coffee service.
It is one anecdote, and it should remain one anecdote. Still, it has the neat shape of his professional thesis. The most memorable service often happens offstage. Someone notices friction, resolves it and gives the relationship back in better condition. The guest remembers the lodge, not the laundry logistics. The cardholder remembers the bank, not the processor. Invisible work earns visible trust.
The fish got the photograph. The quiet act of service got his attention.A small clue to a long operating philosophy
Floen keeps a spare public profile. There is no stream of personal slogans, no obvious campaign to become a payments celebrity. The available record is mostly institutional: job titles, filings, a handful of interviews, and the products his companies offer. That reserve fits the business he has described. He has spent a career arguing, in effect, that the supporting brand need not insist upon itself.
CorServ now sells card issuing in a market full of newer vocabulary and louder claims. Its own pitch includes speed, flexibility and developer-friendly tools, but it also speaks the older dialect of accountability: program data, risk, compliance, servicing and economics. Floen’s experience connects those eras. He knew the portfolio world before the platform world. He knows that an API is not a relationship. It is a way to build one, provided the unglamorous obligations arrive with it.
The name that remains
There is an appealing consistency in the arc. At Credit Union Card Services, Floen worked at the scale of thousands of institutions. At InfiCorp, he explained why an outside card manager should deepen a credit union’s bond with members. At CorServ, he helps present a platform designed to give banks and fintechs more ways to configure, operate and own card programs. Four decades pass. The nouns change. The sentence underneath them does not.
The card in a wallet is still a small flag for a larger promise. It says the institution will decide well, keep data safe, recognize fraud, settle accurately and answer when something goes sideways. Most customers will never diagram the organizations behind that promise, nor should they. Their ignorance is not a failure of education. It is often evidence that the infrastructure worked.
Floen’s career is useful precisely because it resists the tidy before-and-after story technology likes to tell about itself. The old world was not merely slow; it contained hard-won knowledge about trust. The new world is not merely fast; it gives smaller institutions tools once reserved for national issuers. The interesting work is carrying the knowledge forward without carrying every old limitation with it.
A bank may outsource code, operations or network access. It cannot outsource the meaning of its own name. Keith Floen understood that when card portfolios changed hands in the early 2000s. CorServ’s technology gives him newer ways to make the same argument. The plastic may become virtual, the controls instantaneous and the interface programmable. The relationship still has to belong to someone.