A merger can leave behind something more revealing than a larger company. In John Rademacher’s case, one left behind no company at all. On June 26, 2023, Option Care Health announced the end of its agreement to combine with Amedisys. A plan unveiled less than two months earlier was over. There would be a $106 million termination fee, but no combined business for him to lead.
Rademacher acknowledged the disappointment. Then he returned to the language of acquisition discipline. It was a small, instructive moment in a career spent assembling people, systems and organizations: the executive who had helped bring two companies together in 2019 was now explaining why another combination would stay on paper.
Corporate biographies tend to favor completed transactions. A failed agreement is less cooperative. It interrupts the upward line, asks awkward questions and refuses to fit neatly beside the degree certificates. For Rademacher, it also supplies a useful way into the story. His career has involved both expanding an organization and deciding what its expansion should cost.
The accounting graduate in the operating chair
Rademacher earned a bachelor’s degree in accounting at Hillsdale College and an MBA at Wayne State University. His education placed him in Michigan before his executive work took him through Cigna, Cardinal Health and, eventually, Option Care. The sequence joins financial training to responsibility for large organizations.
At Cigna, he held the presidency of CareAllies and a chief operating officer role. At Cardinal Health, he served as president and general manager of two divisions. These were established businesses with existing teams and obligations. His route to the top ran through management posts inside other people’s organizations.
That distinction matters when considering his later decisions. An operator inherits a working business, along with its unfinished tasks. There are systems to replace while employees still use them, investments to justify before the benefits arrive, and promises made by predecessors that remain quite alive. The job offers fewer blank sheets of paper than its title might suggest.
In 2015, Rademacher joined Option Care as chief operating officer. His remit included a substantial redesign of the operating model, with investment in personnel, processes, technology and facilities. Logistics and revenue management were part of that assignment. The work sat behind the public face of the business, where a strategic plan has to become somebody’s Monday morning.
The interim title comes off
In August 2017, he became interim CEO. On January 4, 2018, the board made the appointment permanent after an extensive search. Chairman Harry Kraemer singled out his strategic and analytical perspective. Rademacher had arrived with responsibility for how the organization worked; now he was responsible for where it went.
The interim period gives the appointment an everyday human dimension. For several months, he carried the role while the search continued. Whatever the board might eventually decide, the company still needed someone to run it. His promotion followed a period of doing the work under a provisional title.
Asked in early 2018 about the company’s success, Rademacher began with its employees. He also described investment across the business as a way to support growth and win market share. The answer connected the people already there with the infrastructure they needed. Technology appeared as part of running the organization, alongside training and equipment.
There is a certain modesty in the subject matter, even when the ambitions are large. A new operating model does not usually receive a ceremonial unveiling. A functioning billing process is unlikely to attract a standing ovation. Its absence, however, can draw quite an audience.
Two histories, one management team
The BioScrip merger supplied the first major combination of his CEO tenure. The transaction closed on August 6, 2019, and the completion was announced the following day. The combined organization took the name Option Care Health. Rademacher became its CEO, Mike Shapiro its chief financial officer, and Kraemer its chairman.
Those names provide continuity across the change. The company’s headquarters remained in Bannockburn, Illinois. An executive team familiar with the legacy Option Care business would lead a company containing another organization’s people, operations and history. A merger announcement can settle the leadership chart quickly. Getting the combined organization to work together takes longer.
Before the deal closed, Rademacher had emphasized the fit between BioScrip’s local relationships and Option Care’s infrastructure. It was an argument about complementary capabilities. One side brought relationships and experience; the other brought systems and a national operating structure. The proposed benefit depended on connecting those assets without losing what made them useful.
The completion announcement placed investment in people, technology and operations among the combined company’s priorities. The vocabulary was familiar from his COO assignment four years earlier. His responsibilities had broadened, but the practical ingredients of the plan were much the same.
- 2015Joins Option Care as COO
- 2018Becomes permanent CEO
- 2019Leads the combined Option Care Health
- 2023Amedisys agreement ends
- 2026Proposed sale to CD&R and McKesson
A Chicago dinner, then a different ending
The Amedisys negotiations offer a more detailed glimpse of Rademacher at work. On March 31, 2023, he discussed a counterproposal with Option Care Health’s transaction committee, then called Amedisys chairman Paul Kusserow. The discussions concerned the share of the combined business that Amedisys stockholders would own.
Two days later, Rademacher met Kusserow and incoming Amedisys CEO Richard Ashworth for dinner. Another dinner followed in Chicago on April 10, with Kraemer also present. Meanwhile, advisers and executives were opening data rooms, examining the businesses and negotiating terms. The work moved between conversations over a table and the less sociable company of transaction documents.
On May 3, the companies announced an all-stock agreement valuing Amedisys at approximately $3.6 billion, including net debt. Rademacher was to continue as CEO of the combined organization. The ownership split, once completed, would give Option Care Health stockholders approximately 64.5% and Amedisys stockholders approximately 35.5%.
By June 26, the agreement had ended. Option Care Health would receive the termination fee. Rademacher’s public response emphasized acquisition discipline. That response deserves to sit beside the earlier announcement. Both belong to the record.
“We take a disciplined approach to acquisitions”.
John Rademacher · June 2023
Ending the agreement did not make its original ambition disappear. It changed the result against which that ambition could be judged. The company had negotiated, announced a combination and then returned to its own course. For an executive profile, that is a more useful episode than an uninterrupted procession of closing dates.
The numbers resist a tidy plot
Option Care Health reported $5.65 billion in net revenue for 2025, an increase of 13% over the previous year. Net income was $207.6 million, down 2%. Operating cash flow reached $258.4 million, and the company repurchased $307 million of its shares during the year.
Put together, those figures complicate a simple growth story. Revenue grew considerably faster than net income. Cash generation and share repurchases added another set of decisions about the use of money. Running the company meant attending to all of those measures, with each describing a different part of its performance.
In the second quarter of 2026, net revenue rose 1.9% to approximately $1.44 billion. Net income increased 6.7% to $53.9 million. The company also repurchased $150 million of shares during the quarter. Rademacher praised the team’s execution while acknowledging that more work remained. The figures offered progress, with a slower pace of revenue growth than the preceding full year.
Another boardroom, the same question about people
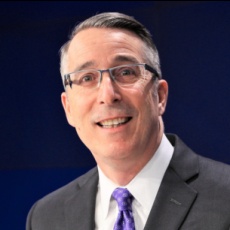
In 2026, Rademacher joined the board of Thrivent, the member-owned financial services organization. He serves on its Human Resource & Governance committee. The appointment adds a different setting to his executive work: a board serving a membership organization, with a committee assignment directly concerned with people and governance.
His August 2026 interview returned to the practical limits of growth. He discussed recruiting, retaining and developing employees, and the importance of training as the business changes. His conclusion was plain: “ultimately the service depends on having great people in place.” It echoes the emphasis of his first year as permanent CEO.
That recurrence is more revealing than a newly minted management slogan. Across eight years, his public explanations repeatedly return to employees and the systems around them. The organizational challenge keeps growing, while the underlying question stays recognizable: can the business build and retain the capabilities its plans require?
The next signature is still ahead
On October 6, 2026, CD&R and McKesson announced an agreement to acquire Option Care Health for $32.05 per share in cash, with an enterprise value of approximately $5.8 billion. The proposed ownership split is about 51% for CD&R and 49% for McKesson. Option Care Health would remain a separate company led by its own management team.
The expected closing is in the first half of 2027, subject to stockholder approval, regulatory clearances and other customary conditions. As of October 21, 2026, it remains an announced transaction. Rademacher has described the prospective backing as support for further strategic investment and faster technology deployment.
His career has now placed him on several sides of the same business question: how much change can an organization turn into useful work? He has inherited operations, led a combination, negotiated another that ended and supported a proposed sale. The accounting graduate has accumulated plenty of occasions to weigh a promise against its terms.
The next closing date is still ahead. So is the work that would follow it.
Continue reading
- Official leadership biography
- John Rademacher on LinkedIn
- 2019 merger announcement
- 2023 negotiation chronology
- Amedisys agreement ends
- 2025 business results
- Second-quarter 2026 results
- August 2026 interview
- Thrivent board biography
- October 2026 transaction announcement
- 2019 CEO video message
- Option Care Health website