An air compressor is an odd thing to build a relationship around. It sits away from the finished product, making noise and pressure. Nobody buying a drink admires the compressed air used to make its bottle. Yet for the manufacturer, that uncelebrated machine creates a very personal question: what happens to the production line when the air stops?
- The job: move air, liquids and powders through processes that depend on them.
- The economics: sell equipment, then supply parts, consumables and service.
- The tension: acquisitions widen the portfolio, but their forecasts can disappoint.
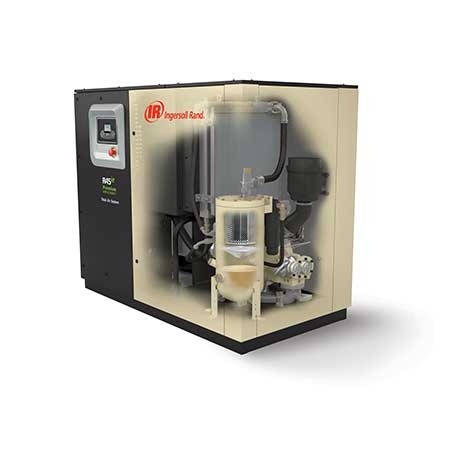
Ingersoll Rand occupies that space between a modest-looking component and an expensive interruption. It sells compressors, vacuum pumps, blowers, precision pumps and life sciences equipment. Its customers include factories, food producers, pharmaceutical manufacturers and wastewater operators. They need the right flow, pressure and purity, repeatedly. The interesting product is dependable production.
The invoice is the opening act
Consider the purchasing decision. Two machines may meet the same pressure specification, yet consume different amounts of electricity over thousands of operating hours. Atlas Copco, a compressor competitor, puts electrical energy at roughly 80% of compressor-related expenses. The precise split depends on the installation. The implication is plain: comparing purchase prices alone can produce an impressively tidy mistake.
This is the problem Ingersoll Rand’s service businesses address. CompAir, one of its brands, offers air audits that examine an installation’s performance. Equipment, treatment, controls and distribution belong in the same conversation. A machine can be sound while the system around it wastes money. Buying more capacity before checking leaks can mean paying to manufacture more escaping air.
Electricity’s approximate share of compressor-related expenses
For the supplier, this creates a relationship with a long tail. Machines need replacement parts, maintenance and eventual upgrades. Some applications consume components as part of normal production. Ingersoll Rand sells through direct operations and distributors, combining specialised equipment with people who understand its use. That application knowledge matters when a customer’s production schedule is on the line.
An old name with a new family tree
The name suggests a straight line through industrial history. The corporate structure tells a more complicated story. Simon Ingersoll patented his rock drill in 1871. It mechanised work previously done by striking a steel rod with a hammer. Another lineage, Gardner Governor, reaches back to 1859. Over time, machinery businesses accumulated inventions, customers and other machinery businesses.
Today’s group took shape in 2020, when Gardner Denver combined with the industrial segment of the former Ingersoll Rand. The combined business adopted the Ingersoll Rand name; the climate business became Trane Technologies. That distinction matters. A familiar logo can survive a substantial change in what sits behind it.
The portfolio now spans more than 80 brands. Familiar names include Gardner Denver and CompAir in compression, Nash in vacuum, and ARO and Milton Roy in fluid handling. The competitive argument is breadth plus technical fit and service reach. Atlas Copco offers a substantial alternative. Buyers still have to compare the actual application; a large catalogue does not settle an engineering decision.
The scale is substantial: Ingersoll Rand reported $7.6509 billion in revenue for 2025. That figure combines equipment and the activity surrounding it across the group. Its opportunity rests on improving familiar processes and extending its reach into applications where precision and reliability command attention. For a buyer, the useful question remains specific: which supplier understands this process well enough to keep it working?
Give the people fixing it a stake
There is another integration problem hiding inside all those brands: how do employees of acquired businesses come to care about the same company? In September 2020, Ingersoll Rand announced a $150 million equity grant for nearly 16,000 employees. Gardner Denver had made a broad employee grant when it returned to public markets in 2017.
“We think and act like owners.”Ingersoll Rand core value
Ownership language becomes more consequential when there is ownership attached. It gives the person improving a process a financial interest in the result. It does not establish that every subsequent improvement came from the grant. But it makes the company’s cultural proposition unusually concrete: employees participate in value they help create.
The operating counterpart is Ingersoll Rand Execution Excellence, or IRX. The company describes it as simple processes supporting execution through self-directed work teams. The lesson to borrow is the combination: give people a stake, then give them a practical way to affect performance. An equity award by itself does not identify a faulty process.
The $2.325 billion turn
In June 2024, Ingersoll Rand closed its acquisition of ILC Dover, announced at approximately $2.325 billion in upfront cash. ILC brought single-use powder and liquid handling, containment and medical-device components. At announcement, roughly 75% of its revenue came from consumables, like-for-like replacement or recurring streams. The attraction extended beyond selling another durable machine.
Then the assumptions moved. In 2025, the acquired Biopharma and Aerospace & Defense reporting units recorded goodwill impairments. Biopharma’s reflected higher discount rates and lower market multiples. Aerospace & Defense’s reflected a reduced long-term forecast tied to less business with a significant customer. These were non-cash accounting charges. They still punctured the comfort of the original valuation.
What gave way was confidence in particular forecasts and valuation inputs. That is a useful distinction for anyone copying an acquisition strategy. A recurring sale still needs a customer; a forecast remains exposed to decisions outside the buyer’s control.
Start with the hiss
The practical takeaway begins with measurement. Establish demand, operating hours, required pressure and air quality. Check the system before ordering more equipment. Compare lifetime cost and service availability. Savings depend on the duty cycle and the starting condition; a lightly used installation will not repay an efficiency premium like one running continuously.
Ingersoll Rand is still investing in that calculation. Its May 2026 partnership with Garrett Motion targets oil-free compression, with a broader rollout planned for 2027. For food and life sciences customers, air purity joins energy and reliability in the specification. The humble compressor room turns out to contain a remarkably large purchasing decision.