A business operating in 122 countries had a perfectly reasonable explanation for one of its markets. The region was mature. Competitors were plentiful. Growth would be modest. Ian Picache said the argument made sense. Then his team counted the customers.
The arrival of new customers was accelerating. Two Six Capital, the analytics firm Picache co-founded, reached a different conclusion about the region's prospects. In a 2019 talk, he reported that the region had subsequently grown 100 percent. The apparently tired market had become an engine of the business.
There is an appealing lack of theatre in the mechanism: record when a customer arrives, then examine the pattern. No secret handshake required. The episode offers a way into Picache's career, which has moved between buying stakes in businesses, building businesses, and building tools to understand them. A persuasive account of a company is useful. A way to test it is more useful still.
The investor takes a turn behind the counter
Picache began his career in Morgan Stanley's private equity and investment banking groups. He went on to spend more than a decade investing through Technology Crossover Ventures, Vanguard Ventures and TeleSoft Partners. His education brought together a Dartmouth bachelor's degree in engineering and economics and an MBA from Wharton, where he graduated in 2001.
That combination places two questions beside each other: what is something worth, and how does it work? His later businesses would keep those questions in close company. Investment analysis requires assumptions about a company's future. Operating a company supplies a brisk education in what happens when those assumptions encounter customers, employees and a deadline.
One such education came through Bergine, a luxury local flash-sale business he co-founded with his wife, Patricia Calfee. The idea arose during a Napa Valley weekend. They spent weeks working through business models, recruited a sales team through introductions, and funded the venture themselves. It launched in San Francisco and Napa Valley in March 2010, then expanded to Los Angeles in June.
Calfee described a division of labour in which she supplied the why and Ian supplied the how. Their founding employees all received equity. Advisors had encouraged a more mainstream approach; the founders stayed with the luxury segment. Gilt Groupe acquired the business seven months after launch, and Bergine became Gilt City in October 2010.
Afterward, the pair wrote down 50 lessons for their next venture. The subjects ranged from customer acquisition costs to selecting a lawyer. An exit may look tidy in a career biography. A list that includes legal housekeeping has the less glamorous advantage of sounding like an actual business.
Two classmates, one unfinished calculation
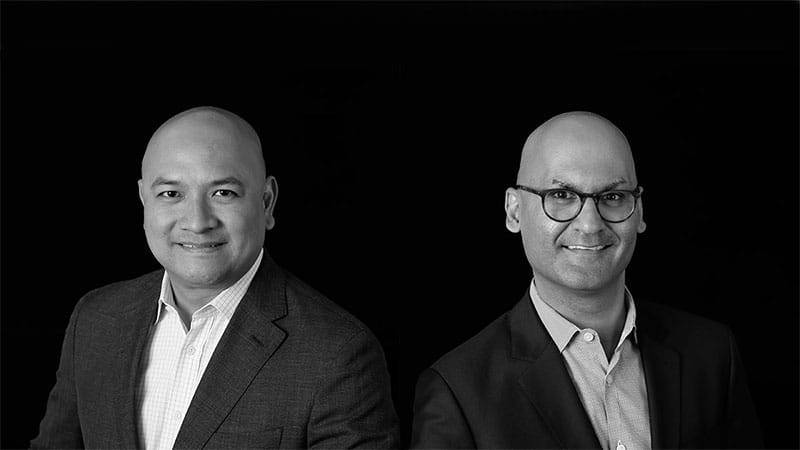
Picache and Sajjad Jaffer were Wharton MBA classmates who stayed in touch after graduating. In 2013 they founded Two Six Capital. The name came from the birth date of Picache's first child, a small domestic detail tucked inside an enterprise concerned with very large transactions.
Their partnership also supplied Picache with a joke: “We're both bald, and we met at the same barbershop.” The documented connection was business school. The barbershop line was his way of having a little fun with the origin story.
Jaffer had been looking to academic research for an investment advantage. Work by Wharton professors Peter Fader and Eric Bradlow on customer lifetime value caught his attention. He brought it to Picache, whose investing experience had repeatedly involved businesses where the economics of a customer mattered. They began assembling a team through their Wharton connections.
The practical attraction was straightforward. Historical purchases could help investors understand customer behaviour and estimate future value. A company could be examined through its customers, products and sales channels, bringing the marketing department's information into the financial discussion. The professors' work offered the founders a basis for analysis; the founders built a commercial application around it.
By 2015, seven of Two Six's 11 full-time employees were Wharton alumni. The team also included a Penn astrophysicist. It was an unusual collection of people for a private equity assignment, though an industry asking for help with vast quantities of data could hardly complain about someone accustomed to a large universe.
The forecast has to survive the meeting
Two Six's work extended from evaluating a potential acquisition to helping improve a business after investment and preparing it for sale. Its method used historical customer, product and channel records to examine performance and identify places where managers could act. The attraction was continuity: the analysis used to assess a purchase could remain useful after the deal closed.
Consider the everyday questions inside that approach. Which customers return? Which products earn repeat purchases? Which channels bring in customers worth keeping? An overall revenue figure can conceal very different answers. A growing business may contain a struggling product, while an unremarkable total may conceal a promising group of customers.
By 2018, Picache was describing data as a matter for the boardroom. He connected the firm's work to resource allocation across marketing, sales, support, budgeting, research and operations. The scope explains why his career is difficult to file neatly under either investor or operator. The investment question leads directly to decisions about running the company.
“We see big data as a board room agenda.”Ian Picache, 2018
He also described the kinds of businesses suited to the method: substantial data and repeat buying behaviour, often at least 10,000 customers or 500 products. Those were working criteria he discussed at the time, rather than a promise that every company with a database could produce useful predictions. The underlying business still mattered.
In a co-authored 2018 essay, Picache and Jaffer argued that data science could change how deal teams and operating teams worked together. Their interest went beyond a more elaborate valuation spreadsheet. They wanted analysis to inform entry valuations, improvements during ownership and the timing of an exit. The proposal put technical work alongside financial judgement throughout the investment process.
That is an organisational proposition as much as a mathematical one. A model can be examined, corrected and run again. A management team must decide whether to use its findings. The gap between understanding something and changing what happens next is where an operating business keeps its appointment book.
A sale, then a seat inside the firm
West Monroe acquired Two Six Capital in 2020, with the transaction closing on November 30. Picache and Jaffer joined as senior directors, and the Two Six team joined the consulting firm's San Francisco office. The platform became part of West Monroe's Intellio suite through Intellio Predict, designed to help project business drivers and support investment decisions.
At the acquisition, West Monroe described a platform with more than $160 billion worth of data accumulated across diligence and value-creation work. That number measures the underlying data, not assets Picache owned or capital he personally managed. It gives a sense of the material the team had worked through.
Worth of data accumulated by the Two Six platform across its work. A data measure, not personal wealth or fund assets.
Picache said the buyer's presence and private equity relationships offered a way to scale the business. He also joined West Monroe Capital's investment committee, continuing the connection between advisory work and co-investment. Selling the company did not conclude his involvement in the questions it had been built to answer.
In 2021 he joined Roark Capital as managing director and chief analytics officer. The role placed him inside a consumer-focused private equity firm, responsible for data and analytics used in investing and portfolio operations. He subsequently scaled its data and analytics department. The practical setting had changed: an external specialist became part of the institution making the decisions.
By October 2024, Wharton's Venture Lab was inviting students to an ask-me-anything session with him about investing and analytics careers. The invitation brought the university connection around again. The graduate who had built a company with a classmate was returning with experience on both sides of an acquisition and inside a private equity firm.
Atomic, and the question that remains human
Picache now identifies himself as co-chairman and co-founder of AtomicPE. The company's proposition expands the subject from analysing customer transactions to understanding how a business operates. Its description of an AI-native platform centres on creating a digital twin of a business and supporting strategic plans and corporate transformations.
The phrase digital twin describes an ambition to represent the business in a form that can be examined. For a reader following Picache's earlier work, the connection is clear enough: understand the activity beneath the summary, then use that understanding to make decisions. The technology and scope have changed. The question about what actually happens inside a company remains familiar.
Atomic's website makes room for human responsibility in a short line: “Connection and judgment are human. Automate the rest.” It is a useful statement of intent because the work Picache has described over the years has always ended with people deciding where to put resources. Analysis supplies evidence. Someone still has to choose.
He is listed to speak at the San Francisco Data and AI Summit on October 29, 2026, with the agenda placing him in a session on AI and alternative data across the private equity deal cycle. The setting suits the route he has taken: investing, operating, customer analytics, then a broader attempt to model the business itself.
Return to the apparently mature region. The memorable part of that episode is the willingness to test an explanation that already sounded sensible. A convincing story can bring a meeting to an agreeable close. Picache's career keeps opening the underlying records, where the customers may have a less convenient ending in mind.