Howard Scott Silverman and Seth Deutsch met at the Art Institute of Chicago, away from the main crowd. Both had found their way to the edge of the room. Years later, discussing the encounter, Silverman made networking sound less like collecting contacts than finding one person worth talking to. It is a modest beginning for a friendship, and a useful place to begin understanding an investor whose work depends on partnerships that last.
Silverman, Agman’s founder and CEO, uses the word “investrepreneur” for his occupation. The word asks quite a lot of the reader’s tongue. The businesses make it easier to understand. His investing world includes restaurant operations, insurance companies and real estate: places where a promising idea eventually has to become a functioning organization.
The question running through that work is duration. An entrepreneur can find an investor who likes the business and still disagree with that investor about its future. A few years of ownership and a few decades of ownership invite different decisions. Silverman has arranged his firm around the longer conversation.
A doctorate, then a different set of questions
His education began in Chicago at the Latin School, where he finished first in his class. Dartmouth followed. He graduated with High Honors and Phi Beta Kappa recognition, studying biochemistry and molecular biology. At Oxford, a Keasbey Memorial Scholarship supported graduate work that culminated in a doctorate. The academic credentials were substantial; the eventual occupation was considerably harder to put on a school prospectus.
His early professional stops included Boston Consulting Group, Oxford Bioscience Partners and Atlas Venture. Consulting and venture investing put him close to the decisions that turn an idea into a business. They also introduced a different sort of uncertainty. A plan can be coherent on paper and still require a customer, a team and enough money to survive its first revisions.
That progression makes his later work more interesting than a simple return to a family profession. He had acquired experience outside the family’s investing activities before developing his own approach within them. A scientific education, consulting assignments and venture work are different apprenticeships. Each involves deciding which questions deserve attention before committing resources to an answer.
There is an appealing untidiness to the route. We like a career to proceed as though the ending were printed on the first page. Silverman’s résumé has several chapters before Agman. Read backward, they form a plausible preparation. Read forward, they are a sequence of choices about what kind of work he wanted to do.
The calendar is part of the deal
Silverman describes himself as a fourth-generation investor, with family roots in Omaha. His own CEO role at Agman dates to 2005. The firm traces its earlier origins to a one-person insurance business in 1923. Those dates describe two different beginnings: a family’s investing history and the investment organization he helped shape.
His transition toward Agman overlapped the financial crisis. “My timing was impeccable,” he joked. The dry line is more convincing than a polished origin myth. It allows a difficult moment to remain difficult, without pretending that a long investment horizon comes with a reliable forecast of next Tuesday.
Agman’s capital is permanent. Its stated approach allows both controlling and minority investments, with room to operate across different parts of a company’s financing. That flexibility means Silverman can consider several ways of entering a business relationship rather than making every opportunity fit one transaction.
“The best investors think and act like founders.”
H. Scott Silverman
The calendar has consequences even before any money changes hands. A founder considering a factory, a software system or a management hire has to know how long the partner expects to remain. Some improvements arrive slowly. Some expenses become useful only after a business reaches a different scale. Ownership expectations influence which of those decisions seem sensible.
Long ownership also raises the standard for choosing a partner. If the relationship is expected to continue, a disagreement cannot always be solved by waiting for a sale. Judgment and operating responsibility become daily concerns. The attractive part of the arrangement is time; the demanding part is what two people agree to do with it.
A sequence of responsibilities, rather than a timetable for a guaranteed return.
A hotel, a relationship, a decade
Real estate gives that idea physical form. Agman’s platform includes acquisition, development, asset management and property management. Its investment interests range from residential buildings to hospitality, offices, retail and industrial properties, with an emphasis on secondary markets in the United States. Buying the property is one event inside a much longer operating story.
Consider the connection with Jasin Alfaro. Silverman first worked with him on the acquisition and redevelopment of the historic Chicago Athletic Association Hotel. In April 2024, when Metonic appointed Alfaro CEO, Silverman welcomed him as a co-founder and board member who had known the incoming leader for more than a decade.
The appointment gives the phrase “long-term relationship” an actual history. A hotel project introduced two people. Years of familiarity preceded a later leadership decision. For an investor, knowing someone through a complex project is a different kind of evidence from knowing someone through a presentation. The work leaves a record of how people behave when the plan meets reality.
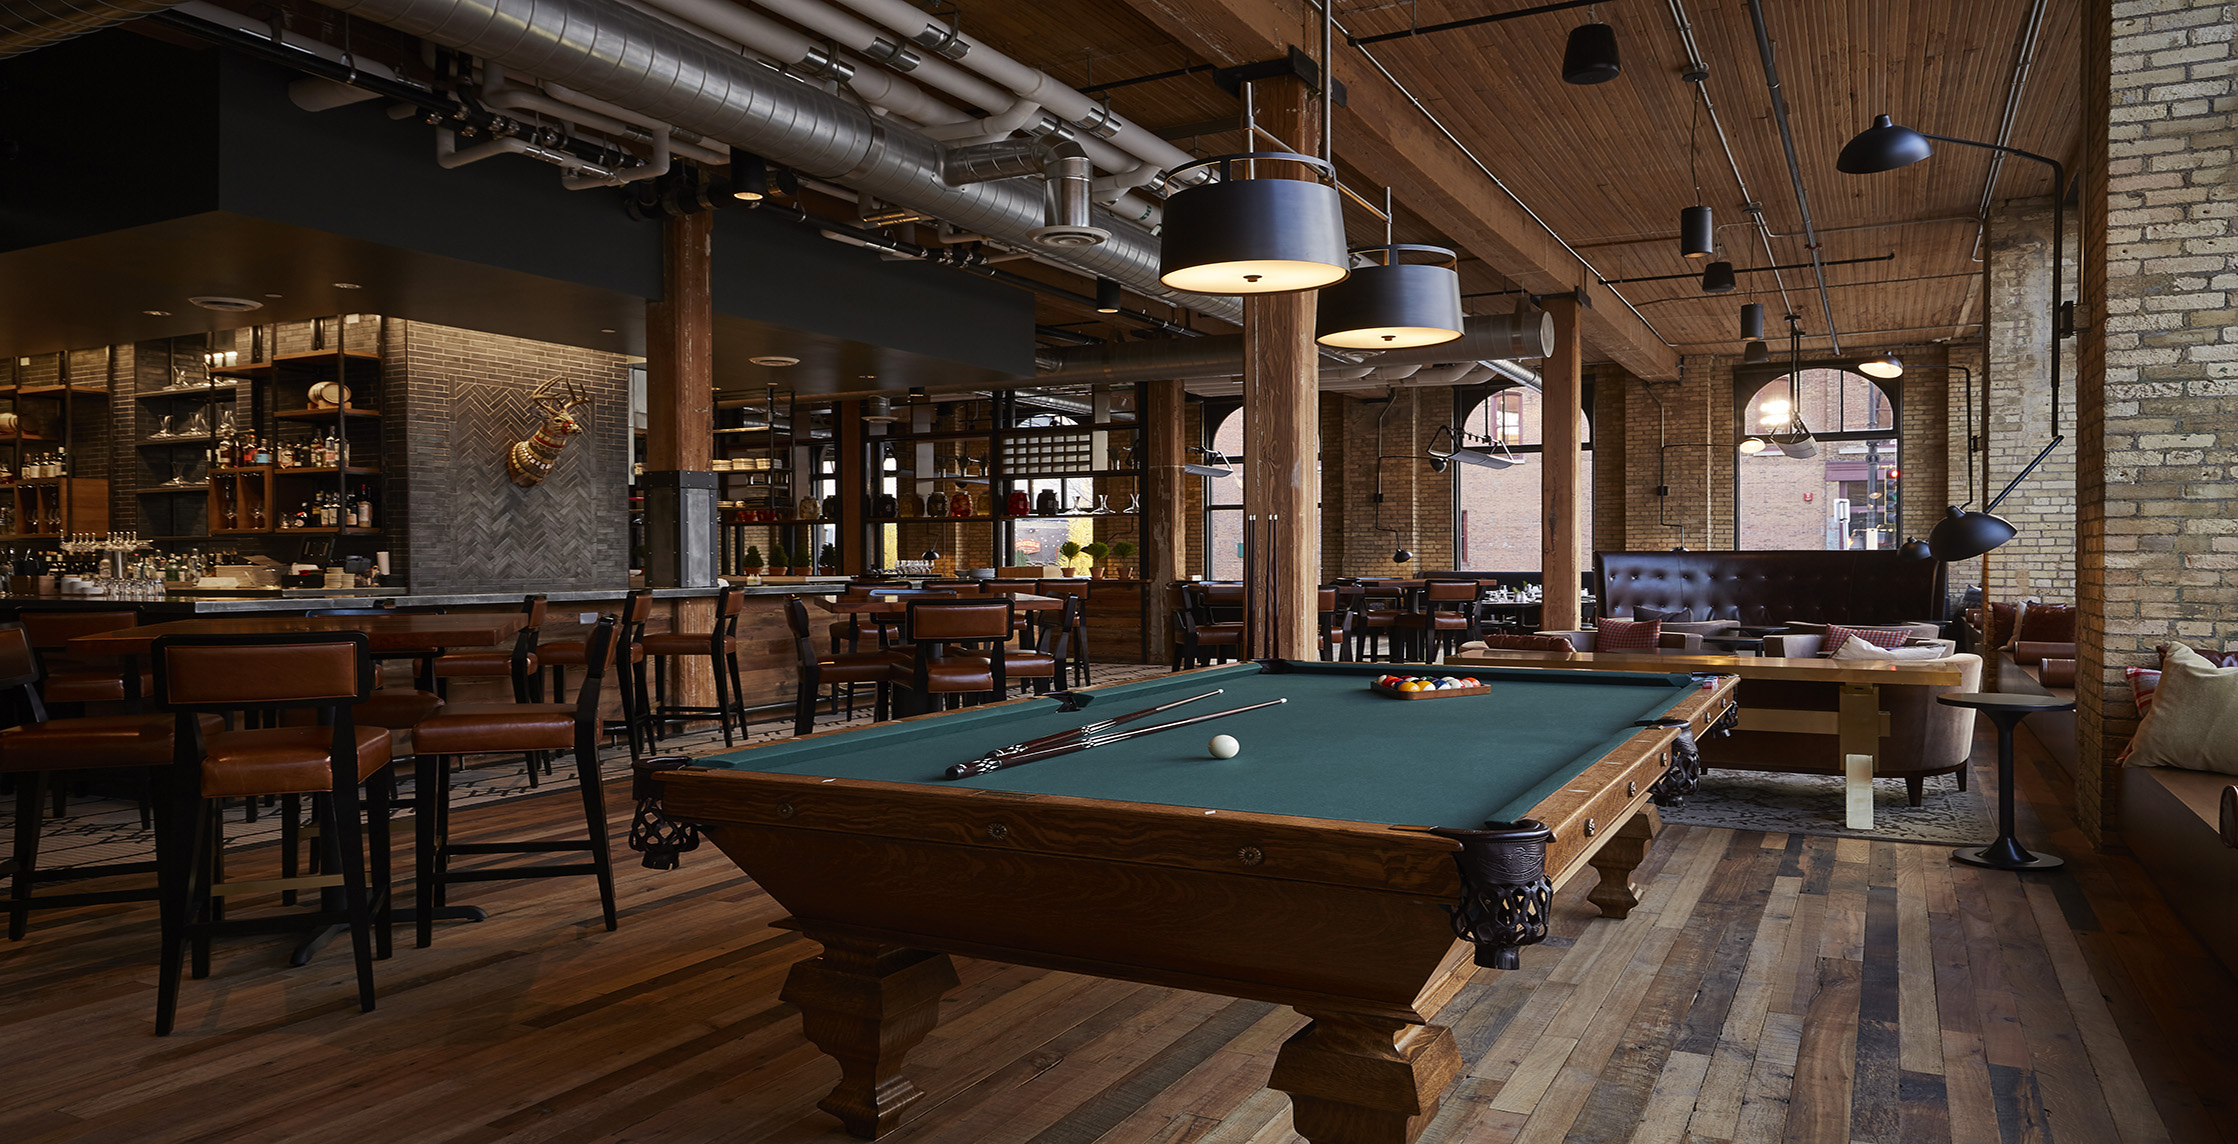
Metonic’s April 2024 announcement put its portfolio at more than $1 billion in assets under management across over 80 properties. Those are company figures, tied to that moment. The personal detail is Silverman’s role in a partnership that had enough history to make a new appointment feel familiar. Buildings may be the assets; relationships help determine who will look after them.
Three ways into insurance
The insurance holdings show how several businesses in one industry can have different jobs. Virtus is a brokerage. Omaha National is an insurance company. Aurenity is a managing general agent, an underwriting business working with insurance capacity partners. Treating them as interchangeable would miss much of what Silverman and his colleagues are building.
Omaha National began in 2016. In September 2021 it raised $45 million in a Series B round led by Accomplice, with HighSage Ventures and Tull Investments also participating. Agman remained its principal and founding investor. The money supported the company’s move toward issuing policies on its own paper and further developing proprietary software.
The announcement illustrates a practical feature of founding capital: a company’s needs change. The organization that helps a business begin may later invest alongside other firms. A longer ownership horizon can accommodate new partners and a more elaborate operation. The relationship continues while the business acquires tools it did not need, or could not support, at the start.
Seed investment from Agman to launch the underwriting business.
Aurenity followed in 2022, launched with $10 million from Agman. Nick Davies, who had joined Agman as an operating partner in 2021, became CEO. Patrick Safino joined as chief operating officer. The initial focus was casualty and professional liability in the excess and surplus insurance market, with analytics supporting pricing and underwriting decisions.
“Agman is built around backing entrepreneurs,” Silverman said at the launch. It is a short explanation of an arrangement that requires several kinds of expertise. Capital can finance recruitment and technology. Underwriters still have to decide which risks make sense. A useful partnership preserves that distinction while making the specialist’s work possible.
The work behind staying
Agman’s portfolio also includes Ampler, the restaurant platform associated with brands such as Taco Bell, Burger King and Little Caesars. Its news page recorded a 500-unit milestone in September 2025. Restaurants bring a different set of operating demands from underwriting or property development, even when the investor’s preferred horizon remains similar.
A restaurant has to open for the next shift. An underwriting operation has to evaluate the next submission. A building has to be maintained between transactions. These are ordinary descriptions of work, but they explain why the operator occupies such a large place in Silverman’s investment approach. The person allocating capital and the person making the daily decisions have related responsibilities, with different points of view.
Agman’s own team reflects that need for more than investment selection. Alongside investment professionals and operating partners sit financial, legal and accounting roles. Erica Wessel is chief financial officer; Anna Simpson is general counsel. The structure puts the less glamorous machinery of ownership in view. A company can survive without an elegant slogan. Its obligations require considerably more attention.
A new partner, with the old one still there
In September 2026, Aurenity secured a strategic investment from Great Hill Partners. Agman and Aurenity’s management retained significant equity stakes. The planned uses included recruiting underwriters, launching programs and expanding the technology supporting the business. Financial terms were undisclosed.
By then, Aurenity had six core excess and surplus programs. The new investor joined a company with an operating history, rather than simply a launch proposal. For Silverman, the transaction carried the original partnership into another stage. It is a useful recent example of what staying can look like: ownership changes around a business without requiring its founding investor to disappear.
There is no need to turn that into a fable about patience always winning. Businesses still have to earn their place with customers, employees and partners. Silverman’s career offers a narrower, more concrete proposition. Capital has a duration, and that duration affects the relationships it can support. At Agman, the invitation is to build something together and leave enough room on the calendar to keep working.