A mortgage broker's screen can resemble air-traffic control, except every blinking object wants a password. There is the borrower application, the pricing engine, the loan-origination system, the document portal, the e-signature service, the lender's own portal, the customer relationship manager and, somewhere beneath them all, the actual customer. Harish Tejwani looked at this procession of tabs and saw a software architecture problem.
His answer is ARIVE, the San Ramon platform he leads as founder and chief executive. It combines loan origination, point of sale, pricing, documents, a compact CRM and a marketplace of wholesale lenders. The proposition is less glamorous than a flying car and rather more useful: give independent mortgage professionals one place to compare, communicate, collect, submit and keep moving.
Tejwani arrived at that proposition by a route measured in decades, not pitch decks. He graduated from IIT Roorkee in 1998 with an engineering degree in electronics and communication. His software career ran through Hughes Software Systems, Nagarro, SAP Labs and the Mexican retailer OXXO. The recurring work was architecture, performance and the patient business of making complicated systems behave.
POS · CRM · docs
loan file
marketplace
The engineer notices the seams
A small episode from 2008 offers a useful miniature. At an SAP developer challenge, Tejwani joined a cross-company team tasked with combining several technology themes. The group quickly chose a carpooling application because one product could pull those themes together. It was a prototype, not a prophecy. Still, the instinct is recognizable: find the scattered pieces, then build the joining layer.
By 2011, Tejwani had founded Wizni. Its lending software eventually operated under the LendWize name, connecting products, pricing and origination. The mortgage industry supplied no shortage of seams. Independent brokers had the freedom to shop across lenders, but that freedom came with administrative tribute: repeat the data, reconcile the systems, remember which portal held which answer.
Today's broker market is heavily fragmented.Harish Tejwani, 2021
In early 2020, Wizni took over management of ARIVE, an existing broker-software platform. It replaced the original system with technology developed through years of research and relaunched the product late that year. Around the turn of 2021, Wizni completed the acquisition. Tejwani did not merely bolt his company's tools onto someone else's brand. The team rebuilt the working surface.
The timing was severe. Mortgage volume surged during the pandemic, while broker teams were already coping with a thicket of rules and portals. Yet the new version drew more than 1,000 broker sign-ups within roughly six months. By the end of the third quarter of 2021, more than 2,000 broker shops representing over 8,000 originators had signed up. HousingWire named Tejwani a Tech Trendsetter that year.
- 1998Graduates from IIT Roorkee and begins a career in software.
- 2011Founds Wizni, later home to the LendWize lending platform.
- 2020-21Rebuilds, relaunches and acquires ARIVE.
- 2023Appears on the Mortgage Global 100.
- 2025ARIVE reports 4,200 paid customers and 27,000 users.
The marketplace lives inside the work
ARIVE's cleverest choice is where it places the marketplace. A broker does not browse lenders in one product and then restart the loan in another. Pricing and lender access sit inside the origination workflow. The application is already there. So are the documents, tasks and conversations. A moment of comparison can become a moment of action without forcing the broker to reintroduce the loan to the internet.
That arrangement creates a compact flywheel. More brokers make ARIVE a useful place for lenders to show up. More lender integrations make ARIVE a useful place for brokers to work. The system of record keeps both sides close to an active transaction. Network effects, a phrase often dressed for dinner, turn up here wearing sensible shoes.
In April 2025, ARIVE said it had 4,200 paid customers and roughly 27,000 users, including about 20,000 loan officers. It was adding around 100 customers a month, each commonly bringing a team of five to ten officers. Those figures arrived while the broader market had shed roughly 30,000 originators from the prior year. The useful fact is not simply that ARIVE grew. It grew while its users' profession was being asked to do more with less.
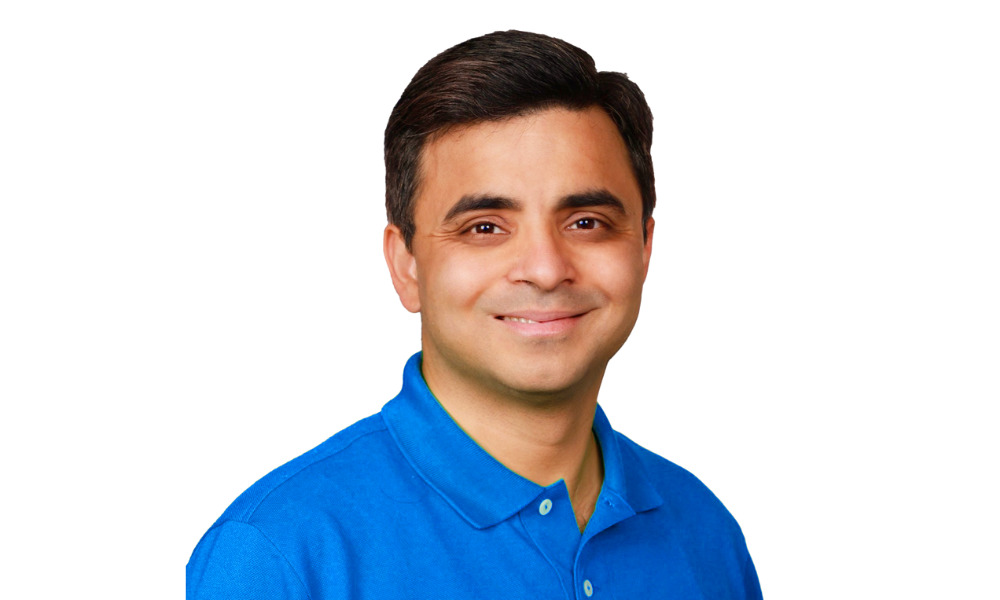
Tejwani's public explanation is stubbornly close to the user. The system is simple, he says, because it is geared toward loan officers. Its roadmap is driven by feedback. Users say what they need; the team acts. ARIVE's relationship with the Association of Independent Mortgage Experts gives the company regular contact through events, discussions and the broker community around them.
Our platform is driven by feedback. Our users tell us what to do, and we do that.Harish Tejwani, 2025
This sounds obvious until one considers how many enterprise products treat users as witnesses to a roadmap already decided. Tejwani describes something closer to a standing editorial meeting. The community supplies the field notes. ARIVE turns recurring complaints into product work. Feedback is not decoration on strategy; it is the raw material.
A roadmap made of next actions
One 2025 project made that philosophy literal: autonomous task management. Tejwani described software that would guide a loan officer, processor and team through what comes next, who is responsible, how much time remains and when a delayed task deserves an alert. Artificial intelligence appears in ARIVE's technology stack, but the ambition is not a fog of omniscience. It is a better queue.
The product roadmap is expanding alongside the lender network. Through 2025 and into 2026, ARIVE continued announcing integrations across conventional, government, non-QM and investor lending. Each agreement adds choice, but also another set of products, pricing and workflows that must feel coherent inside the platform. A marketplace is easy to enlarge on a slide. Keeping it navigable is engineering.
That prank supplies a rare glimpse of the company's playful side. Mortgage origination is consequential work. It is also filled with small absurdities familiar to anyone who has typed the same fact into three systems. Humor becomes a form of product empathy: yes, the workflow occasionally makes a person want to scream; no, the microphone should not underwrite the house.
The medal comes with a door
Tejwani's connection to engineering now loops back to Roorkee. He established a corpus for two annual Class of '98 Tejwani Gold Medals, one for an outstanding final-year project in computer science and one in electronics and communication engineering. Eligible students need strong academic records and projects judged for innovation, technical depth and impact.
The interesting flourish comes after the ceremony. Recipients also receive confirmed placement offers at ARIVE India and joining bonuses. A medal looks backward at work completed; a job opens forward. Tejwani paired the two, turning alumni recognition into a small talent bridge between the institution that trained him and the company he built.
It also fits the larger pattern. His career is full of joins: software to lending, origination to pricing, brokers to lenders, classroom projects to first jobs. The joins are not glamorous by themselves. Their value appears in motion - a loan that proceeds, a customer who gets an answer, a graduate who has somewhere to apply an idea.
Independence, with better instruments
Tejwani's stated aspiration for ARIVE has remained consistent since the acquisition: build a large marketplace for lenders and brokers, then give brokers the efficiency to stay close to clients and real-estate partners. The company also emphasizes its own independence. Wizni is privately held, majority owned by Tejwani with employees and strategic advisers, and says it has no outside investment or lender control.
That ownership matters because ARIVE sits at a sensitive junction. Brokers compare lenders there. Borrower information moves through it. A platform promising choice must persuade users that the marketplace is not quietly choosing for them. Tejwani has addressed the question directly, spelling out that lender partners do not own or control Wizni and that broker pipeline data is not broadcast across the marketplace.
The deeper product wager is modest enough to be credible. Mortgages will remain complicated. Guidelines will branch. Disclosures will reproduce after dark. Interest rates will refuse to become a personality anyone enjoys. ARIVE does not need to abolish complexity. It needs to arrange it so a broker can see the next useful action.
That is Tejwani's work in one line: respect the independence, reduce the friction. The broker keeps the choice. The software carries more of the choreography. And the customer, ideally, gets more of the person on the other side of the screen.