The costly moment in a mortgage is not always when something goes wrong. It is when everyone finally notices. A lien, a judgment, an ownership mismatch or a solar assessment can sit quietly while a lender gathers documents, a title company opens an order and a borrower imagines the keys. Then the title work arrives and the file stops cold. Flueid, an Austin software company founded in 2017, has built its business around a blunt operational idea: ask the title questions before the transaction becomes emotionally and financially expensive.
Its phrase for this is Verification of Title, or VOT. The flagship Flueid Decision platform pulls property and consumer information, applies rules approved by title underwriters, and returns a TitleCheck or TitleDecision. The result is not merely another PDF for the closing folder. It is intended to tell a lender, servicer or title provider what to do next: fast-track the routine file, investigate an alert, assign an experienced examiner or stop spending money on a loan unlikely to close.
The product is triage, not speed
Flueid talks about five-day home-equity closings and ten-day refinances. Those are enticing numbers, but they are better understood as workflow goals than warranties. The more useful thing the software does is separate files. A clear transaction can take a shorter path. A messy one receives attention while there is still time to cure it. Automation here does not mean pretending every property is clean; it means reserving human judgment for the records that refuse to behave.
That distinction also answers what failed first in the old process: timing. Traditional title work usually began after a mortgage or real-estate workflow was already moving. Flueid did not invent public records or underwriting rules. It changed when their implications become visible. In a 2023 Encompass integration announcement, the company said an early check could help a lender avoid roughly $1,500 in resources on a file that would later fall out. The figure is Flueid's estimate, and the actual economics will vary by lender, channel and complexity. The reusable lesson is sturdier than the exact dollar amount: bad news gets cheaper when it arrives earlier.
“The earlier title data and intelligence is accessible to lenders, the better for perfecting their pipelines.”Peter Richter, co-founder and president
Four engines and a lot of scar tissue
Flueid may be nine years old, but its founders' title-software apprenticeship began decades earlier. Peter Bowman and Peter Richter say their team built an early online property-research application in 1995, later developed tools for Move, Inc., and created ClosingPoint, a transaction-management platform. In 2009, they co-founded Title365, a national title agency that became a laboratory for cloud, mobile, signing and search technology. Nationstar Mortgage, now Mr. Cooper, acquired it in 2015.
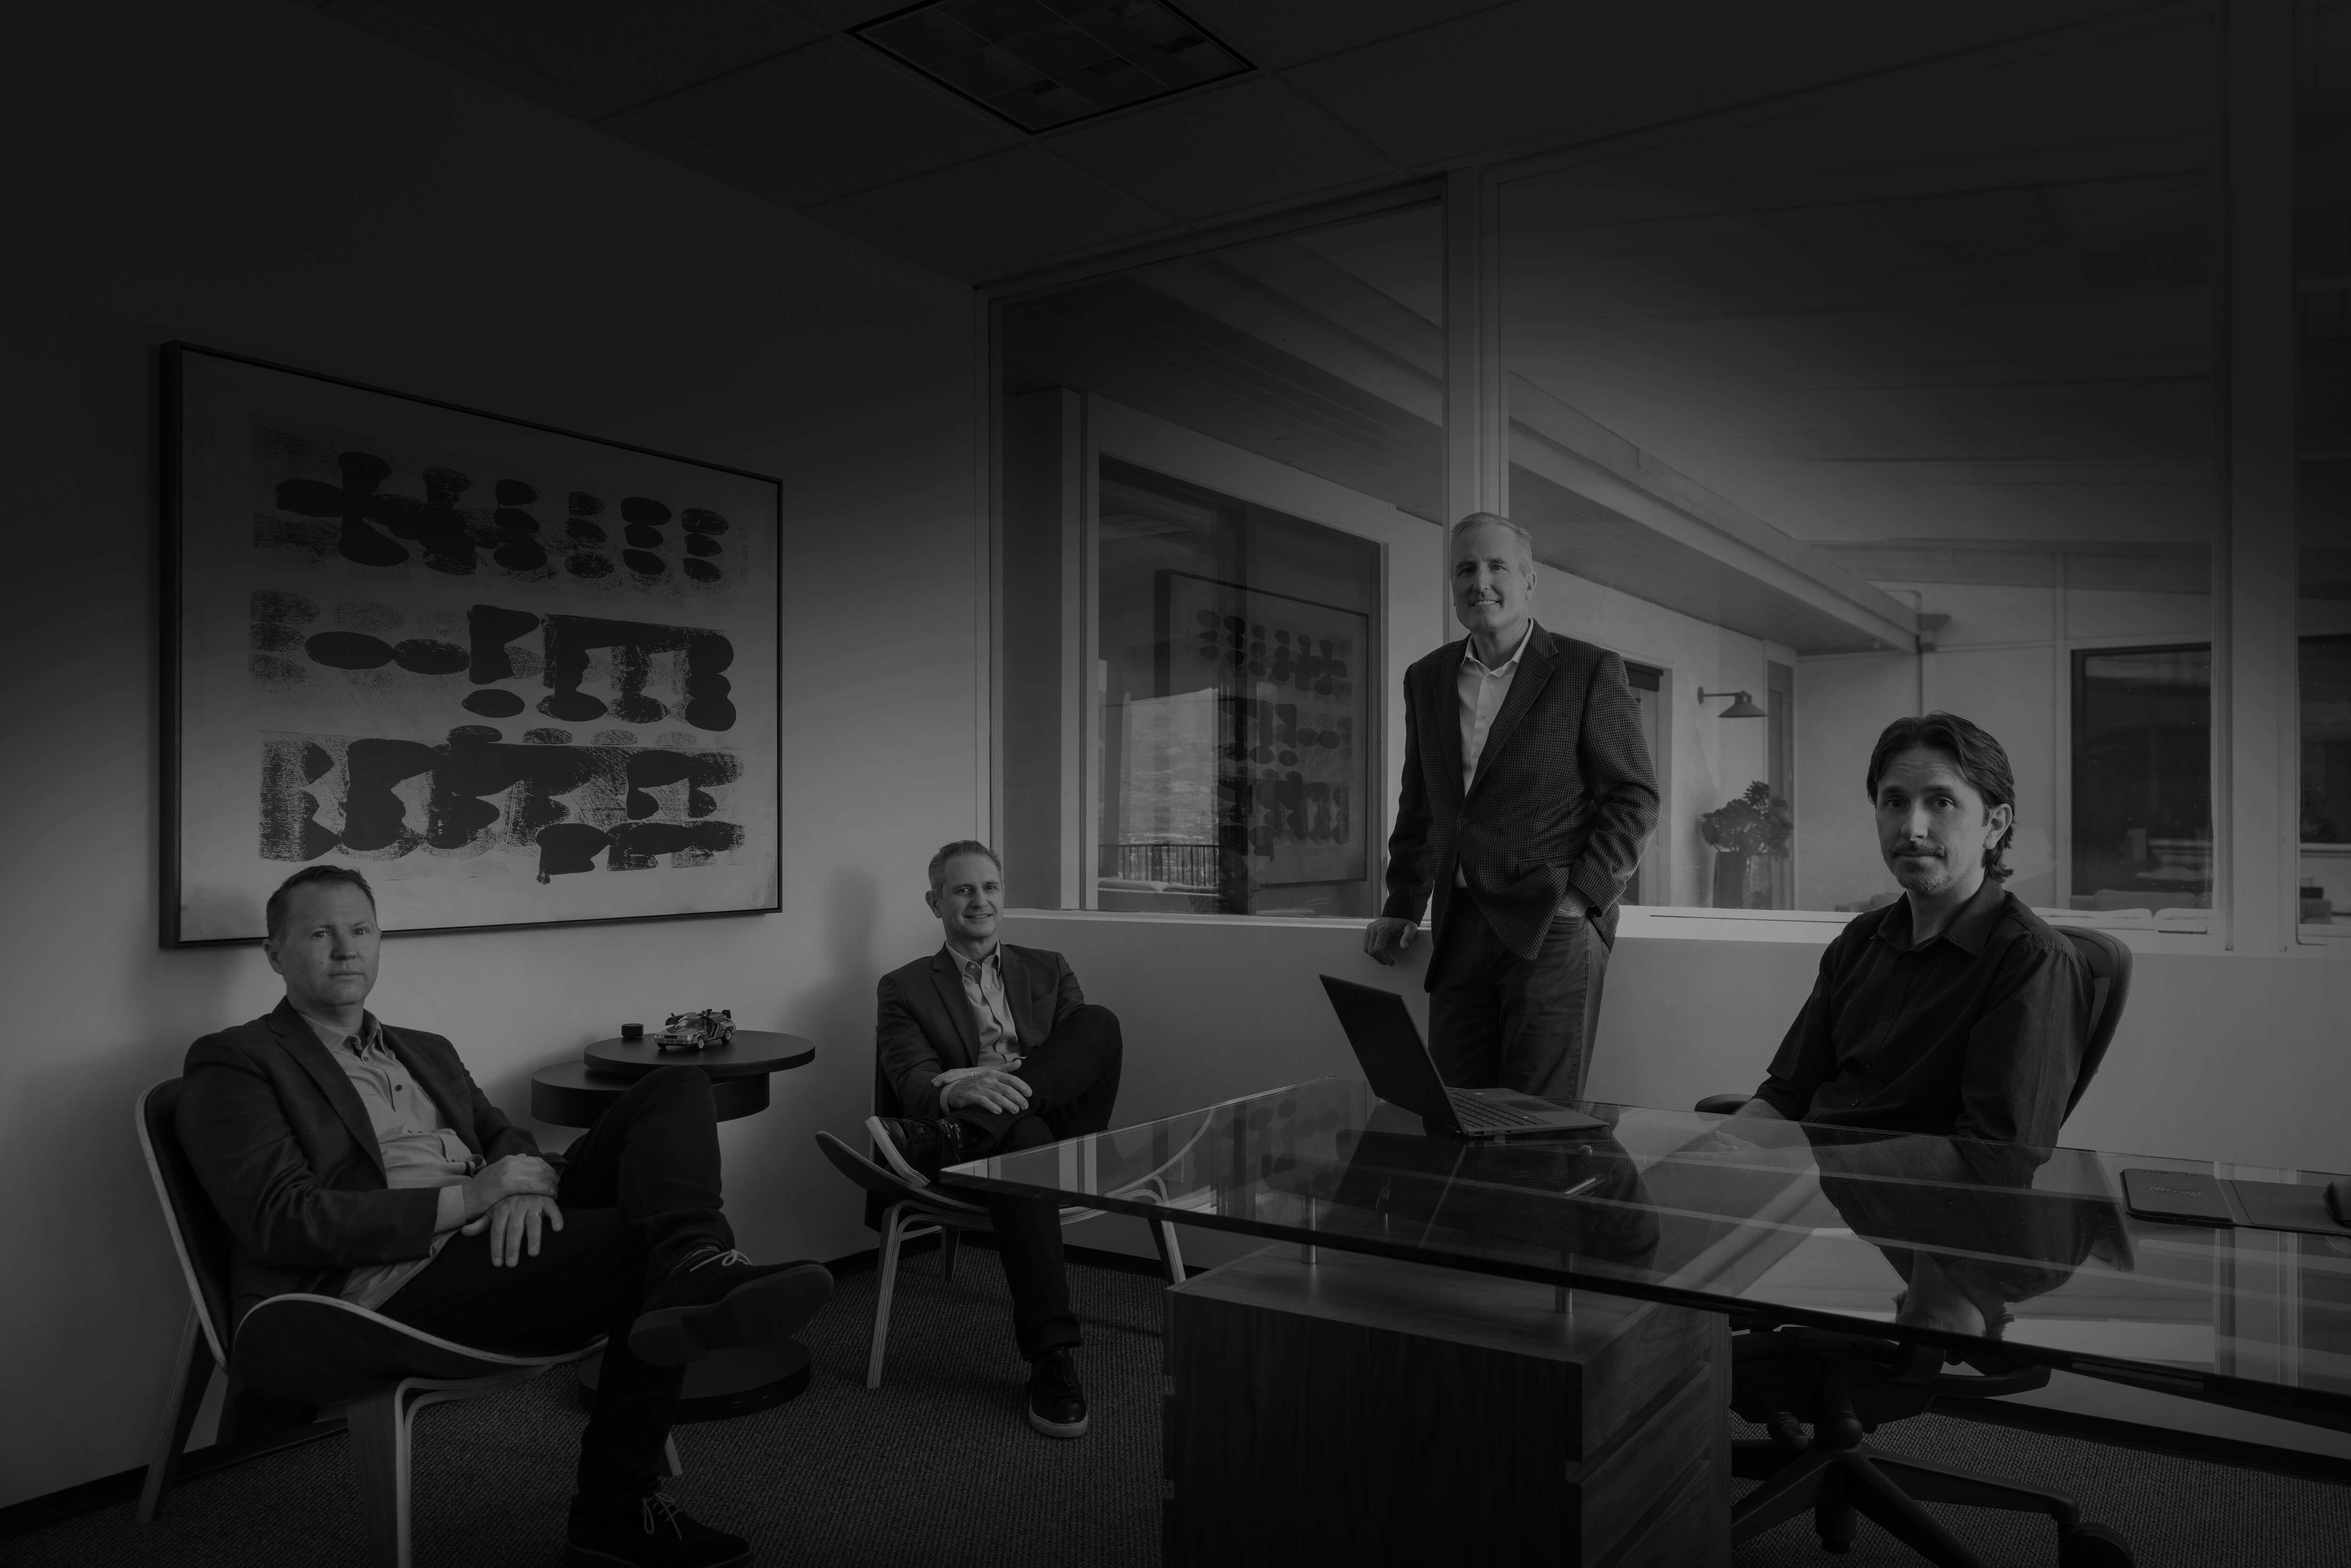
Bowman and Richter founded Flueid with chief architect Dennis Frandsen in the technical inner circle. They self-funded the early work while building what the company calls the team's fourth title decision engine. That history matters because title is not a generic data-cleaning exercise. County records differ. Underwriting guidelines differ. Exceptions compound. A model that generates a confident answer without respecting those rules is not helpful; it is a new risk.
Flueid's answer is a multi-tenant platform with client-specific rules and dedicated cloud environments. The company received U.S. Patent 11,095,756 in 2021 and a continuation patent in 2022. It completed SOC 2 Type I and Type II work, uses order-level encryption and says it does not monetize consumer data with third parties. In a market where a title file contains sensitive financial and identity information, security is part of the product, not the page after the product.
A refinance tool learns to survive the cycle
Flueid Decision launched in 2020 around refinance. That was excellent timing until it wasn't. Mortgage markets punish products tied to a single transaction type, so the company spent the next four years broadening the engine: home equity in 2022; loss mitigation and loan modification in 2023; purchase in 2024. The change of mind was not a public retreat from refinance. It was a recognition that one strong workflow still leaves a company exposed to rates and volume.
The purchase product shows how early Flueid wants to go. A real-estate agent can request a TitleCheck around listing, and a participating title provider can work toward a “Close Certified” property before an offer is accepted. Sellers get time to address an old lien or ownership issue. Buyers receive fewer late surprises. First National Title Insurance Company became an early adopter across purchase, refinance and home equity, using Title Data's Texas title plants where state rules require the underlying evidence.
Distribution is deliberately unromantic. Flueid integrates into systems customers already use: Encompass for mortgage origination, FirstClose for home equity, and title-production platforms including SoftPro and Resware. Flueid Transact moves decisions, data and documents among systems of record. Flueid Built adds managed title production. The company is not asking a lender to throw out its operating system. It is trying to insert one consequential answer at the point where that system can act on it.
Move the diagnostic upstream. Split routine work from exceptions. Put the answer inside the tool people already use. Preserve evidence so a specialist can inspect it. This pattern travels well beyond title - into fraud review, compliance, claims and any process where late discovery is more expensive than early uncertainty.
Who pays, who benefits, and where it breaks
Flueid is a business-to-business software company. Title underwriters and agents, mortgage lenders and servicers, and fintech or proptech platforms buy the enterprise tools. Public company databases describe a mix of enterprise licenses and usage pricing, while Flueid does not publish a standard rate card. Flueid Pro has subscription access and in-app credits for selected owner contact data. Consumers usually do not buy Flueid directly; they experience it as a faster, more legible process run by someone else.
The product suite now stretches from finding a possible transaction to closing it. Flueid Pro, rebuilt in 2025, combines nationwide property and ownership data, “farm” creation for prospecting, turnover probability, equity insights, maps, recorded documents and mobile notes. A service-ordering module connects that research to title, settlement and VOT orders. Flueid Decision performs the risk triage. Transact carries the result. Built supplies managed operations where software alone is not enough.
That breadth also defines the competitive position. Property-data companies can supply records. Title-production systems can run the file. Digital title agencies can bundle insurance and closing. Flueid's wedge is narrower: an independent, underwriter-agnostic decision layer that can sit among them. Its advantage depends on data coverage, acceptance by insurers and integrations that make a decision usable. If any one of those is weak, the elegant diagram turns back into email and manual review.
There are firm limits. Public records can be incomplete or slow. Ownership disputes, unusual liens, probate, jurisdiction-specific rules and underwriting exceptions do not vanish because a report arrived in under a minute. A fast-path model works best when a meaningful share of files is routine, data is sufficiently current, and the organization is willing to change staffing and routing around the output. It works poorly when every decision must still be repeated by hand, or when users mistake “clear” for an unconditional guarantee.
The clever part is not making every title file automatic. It is discovering which files deserve not to be.
The capital behind the category bet
Flueid partnered with Aquiline in 2020, raised a Series A with Aquiline and Commerce Ventures in 2021, then secured $15 million in Series B equity plus a $5 million Silicon Valley Bank relationship extension in 2022. Another $10 million Series B extension followed in 2023. In October 2024, LiveOak Ventures led $8.3 million in growth financing, joined by Detroit Venture Partners and the existing investors. Public databases disagree on total capital because they count debt, extensions and undisclosed rounds differently; the cleanest number is the latest disclosed raise.
The 2024 money was earmarked for product development, growth and go-to-market work. Two months later, Flueid moved former Zillow and First American executive Cheryl Baillis from its board into the chief revenue officer role. In October 2025, it unveiled the rebuilt Pro and previewed AI-supported marketing actions. That sequence is revealing: fund the category, hire for distribution, then widen the front door of the product.
Flueid says technology architected by its team has processed more than 5.8 million transactions, while the current Decision platform has supported more than 387,000. Those figures are not the same thing, and the smaller number is more useful for judging the present product. The company is still trying to turn VOT from its own acronym into an industry checkpoint. The outcome will hinge less on whether title can be automated in theory than on whether lenders and title companies reorganize real work around an early answer.
That is the practical takeaway. Do not begin with a grand promise to transform an entire transaction. Find the expensive surprise. Move its diagnosis forward. Give the routine majority a clean path and the complicated minority a visible queue. Then integrate the decision where somebody can use it. Flueid's subject happens to be title insurance, a business famous for courthouse records and exceptions. The operating idea is much larger - and pleasantly free of magic.
Go down the title rabbit hole
Performance figures in this profile are company-reported and describe targeted or observed workflows, not guaranteed closing times or savings for every transaction.