A mortgage has an odd rhythm. There is the excitement of choosing a home, then the quiet business of proving things: income, assets, ownership, the answer to one more question. A borrower sees a purchase. A loan officer sees a file that must keep moving. Groves Capital has built its pitch around that second view. Find a suitable lender, certainly. Then deal with the little requests that stand between an application and a completed transaction.
- A mortgage broker and lender serving homebuyers, homeowners and property investors.
- A network that gives loan officers lender access and shared operating support.
- A technology arm, Groves IQ, aimed at document follow-up and client communication.
01A family business with two front doors
Aleyna and Christoffer Groves are the husband-and-wife founders. She is the chief operating officer; he is the chief executive. Their older company biography dates the start to 2016, while corporate filing information and LinkedIn point to 2017. The useful distinction is between an origin story and a corporation. The business they describe has always combined lending experience with a particular ambition: give originators more room to run their own practice.
That creates two customers. One wants financing. The other wants the infrastructure to arrange it. Groves Capital’s partner site describes a privately owned company offering remote work, lender relationships and shared support. Its account of the founders’ motivation is blunt: bank originators worked hard without enough compensation or control. The response was a platform where loan officers could operate with greater independence.
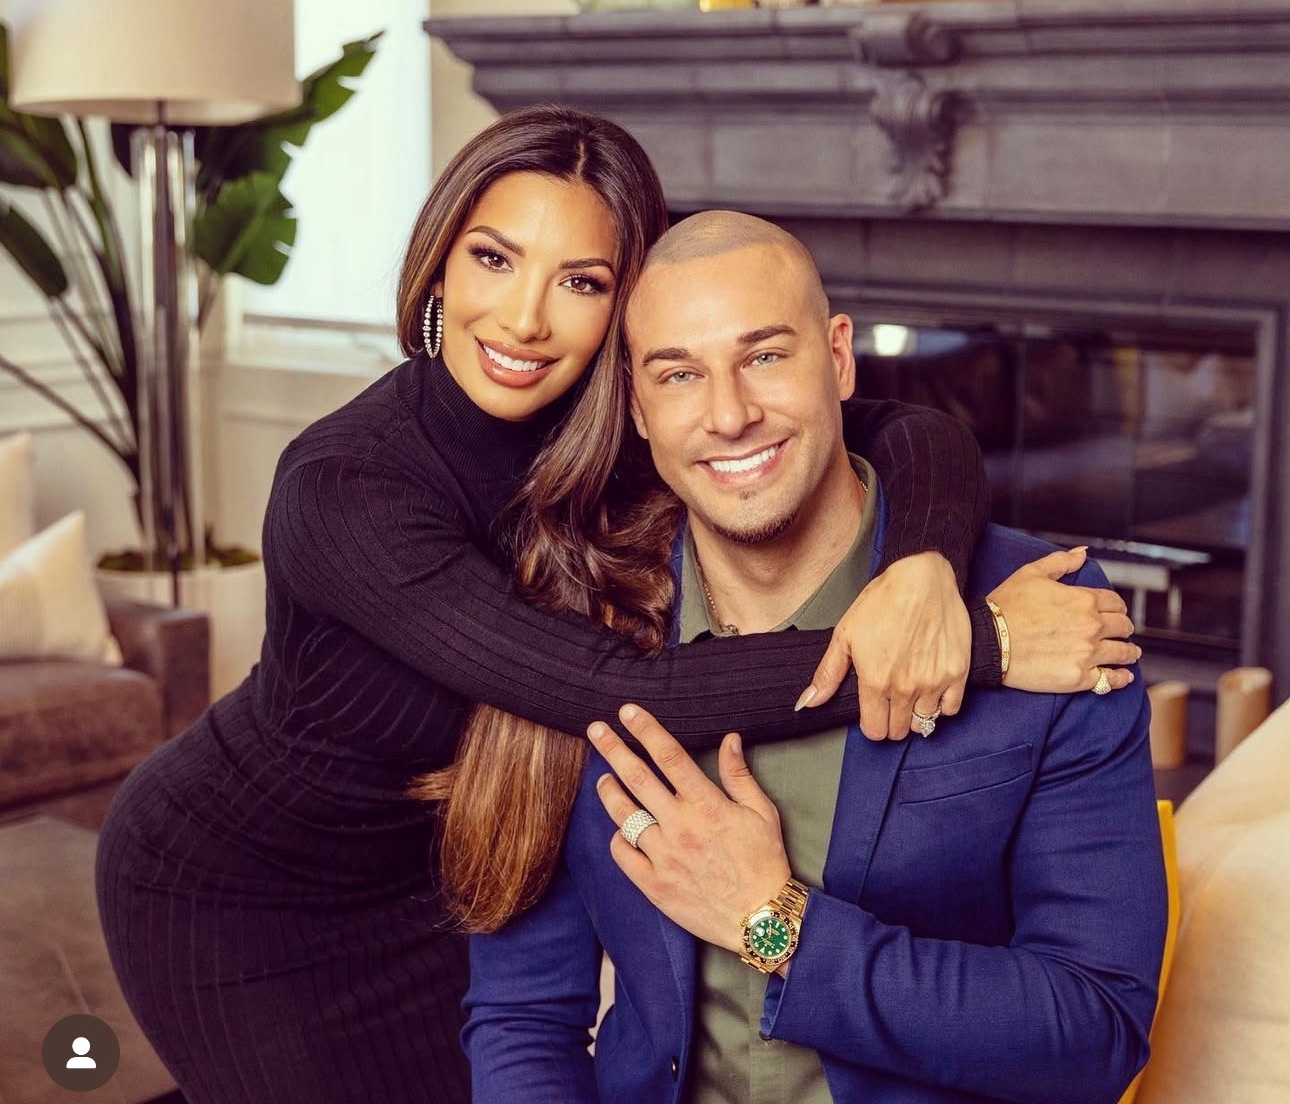
The company’s language is familial, but its operating question is practical. How much can one originator do alone? A broker must understand products, maintain relationships, manage a pipeline and keep clients informed. Sharing the machinery offers a way to preserve a small business’s personal service while spreading some of the administrative burden.
02The menu is only half the meal
For borrowers, the offer starts with choice. Groves Capital lists conventional, FHA, VA and jumbo mortgages alongside financing for investors and self-employed applicants. Its bank-statement programs examine deposits; its DSCR offerings focus on investment-property cash flow. Those are different approaches to different borrowers. A business owner and a salaried employee may need very different conversations about the same house.
The company also advertises equity products, construction financing, bridge loans and commercial mortgages. This breadth puts it in the space between a borrower’s specific circumstances and a lender’s specific requirements. The alternative might be a bank, another brokerage or a different loan officer with access to wholesale lenders. A large menu alone does not establish better pricing. Someone still has to match the file to the product.
in funded loans, according to its about page.
Loan volume measures financing arranged. It does not measure the company’s revenue.
The same page reports more than 500 brokers and more than 160 lender approvals. Those figures describe the network Groves Capital says it has assembled. They also explain the coordination problem: more relationships can produce more options, and more processes to navigate. Making a selection is one task. Keeping everyone informed after that selection is another.
03Mortgage Mommy clocks in
Groves IQ is the company’s technology arm. Aleyna leads it as CEO, with Christoffer as chief revenue officer. On LinkedIn, Groves Capital says it built the tools to address its own bottlenecks, including chasing conditions. That word deserves attention. Conditions are the outstanding requirements a file needs resolved. Software aimed there has a more concrete assignment than the broad promise of an AI-powered mortgage.
“Broker First”
A published Groves Capital core value
The product names add some domestic comedy. Mortgage Mommy handles processing support; Deal Daddy handles sales follow-up. Behind the jokes are document requests, borrower updates and lead nurturing. The company describes connections with LendingPad and UWM, while its broker tools also include Lender Price. The design principle is recognizable: connect the work around existing mortgage systems.
Those published prices give a broker something to examine. The sensible comparison is with the tasks the business needs performed, the tools it already pays for and the volume it can support. A subscription earns its place when it removes enough repetitive work. A quiet pipeline and a busy pipeline will produce different answers.
04A bigger loan changes the problem
Groves Capital’s ambitions extend beyond home loans. In March 2024, it announced commercial expansion into domestic and international markets, naming developments, hotels, condominiums and multifamily projects. It described relationships with family offices and funds as part of that strategy. This was an announcement of direction; it should be read as such.
The same announcement identified sponsor liquidity and continued investment commitment as concerns. That detail is more revealing than the expansion language. Sending an update cannot supply missing capital. Commercial projects add questions about counterparties and funding that require judgment, relationships and negotiated terms. The software can help organize the work surrounding those decisions.
05Borrow the question
There is a useful lesson here for businesses outside mortgages. Start with a recurring task people already dislike. Ask what information it needs, who owns the next action and where the result belongs. Then decide which parts can be automated. Groves Capital’s stated experience with conditions offers a specific example of that approach, without requiring every business to build a technology arm.
It works best when file information is accurate, integrations function and someone handles exceptions. Licensed professionals and lender requirements remain central to the transaction. For a borrower, the practical attraction is a human adviser with more options and a clearer process. For a broker, it is the possibility of spending less of the day asking where things stand.