A bank can fit inside a phone and still feel a long way away. There is the download, the registration, the unfamiliar menu, the form that wants information in precisely the right shape. Gordon Peters’s work begins with a less ceremonial entrance: a conversation in a messaging app. The customer already knows where to type. The bank must learn how to listen.
Peters is the co-founder and CEO of Boost Capital, a Singapore-headquartered financial technology company with roots in Cambodia. With co-founder Lucinda Revell, he built a business that helps financial institutions bring customers through their digital application processes. Its early proposition was disarmingly plain: let people apply through Facebook Messenger, Telegram or WhatsApp, without first asking them to install another app.
That choice gives his career a useful point of entry. Peters has worked on the large machinery of finance, including mergers and acquisitions in banking and microfinance. At Boost, the machinery has to work for someone holding a smartphone. A transaction can be beautifully arranged at the institutional level and still stumble when a customer reaches the first question.
Before the chatbot, there were the bank deals
Peters studied economics at the University of Virginia from 1996 to 2000 and began his career at Bain & Company. His subsequent working life moved through technology businesses and emerging markets. There were regional expansion responsibilities at Digital Divide Data in Cambodia, business development roles, and a venture of his own in social media advertising.
He co-founded SocialCash, an advertising network on Facebook and Twitter that was acquired by LifeStreet Media. Long before Boost, then, he had worked with businesses built around the places people gathered online. The commercial purpose was different, but the distribution question would return: when an audience already has a destination, what should a business do to reach it?
From 2009 to 2015, Peters was managing director of Emerging Markets Consulting. He expanded the consultancy’s operations across Cambodia, Myanmar, Vietnam, Thailand, Indonesia, the Philippines and Singapore. He later became a partner at Mekong Strategic Partners, where his work included banking and microfinance M&A across Southeast Asia. Those roles placed him on the institutional side of a region’s financial development.
His professional record also includes a board role at 17 Triggers and a listed Khmer language capability. These are small details beside a CEO title, but they give the biography texture: consulting, consumer behaviour, local language, finance. Boost sits at an intersection of those subjects. Explaining an application clearly and assessing it properly require different kinds of expertise, and both have to survive contact with the same customer.
- 2000Bain & Company
Consulting - 2007SocialCash
Co-founder - 2009Emerging Markets Consulting
Managing director - 2016Mekong Strategic Partners
Banking & microfinance deals - TodayBoost Capital
Co-founder & CEO
A familiar window, an unfamiliar opportunity
Boost was founded by Peters and Revell in 2018. Its chat-based approach addressed a practical mismatch: customers were comfortable with informal messaging channels, while financial institutions needed structured information and checks. The company put an application process into that familiar setting. A chat window could become a place to ask questions, submit documents and move towards a financial service.
The charm of the idea is that it asks technology to accommodate a habit. Much digital design starts by teaching the customer a new routine. Here, the routine already existed. The demanding work happened behind it, where a bank’s requirements had to be translated into a sequence someone could complete. Familiarity was the opening; the application still had to make sense.
In Cambodia, that mattered particularly for small business owners. A visit to a branch competes with the hours needed to run a business. Boost’s model brought the process to a smartphone and allowed business income to help support applications where collateral could be a barrier. Convenience, in this setting, has consequences beyond saving a few taps.
In August 2022, Peters met UNCDF executive secretary Preeti Sinha during her Cambodia visit. The figures discussed were concrete: 96,000 micro, small and medium enterprises registered on Boost’s platform, including 68,000 led by women. Working with financial institutions, the team had helped disburse $1.7 million in loans to MSME owners over the preceding year.
Snapshot: August 2022. Registrations and lending are separate measures.
The distinction between registration and lending matters. An open door is useful; what happens after someone walks through it deserves its own accounting. These numbers describe different stages of the process. They also put a human scale on Peters’s work without pretending that every application ends with a loan.
Two founders, two customers to satisfy
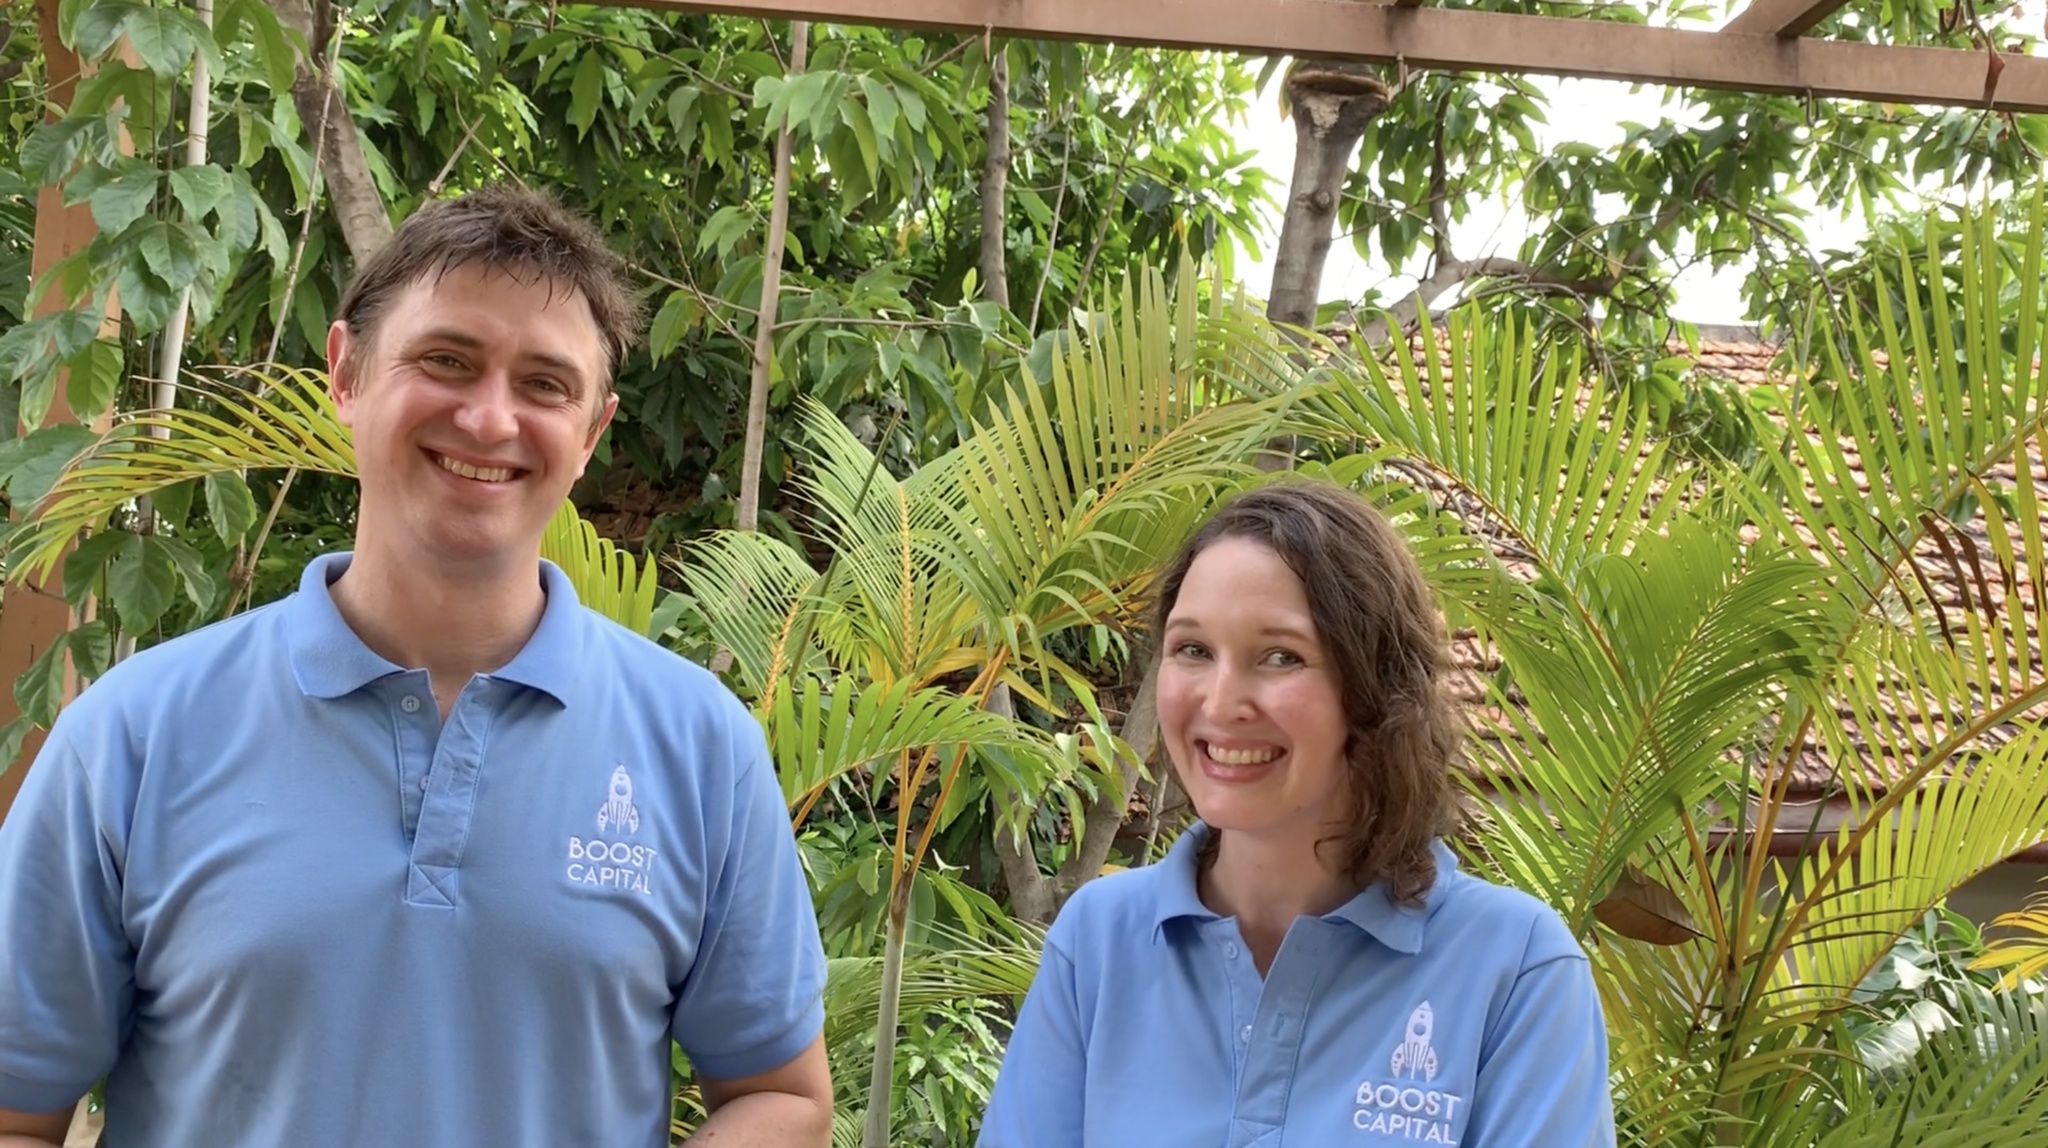
A photograph of Peters and Revell shows the co-founders in matching blue Boost polo shirts, standing among palms. It is a more relaxed picture than the usual financial services portrait. The business underneath it, however, carries a demanding arrangement: the applicant needs an intelligible experience, and the institution paying for the software needs results it can use.
Revell has described Boost as a business-to-business-to-consumer company. In a 2024 interview, she explained that it works on banks’ behalf to onboard applicants while serving the applicants themselves. That makes customer experience part of the product’s commercial logic. A pleasing conversation that cannot produce a usable file has failed the bank; a perfect file nobody can finish assembling has failed the customer.
She also described different market priorities, including salary lending in Cambodia and SME products in the Philippines. Regional expansion therefore involves more than replacing one country name with another. The same interface may sit in front of different products, evidence and customer needs. Peters’s earlier regional work gives that expansion a recognisable place in his career, rather than making it appear as a sudden new ambition.
Boost’s aim to concentrate on selected partners in each market also gives the story a particular shape. This is a company selling capabilities to financial institutions. Its success depends partly on what those partners can achieve with the technology, and on how well the founders understand each institution’s priorities.
Competition, sold as software
Peters’s explanation of Boost is especially revealing when he talks about competition between banks. In 2024, he pointed to the opportunity for more institutions to obtain the technological advantages already enjoyed by banks with strong internal teams. Software offered a way to spread those capabilities more widely.
“There are banks that have good tech talent and good tech products.”Gordon Peters, 2024
The sentence is modest, almost deliberately so. He acknowledges the institutions already doing the work well. His argument opens space for the others. Instead of requiring every lender to build a complete digital onboarding operation for itself, Boost offers a service those lenders can use. The competitive question becomes what they do with access to it.
In August 2023, Boost announced a $2.5 million seed round involving Village Global, Iterative Ventures, Hustle Fund, Epic Angels, Xcel Next and Insitor, alongside angel investors. The stated uses included market expansion, a larger product team and new bank partnerships. Investment here funded the work of extending a system and supporting the institutions using it.
Among the participating angels were Remitly co-founder Shivaas Gulati, former Intel CFO Larry Hootnick and former Wells Fargo venture capital executive Puon Penn. Village Global separately described its investment and Boost’s expansion plans in Cambodia, the Philippines and Indonesia. These connections put the founders in networks spanning technology, finance and regional development. They are backing and relationships, rather than a substitute for execution.
One partnership made that integration question explicit. At the start of 2024, Peters and Oradian co-founder Antonio Separovic considered combining Boost’s chat technology with Oradian’s Instafin core banking platform. The resulting offering connected digital onboarding with the institution’s existing back-end infrastructure. For Peters, the useful connection ran in both directions: towards the familiar channel on the customer’s phone and towards the systems the financial institution already operated. The customer could keep a familiar habit, while the lender could keep working inside its established infrastructure.
The paperwork behind the conversation
By 2025, Peters’s public discussions were reaching further into AI. At the Asia Financial Institutions Forum in Bangkok, he spoke about validating identities and incomes at a scale difficult to achieve through manual review alone. He also emphasised training systems on local market data. For a business operating across countries, local knowledge belongs inside the technology as well as around the negotiating table.
At a Financial Alliance for Women discussion, he addressed AI in customer service and onboarding while stressing the continuing role of people in the process. That is a useful complication in a subject often reduced to promises of automation. Financial institutions and customers can still need human involvement, particularly when serving people who have had limited access to formal finance.
Illustration of Boost’s current onboarding capabilities; individual deployments vary.
Boost’s current offering includes identity and business checks, document validation and integration with existing systems. The company describes turning unstructured documents into structured, validated information. The conversation remains visible to the applicant, but increasingly the product also works on the evidence behind that conversation. A friendly question is the beginning of a much less visible processing job.
In Bangkok, the question becomes trust
At Money20/20 Asia in April 2026, Peters joined a discussion on inclusive open finance with Hakan Eroglu of the BIS Innovation Hub, Rachel Freeman of Tyme and NetBank founder Gus Poston. Brankas CEO Todd Schweitzer moderated. Peters highlighted the difficulty of connecting to government data and the value of basic infrastructure for validating identity and company documents.
It was a continuation of the problem Boost had approached through chat. Getting information from a customer is one task. Establishing that the information can support a financial relationship is another. A document must become something an institution can check and act on. Better infrastructure can make that passage faster, but the need for confidence survives every improvement to the interface.
The public arc of Peters’s work runs from consulting and institutional finance to the small, consequential steps of an application. His stated goal is to expand access to digital financial services for people who are unbanked or underserved. That ambition has acquired a specific working vocabulary: chat, local data, document checks, bank partnerships.
There is an appealing lack of ceremony in the original idea. A customer sends a message. Behind it sits the accumulated difficulty of banking. Peters and his colleagues have made that boundary their business: the ordinary action on one side, the institutional demands on the other. The chat window is small. The work required to keep it useful has plenty of room to grow.