A shopper can forgive a crowded aisle. A coupon that works on the phone but vanishes at the till is harder to explain. Suddenly, the customer is refereeing a disagreement between two parts of the same retailer. Flooid makes software for that meeting point: the moment when a price, a promotion, a payment and a person have to agree.
The company supplies a unified commerce platform, a collection of shared services underneath staffed checkouts, self-scanners, mobile devices and digital shopping channels. Its customer references run from Waitrose and Walgreens to Hudson and Krispy Kreme. These are businesses where selling a product involves more than putting a payment button on a screen.
Flooid’s proposition is deliberately practical. Give different shopping interfaces access to common transaction logic, then let retailers change those interfaces as habits change. The shopper sees another way to buy. The retailer wants fewer versions of the truth to maintain. That is the commercial promise behind the software vocabulary.
Waitrose wanted the payment to disappear
Waitrose offers a useful way into the story. In Flooid’s case study, Matt Clifton of the John Lewis Partnership describes a checkout strategy built around choice. Customers could scan with a handset or their own phone; self-service sat alongside service from employees. The objective was to make the end of the shop easy enough that customers remembered the food.
“Customer habits are moving so fast you can’t afford to sit still.”Matt Clifton · John Lewis Partnership
The important engineering decision happened underneath. Waitrose and Flooid built a basket-pricing service that could be used by self-scan and ecommerce. The January 2020 rebrand announcement described connections spanning online shopping, mobile solutions and tills in 340 physical stores. That number belongs to the announcement, not today’s estate.
The lesson is specific: reuse the calculation before multiplying the ways customers reach it. A retailer evaluating this approach should ask a vendor to demonstrate the same promotion across several channels. A consistent answer matters more than a matching colour scheme.
Staffed till02
Self-scan03
Online shop
Different screens.
Prices · Promotions · Tax · Payments
A new screen should not mean a new rulebook
Flooid separates the services that do the work from the applications customers and employees use. A retailer can take Flooid’s interfaces, work with another application vendor or develop its own. The platform supports Google Cloud deployment and APIs for connecting other systems.
That arrangement matters because retail formats overlap. A grocery operation can include fuel, food service and conventional checkouts. Flooid’s grocery materials describe convertible lanes that switch between attended and self-checkout use, alongside cash and inventory functions. Existing equipment represents an investment worth considering before a replacement programme begins.
The freedom comes with a boundary. Flooid also publishes a reference architecture and encourages limiting technologies outside its supported stack. For a buyer, that means checking the proposed combination of devices, services and integrations. An open interface is a route to compatibility; it is not proof that every combination will behave equally well.
At Hudson, the new channel sold masks
Hudson’s problem was an ageing POS system that could not support the digital selling experiences it wanted. Its Flooid case study describes a modernisation covering 1,010 travel convenience and specialty stores. When the pandemic hit, the partners completed deployment across 2,000 points of sale five months ahead of schedule, according to that account.
Then came a particularly concrete test: personal protective equipment. Hudson reported introducing vending machines in 27 North American airports within three weeks. Shared processes for prices, ranges, promotions and taxes helped the retailer sell through a different kind of machine.
Hudson’s reported pandemic-era PPE vending rollout.
The initial weakness was the old system’s limited ability to support new ways of selling. The pandemic changed what needed selling, and quickly. This is a more revealing account of flexibility than a showroom full of terminals: existing commercial rules were useful in an unexpected setting.
The doughnut has a loyalty wallet
Krispy Kreme’s UK and Ireland project shows a different coordination problem. Flooid provided the store platform and a real-time rewards wallet within a programme involving Magento, Gene, HTK and Nodes. The work connected ecommerce, customer information, the loyalty application and in-store activity.
The useful detail is redemption. A store employee should not have to guess whether a benefit has already been used online. Connecting the reward wallet across channels gives that apparently small interaction a common record.
The case study also contains an unusually copyable spending rule. Marketing chief Emma Colquhoun described allocating 70 percent to proven activity, 20 percent to approved new initiatives and 10 percent to innovation. It is a reminder that a transformation programme needs money for experiments without treating the functioning business as expendable.
Self-service still needs a human
A checkout that lets the customer do the scanning still produces exceptions. An age-restricted item needs attention. A terminal goes offline. A transaction appears unusual. Flooid’s Empower application gives associates alerts and a live view of transactions through existing POS and mobile devices.
Employees can monitor activity, respond to requests and handle supported interventions remotely. The product also lets staff compare what they can see being scanned with the transaction feed. Its proposed benefits include fewer interruptions and better loss prevention; those are product aims, not a universal measured reduction in theft.
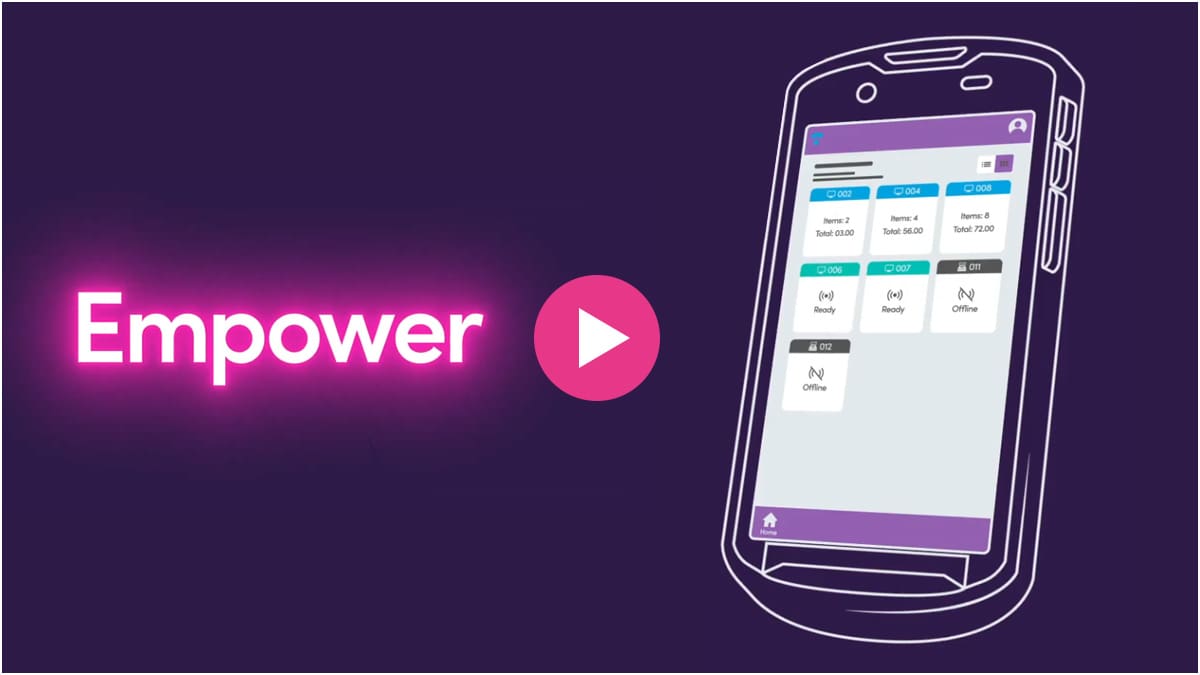
For retailers, the question is how quickly a signal becomes useful help. More alerts will not resolve a queue if nobody can act on them. An evaluation should include the staffing plan, permission settings and the customer experience of being interrupted.
Glory bought more than a till business
Flooid’s history helps explain its position. The PCMS business dates to 1982; the legal entity is older, incorporated in 1979 under the name Prestec Properties. In 2017, Inflexion backed a management buyout and succession from the departing founder. PCMS announced the Flooid brand in January 2020.
The company later explained that its old identity no longer represented the move from POS provider to a broader commerce platform. Houlihan Lokey, adviser on the subsequent sale, described substantial product investment and a transition to SaaS under Inflexion. The recurring software business became part of its appeal to a new owner.
Glory’s December 2023 filing put the announced acquisition price at £145 million, including net interest-bearing debt, plus £3.1 million in advisory fees. The figures were subject to adjustment. It reported Flooid Topco’s 2022 revenue at £45 million and operating loss at £5 million. The deal completed in January 2024.
For Glory, the stated logic was diversification beyond cash technology and expansion of recurring software revenue. Flooid gained access to a parent with international sales relationships. The strategic fit is understandable, but an acquisition price should not be mistaken for a retailer’s implementation budget.
Someone has to keep the shops trading
Flooid’s business model extends beyond a software subscription. It offers professional services, cloud infrastructure services and ongoing operational support. Managed services cover the platform, data flowing between cloud and stores, endpoint updates and monitoring. Its service desk operates around the clock, every day of the year.
These services address a different buying question from feature selection: who responds when a system needs attention? For a chain with many stores, the responsibilities between retailer, platform provider and integration partners are part of the product’s practical value. Buyers should compare support coverage and deployment work alongside subscription costs.
A retailer comparing proposals can separate the bill into software, integration, equipment, rollout and continuing support. The useful comparison is the cost of keeping the intended service running, including changes after launch. That matters especially when the pitch involves retaining existing systems: preserving a terminal may save a hardware purchase, while connecting it still requires work. This is a procurement lens for the project, rather than a claimed saving from Flooid.
Its employer materials describe hybrid working in Birmingham and Cincinnati, access to Udemy Business and development through colleagues and formal courses. One employee account describes moving from customer service into HR with qualification support. Such examples give the culture claims some texture, while remaining the company’s own presentation of working life.
The next argument is about the data
Flooid’s 2026 announcements broaden the story beyond the till. In May, the company said it had completed an integration with Planet’s omnichannel payments solution, extending a relationship already covering order management. The aim is to connect payment acceptance with stock visibility and fulfilment choices across channels.
In June, Flooid and Xiatech announced Insights Dashboards powered by Xfuze. The dashboards provide views for executives, regional managers, category teams and marketing, including store comparisons, bestsellers and discounts. The broader Insights offering includes connectors for retailers’ own data environments and a managed repository using Google BigQuery.
Later that month, Flooid announced work with efsta on fiscal compliance. The partnership addresses specialised requirements around transaction recording, receipts, archiving and invoicing. It illustrates why international retail software needs local expertise even when its selling logic is shared.
Flooid sits in an enterprise market with alternatives such as Oracle Retail Xstore and Toshiba Commerce software. Its case rests on experience in complex retail formats, shared services and a choice of applications and partners. Those characteristics give buyers a useful shortlist of questions; they do not establish that one vendor wins every deployment.
A sensible trial would take a real basket through a promotion, payment, return and staff intervention. Include existing hardware and the integrations the business actually uses. For a small operation with few channels, the coordination benefits may not justify an enterprise project. For a sprawling retailer, getting those everyday transactions to agree is a substantial ambition all by itself.