In 2015, a credit union in Little Rock did something software vendors love to hear about: it came back. TruService had used FLEX from 1988 to 2010. After several years away, it reviewed its core system and selected FLEX again. The interesting part is the explanation. Familiar service mattered, but so did the product’s progress: mobile check deposits, lending, accounting and documents working together.
- FLEX supplies the software behind credit union accounts, lending and digital banking.
- Its pitch centers on bringing staff workflows together.
- Outside partners connect through FLEXBridge APIs.
The return makes a useful opening because banking technology is usually judged from the wrong end. We see the app. An employee sees the application, the document, the account record and the next system that needs updating. A polished front door can conceal a surprisingly busy corridor.
The work between the screens
FLEX sells to credit unions, rather than directly to their members. It describes its business as SaaS core banking and digital solutions. Its market position is straightforward: give an institution a broad operating platform, with more of its daily work handled together. The practical comparison with alternatives from Fiserv, Jack Henry or Corelation begins with the tasks a particular credit union needs to finish.
The core combines teller functions, deposits and loans. Cards can be managed there, too, including limits and blocks. Payments extend to ACH processing and origination, card issuance and FedNow integration. This is the operational territory behind the balance someone checks on a phone. Bringing those functions together gives FLEX a concrete proposition: fewer boundaries for an employee to cross.
Smart Lending applies the same idea to borrowing. It offers configurable loan applications, document uploads, eSignatures and underwriting connections. A credit union can define loan types and workflows, while members use an applicant portal. The useful question during a demonstration is whether the application reaches the employee with the information needed to act, without another round of copying and chasing.
New-member onboarding has its own sequence: collect identity information, check it, open the account and fund it. FLEX supports digital and branch workflows, document submission and electronic membership agreements. For the prospective member, this is an application. For the institution, it is a chain of checks and records that has to hold together.
- 01Apply
- 02Verify
- 03Fund
- 04Record
The member sees an application. Staff need a complete record.
Then there is the work nobody puts on an app-store screenshot. FLEX’s financial operations suite includes general ledger, accounts payable, fixed assets, budgeting and financial statements. Its 5300 Call Report Assistant helps gather and organize information for quarterly reporting. These tools support the institution’s reporting work; the credit union still has to own the accuracy of what it submits.
One system. Room for outsiders.
A broad platform also needs a way to accommodate an institution’s existing choices. FLEXBridge is the company’s open API layer, allowing outside applications to connect to core functions and data. Its published security features include access controls, input validation, rate limiting and OAuth 2.0. Connectivity is part of the product proposition, alongside the functions FLEX develops itself.
Consider lending decisions. In November 2023, FLEX announced an enhanced integration with Hart Credit Technology. Hart’s decisioning can use criteria such as debt-to-income ratio, loan-to-value ratio and credit history. That places a specialist’s tools inside the lending workflow. It also makes the credit union’s own policies consequential: automation executes the decision framework people have chosen.
Payments offer another example. A May 2025 Alloya integration connected FLEX credit unions with FedNow and the RTP network, with Alloya acting as funding agent. The announcement covered settlement, reconciliation, reporting and receive-only or send-and-receive participation. Those are useful details because an instant payment creates work after someone presses send.
In September 2025, FLEX announced that Beehive Federal Credit Union could send and receive FedNow payments through its Catalyst integration, around the clock. The outcome involved a core provider, a corporate credit union and the member’s institution. Even a company selling integration has to be good at cooperation.
The second conversion
The revealing friction in FLEX’s customer accounts often appears before a switch. Jackson County Co-op wanted fewer repeated entries and better digital services. It initially favored nearby vendors, then gave more weight to providers serving comparable credit unions. In FLEX’s published case study, CEO Kristina McIntosh also described demonstrations that failed to answer specific workflow questions.
“It’s all about the member”
Kristina McIntosh
Jackson County Co-op Credit Union
Buying software is also buying a learning project. FLEX’s customer accounts describe staff preparation and the time needed to explore functions after launch. Its Academy offers courses and videos spanning lending, cards, back-office work and system management. The practical cost includes employee attention, alongside the contract: people need time to practice unfamiliar jobs before those jobs become routine.
Bring one ordinary member request. Ask the vendor to follow it through every screen, document and approval. Count the handoffs.
That is a useful test for any core provider. An integration label tells you little about an awkward exception or a task left unfinished. A team without time to learn, or with essential partners whose connections do not meet its needs, should be cautious about assuming that a larger feature list will produce a simpler day.
A very long product conversation
FLEX’s company account emphasizes continuity of ownership and a commitment to developing its software around credit union needs. Its service culture is part of that pitch. Buyers can test it through reference calls and training conversations, especially with institutions that resemble their own. A relationship becomes more persuasive when someone can describe what happened after the sale.
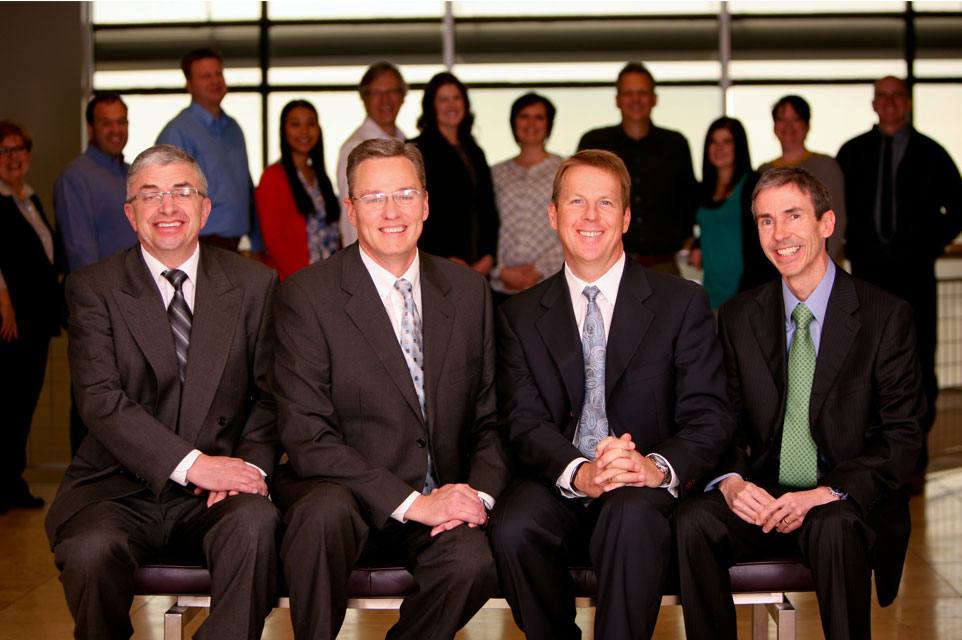
On October 1, 2026, Sean Holcomb became CEO, succeeding founder Fredrick Holcomb, who started the company in 1978. The accompanying announcement put FLEX’s reach at about 300 credit unions in 46 states and the Eastern Caribbean. For those customers, the enduring question remains pleasingly ordinary: can the next member request be completed with less work?
KEEP EXPLORING ↗