In 2004, Feroz Dewan went to a small office in south Delhi to meet Deep Kalra, the founder of MakeMyTrip. Dewan was working at Tiger Global in New York. The travel business was too small for Tiger to invest in then. The visit could have ended with a polite goodbye and an unused business card. Instead, Dewan stayed in touch. Around 2007, he introduced Kalra to his colleague Lee Fixel. Tiger went on to lead a financing round, and then another.
There is an investment story here that begins before the investment. No cheque at the first meeting. A relationship that survived the absence of a transaction. Then an introduction when the circumstances had changed. Finance has plenty of vocabulary for measuring returns; it has rather less for remembering someone three years later.
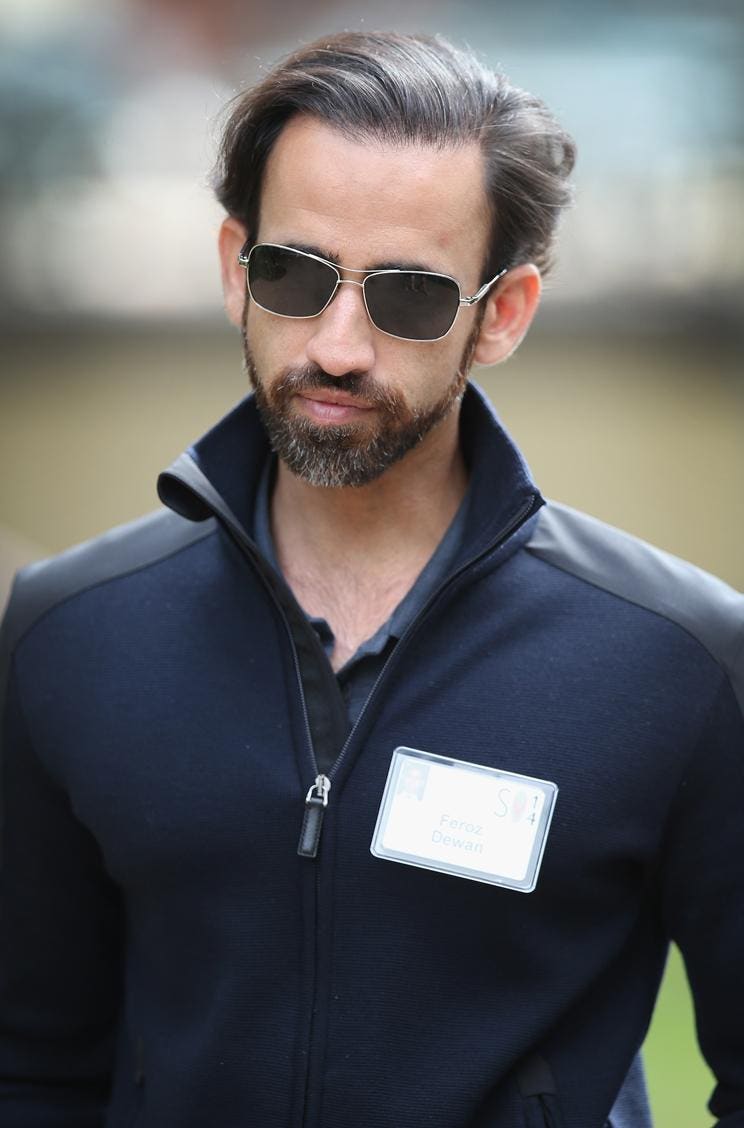
Dewan’s subsequent career gives that small scene a larger setting. He spent twelve years at Tiger Global, eventually heading public equities, before leaving in 2015 to build his own business. Arena Holdings, the firm he founded and leads, describes itself as a permanent capital investor in private and public companies. The word that makes this biography interesting is permanent. It asks a question that a stock price cannot answer: how long can the owner stay?
A civil engineer enters the market
Dewan graduated from Princeton in 1998 with a BSE in civil engineering. His education also included a certificate in applied and computational mathematics. Before Tiger Global, he worked in management consulting at McKinsey & Company and in private equity at Silver Lake Partners. His Silver Lake stint ran from 2002 to 2003.
These were different vantage points on a business. Consulting examines how an organization operates. Private equity examines a company as something to acquire or finance. Public-equity investing adds the daily presence of a market price. Dewan’s professional itinerary took him through all three before he established Arena.
A civil-engineering degree is a pleasing detail in a career spent around technology companies. The discipline deals with structures that must work outside a classroom, under actual loads and with actual consequences. It would be too convenient to turn that into a claim about his investment methods. The factual connection is simpler: an engineering graduate went into consulting and technology investing, then became a capital allocator and corporate director.
There is also a useful distinction between his education and his occupation. Dewan is an investor. His engineering qualification belongs to his training. At Arena, his job is to decide where capital goes and to run the organization that puts it there. A degree supplies a starting point; the next two decades supply the rest of the biography.
The departure that left a question open
In May 2015, Tiger Global told investors that Dewan would leave at the end of June and planned to start his own business. He had joined in 2003. By the time he departed, he was head of public equities, a position that put him at the center of the firm’s listed-company investing.
The news was a career break with a familiar outline: an established investor leaves an established firm. What followed was less straightforward. In September 2016, the question of whether Dewan would accept money from outside investors was still open. His next venture did not immediately fit the standard story of a portfolio manager departing to raise a new fund.
That distinction matters because an investment business is shaped by the people whose money it manages. The portfolio is only one part of the design. Ownership, clients and duration help determine what the organization can promise, and to whom. Starting a firm means making decisions about those arrangements as well as picking companies.
The transition also has two dates worth keeping separate. Dewan’s departure from Tiger occurred in 2015. Corporate biographies date his service as Arena Holdings Management’s chief executive to 2016. An investor can leave one institution before the formal timeline of the next role begins. Compressing the two into a single neat birthday for the business would erase that interval.
The owner’s clock
Arena’s public description is unusually brief: it invests permanent capital in private and public companies. Its conference biography adds a focus on businesses at the forefront of technology-enabled innovation. Private and public are both in the sentence. A listing status is not the boundary of the stated mandate.
Permanent capital gives the reader a different organizing principle from a launch date or a fundraising announcement. In the usual closed-end fund arrangement, the investment vehicle has a finite life. An owner using permanent capital can approach duration differently. That structural distinction does not settle whether an individual investment will work. It changes the calendar around the decision.
The private-company and public-company combination is equally important. A private business raises money through negotiated transactions. A listed business has shares traded in a market. Both still need customers, management and a way to turn their activity into durable economic value. Arena’s description allows Dewan to consider companies on either side of that institutional divide.
For an investor with experience at Silver Lake and Tiger Global, the mandate brings earlier chapters of his career into the same business. It also leaves a practical question for every prospective investment: what makes this particular company worth owning? A longer possible holding period does not make that question go away. It gives the owner more years in which to discover whether the original answer was sound.
A family office, in precise language
Arena’s regulatory paperwork supplies another piece of the picture. Its 2019 application described a multi-generational single-family office in New York, formed and led by Dewan. The office was owned by family clients and controlled by family members or family entities. Its work included investment due diligence, asset allocation and investment management, alongside the administrative responsibilities of a family office.
The application sought permission to serve an additional, closely connected set of family clients while retaining treatment outside the investment-adviser definition. These are technical distinctions with everyday implications. They identify the intended clients of the office and the limits of the business described in the filing.
“Global investment business” and “single-family office” describe different aspects of an organization. The first describes an investing scope; the second describes whom the office serves. Neither phrase, by itself, supplies a performance record. What they do supply is a more exact account of the business Dewan chose to establish after Tiger.
The view from the boardroom
Alongside Arena, Dewan has served on public-company boards. He joined Fortive’s board in 2016, when the company separated from Danaher, and was appointed to its audit and compensation committees. He also served on Kraft Heinz’s board from 2016 to 2020. His Fortive service later ended; Danaher’s 2026 proxy treats it as a past directorship.
In June 2022, Danaher appointed Dewan to its board and its Science & Technology Committee. Chairman Steven Rales welcomed the combination of financial judgment and technology experience he brought. The appointment expanded the board from thirteen members to fourteen.
“his financial acumen and technology expertise”
Steven M. Rales, on Dewan’s 2022 appointment
Board work changes the position from which an investor encounters a company. The responsibilities include oversight of management, financial reporting and governance. Buying a security and serving as a director are different jobs, even when a person brings related experience to both. Dewan’s appointments put corporate oversight alongside his work allocating capital.
The chronology continues into 2026. Danaher’s shareholders reelected him on May 5 to a term expiring in 2027. The company’s proxy identifies him as an independent director and lists no other current public-company directorships. That places the present chapter clearly: Arena remains his executive role, with Danaher his public-board appointment.
An idea before the hors d’oeuvres
Dewan’s work in education supplies a smaller, more personal scene. Angela Duckworth recalled that he met educator Dave Levin at a cocktail party and asked about an idea Levin had not yet put into practice. Levin described what became Character Lab, connecting behavioral science with education. Dewan became its founding board chair.
Later, Duckworth was in a Duane Reade after a board meeting when Dewan called to suggest she become the nonprofit’s CEO. She initially found the proposal implausible alongside her university responsibilities, but took the role. The organization moved from New York to Philadelphia.
Duckworth also remembered quarterly meetings with Dewan devoted to reflection, goals and continuous improvement. The episode included a complication: she wanted to develop as a psychologist, writer and communicator, and did not regard becoming a better organizational leader as her first priority. The story allows for a useful untidiness. Appointing a capable person does not eliminate the question of what that person wants to do.
Character Lab thanked Feroz and Erica Dewan for their service as founding board members in its 2022 annual letter. Sean Talamas, writing about the organization’s leadership, credited Dewan with keeping attention on helping children thrive while allowing flexibility in the tactics used to pursue that goal. That is a specific contribution, beyond a name on a donor list: keep the objective in view, and allow the route to change.
The relationship before the cheque
Return to the office in Delhi. The most revealing part of that early encounter is its sequence. First a visit, then continued contact, then an introduction. The transaction arrived later. Dewan was one participant in a larger investment organization, and Fixel led the subsequent relationship described by Kalra. The sequence preserves both men’s roles without turning a shared history into a solo accomplishment.
Today, Dewan’s career spans a New York investment business, past corporate directorships, a current Danaher board seat and education-related board work. Those activities involve different kinds of commitment. A portfolio position can be traded. A director has governance responsibilities. A nonprofit chair helps an organization choose its leadership and keep its purpose clear.
Arena puts duration into its own description. The early MakeMyTrip encounter puts duration into an actual relationship. Between those two points sits a career in which knowing a company, owning it and helping oversee it have each been part of the job. The small Delhi office is a good place to begin because the investor left without making an investment. He still had something worth keeping: a reason to stay in touch.
Follow the next chapter
Profiles, reporting and a conversation about leadership.