Erik Serrano Berntsen generally leaves the naming of an investment firm to its founder. There was, however, the Japanese sword. A prospective name borrowed from one was so difficult to pronounce that he felt obliged to intervene. A business may aspire to cut through the market; it still helps if a customer can say its name. The anecdote is small, funny and unusually revealing. Berntsen spends his working life considering what happens around an investment strategy: the decisions that make an organization understandable, workable and capable of staying together.
His own firm is called Stable. He credits his wife with helping arrive at the name, which carries two meanings: patient capital and a home for a collection of partnerships. In his telling, the horses have accumulated. Stable was founded in 2006; by July 2026 it reported having supported the growth of 46 investment firms. The naming joke has acquired a substantial business underneath it.
Berntsen is Stable’s founder and chief executive, responsible for its investment strategy. His subject is the investment firm itself. He backs people who want to establish or expand organizations in alternative investments, with capital and assistance in building the business. An investor’s judgment remains essential. So does everything that allows that judgment to become a repeatable service for other people’s money.
An education in the machinery
Before Stable, Berntsen worked at Bain & Company. In its Private Equity Group, he undertook deal studies and assessed investment opportunities; his wider consulting work included banks and investment firms. The job placed him close to the machinery of businesses: how an opportunity is evaluated, how a commercial proposition holds together, how an institution decides what to do next. Those are useful questions for someone whose eventual business would involve evaluating other people’s businesses.
His education joined two different traditions. At Keble College, Oxford, he studied politics, philosophy and economics. At the University of Chicago Booth School of Business, he earned an MBA with honors and a concentration in finance. The combination sits comfortably beside his present work, which requires a view of incentives and organizations as well as investments. A founder brings a strategy; a partner must also consider the structure in which that strategy will operate.
In January 2024, his conversation with Patrick O’Shaughnessy centered on investing in investment firms, the characteristics of promising founders and the support they need through a business’s life. He had already discussed the work with Ted Seides in 2021, when Stable was described as managing around $3 billion. Across those conversations, the recurring interest is practical: what helps a capable investor become the founder of a functioning enterprise?
The enterprise around the portfolio
Stable makes seed and acceleration investments. Seeding supports a launch; acceleration supports a firm that already exists and wants to develop further. The distinction matters because a founder beginning with a blank sheet and a founder managing an established team face different tasks. Both need capital. They may need different kinds of help, at different moments, before that capital can do much useful work.
A fund and the firm managing it occupy different places in this arrangement. A limited partner commits money to an investment fund. A general partner organizes and manages the investment business. Berntsen’s interest in GP stakes gives investors exposure to the economics of the manager, alongside the question of how its funds perform. His work therefore reaches beyond choosing a strategy into choosing and supporting the organization responsible for it.
The everyday implications are less glamorous than the vocabulary. Capital formation, talent acquisition and operations are part of Stable’s stated offering. Someone must assemble the team, communicate with investors and keep the business functioning. A compelling investment idea does not write its own employment agreements or answer its own client questions. Berntsen’s model gives those jobs a place in the investment conversation rather than leaving them to appear as surprises later.
There is an appealing seriousness to that approach. Finance is very good at naming things that sound consequential. It is less entertaining to explain who will do the work on Monday. Stable’s proposition asks founders to treat that second question as part of the first. The firm’s offices in New York, London and Palm Beach give the operation a footprint across the Atlantic, while its partnerships span private markets and absolute-return strategies.
The fund
A limited partner commits capital to an investment strategy.
The firm
A stake or revenue-share interest participates in the manager’s business economics.
He put the instructions in a book
In 2015, Berntsen and John Thompson co-authored A Guide to Starting Your Hedge Fund. The title promises a set of instructions, and the contents take that promise seriously. The book considers legal and commercial structures, service providers, fundraising, operations and due diligence, with particular attention to energy commodity markets. It is a useful artifact of his career: years before the latest GP-stakes discussion, he was writing about what it takes to get an investment business into working order.
The operations chapter organizes its discussion around risk, people, processes and procedures. It recognizes that different funds have different needs depending on strategy, geography, trading frequency and other features. That specificity is instructive. A business built to trade one set of markets cannot simply borrow another firm’s infrastructure and assume the fit. Even the physical office must be considered in relation to cost, business requirements and the size of the organization.
Another chapter approaches energy commodity hedge funds from the allocator’s perspective, including the role of a due-diligence questionnaire. For a founder, this is the other side of the table. An investor has questions that extend beyond whether an idea is clever. The business must be able to answer them in a form someone else can evaluate. The book’s movement between manager and allocator shows the two audiences Berntsen’s work must continually bring together.
A guide is also a revealing choice of format. It requires the author to put tasks in an order and explain the connections between them. The romance of starting a firm survives contact with a contents page containing lawyers, service providers and investor maintenance. Barely. Yet those headings give ambition somewhere to go. A founder can disagree with a procedure, hire someone to improve it or replace a provider. An undefined problem is harder to delegate.
Four practical concerns behind an investment enterprise.
The partners who call on Sunday
With experience, Berntsen has come to regard his own founder status as a source of connection with the people Stable backs. He describes the relationship as one between people who have faced unfamiliar problems while still being expected to produce answers. That experience gives the partnership a personal dimension. A founder can speak to someone who has also had to build, adjust and keep going.
He has described spending weekends talking with partners about staffing decisions and difficult investor conversations. The detail makes the word support more concrete. Availability has a calendar cost. It also creates occasions for advice that a formal meeting might miss, particularly when the question is awkward or urgent. The partnership extends into the parts of running a firm that rarely make it into its introductory presentation.
He is candid about an early weakness: underestimating the importance of talent acquisition within partner firms. In some investments, leadership changed within six or twelve months. His lesson concerns continuity and the need to build teams likely to remain together. It brings his interest in people back to an operational fact. A strategy may belong to a firm on paper, but people must be present to execute it.
There is little mystery in why that matters, though it can be difficult to manage. Hiring creates relationships as well as job descriptions. A founding team has to make decisions together when the circumstances change. Berntsen’s experience gives the subject weight without requiring a heroic account of every setback. The useful question becomes what the next partnership should do differently, and how early it should begin.
“The thing I didn't expect to be our biggest competitive advantage: being a Founder myself.”
Erik Serrano Berntsen · shared by Stable, 2026
A different kind of partnership
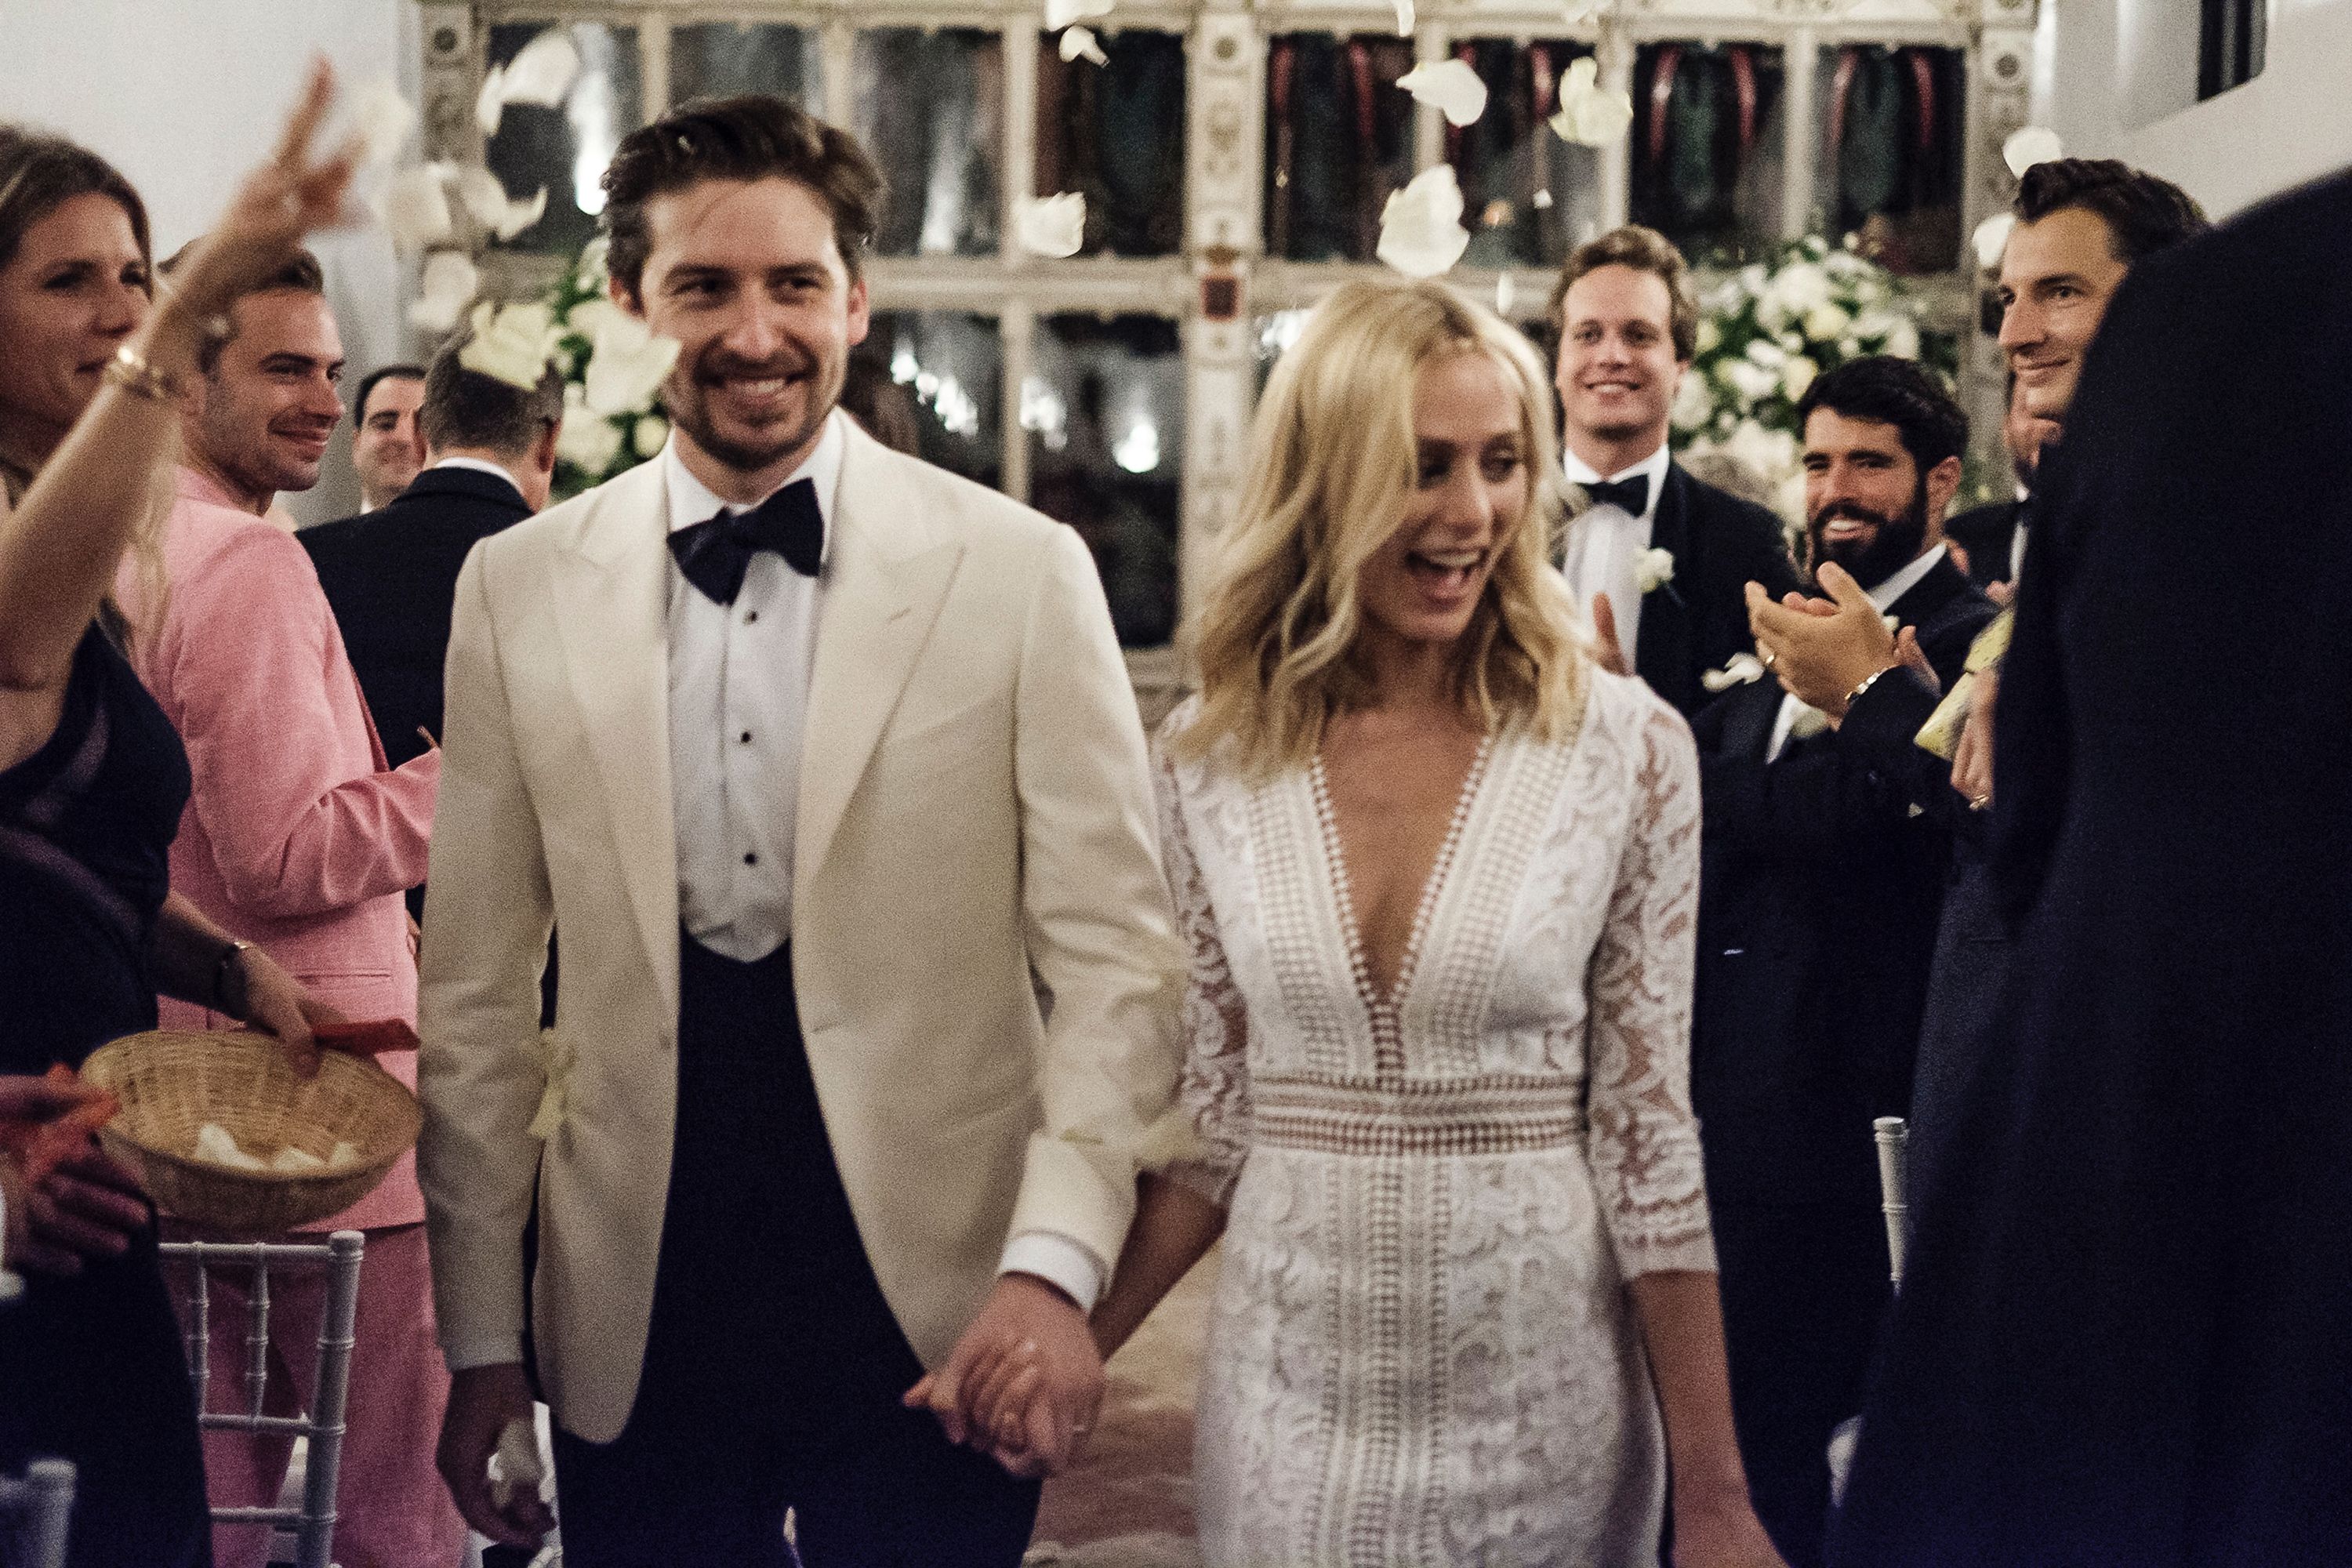
Away from investment firms, Berntsen’s public story includes Katherine Holmgren, a co-founder of the fashion label Galvan. They met at a friend’s Christmas party in 2013. He asked her to leave for dinner. Their wedding took place in Seville, and the celebration included a disco with a notably uncorporate name: The Fluffy Disco. Berntsen grew up in Madrid. For a person professionally interested in naming businesses, the party offers a pleasing reminder that a name can sometimes be chosen simply because it makes people smile.
From the classroom to the conference stage
Education also appears in his public commitments. He supports the LSE Alternative Investments Conference, Girls Who Invest and Girls Are Investors. Stable supports 100 Women in Finance and is a founding partner of the 10,000 Interns Foundation. These are specific connections to programs and networks concerned with entry into investment careers. His biography also records advisory work for the Prince’s Trust during his time at Bain, including a volunteer-strategy initiative.
In May 2026, Berntsen moderated a discussion between Alexis Ohanian and Marc Lasry at the Sohn Investment Conference in New York. Its subject was sports as an investment frontier. He was also listed on the conference’s host committee. The setting placed him alongside founders and investors considering a business whose customers express their loyalties rather more loudly than most limited partners do.
The appearance broadens the picture without changing its center. His public work includes asking how an enterprise is built, who owns it and what makes it attractive to capital. On a conference stage, those questions become a conversation other people can follow. In a partnership, they become decisions with consequences for a team. The setting changes; the attention to businesses and the people directing them remains recognizable.
Twenty years, and another transaction
In July 2026, Stable announced the completion of a $190 million sale of minority net revenue-share interests in alternative asset managers to Navigator Global Investments. The closing established a long-term strategic partnership. Stable would continue managing and monitoring the portfolio, known as NGI Stable Growth, and providing guidance and support to its managers. Stable and its limited partners became minority shareholders in Navigator.
At that point, Stable reported approximately $5.2 billion in assets under management. Its partner firms collectively managed $27 billion. Those figures describe different things: Stable’s own reported assets and the assets managed across its partners. The distinction is worth keeping intact, particularly in a business built around relationships between investment organizations. The sale price, meanwhile, belongs to the transaction involving revenue-share interests.
For Berntsen, the transaction connects an established portfolio with another institution’s resources and network. His continuing role is the part that fits the longer story. After twenty years, the work still includes managing relationships, monitoring firms and helping organizations develop. The ownership arrangement changes while those responsibilities continue.
The Japanese-sword story makes a fitting place to return. Berntsen did not need to settle a grand question of investment theory to help that founder. He needed to notice a practical problem and say something. Much of his career has given that kind of intervention a larger setting: capital, a team, a partnership and the patience to remain involved. The name can be fun. Then there is a business to build.