A portfolio that loses half its value needs to double just to get back to where it started. The calculation takes a moment. The recovery can take considerably longer. Don Schreiber Jr. has built much of his working life around that uncomfortable gap between the ease of losing money and the effort of making it back.
He founded the business that became WBI in 1984. Three decades later, he and his son Matt helped launch ten actively managed exchange-traded funds at once. More than $1 billion entered on the first trading day. For a founder concerned with keeping investors comfortably invested, it was an unusually noisy milestone.
The detail beneath the number is more revealing. Most of the assets came from clients already with the firm, moving their money into a different investment structure. About $200 million was new. The launch was a substantial rearrangement of an existing house, with the occupants still inside.
That is a useful place to begin with Schreiber. His career contains books, portfolios, a family working partnership, and financial software. Across them runs a persistent question: how can an advisor turn an investment approach into something clients can keep using when markets, and their own nerves, become uncooperative?
A business before the tickers
Before there were funds with stock-exchange symbols, there was Wealth Builders. The original name was unusually direct about the proposed service. Schreiber had graduated from Susquehanna University in 1977 with a Bachelor of Science; his field was business finance. He established the firm seven years later, initially providing financial advisory and business planning services to individuals and institutions.
In 1992, the firm introduced its first proprietary portfolio strategies. The distinction matters in a founder’s biography. Advising someone about their money and designing an investment process are related jobs, but they create different obligations. A process needs decisions that can be repeated across accounts, including on days when the person making them would rather wait.
WBI’s stated ambition became a combination of capital preservation in falling markets and participation in rising ones. The aspiration is easy to admire and difficult to deliver. Selling to limit damage can mean missing a rebound. Remaining invested can mean absorbing a decline. Every implementation has to make choices between those possibilities.
Schreiber’s subsequent work kept returning to that practical territory. Separately managed accounts, mutual funds, and ETFs gave the firm different ways to package its approach. The machinery changed as the business grew. The question of how much loss an investor could endure kept its place.
Losses leave a larger bill.
Gain needed to recover to the starting value. Illustrative arithmetic, excluding fees, withdrawals, and taxes; not WBI performance.
The cash that arrives while you wait
His interest in dividends supplied another answer to the problem of staying invested. With Gary E. Stroik, Schreiber co-authored All About Dividend Investing. The first edition appeared in 2004. The second was published in October 2010, with a 2011 copyright, after a period that had given investors ample reason to reconsider their assumptions.
The book’s territory extends beyond identifying a stock with an appealing payout. Its contents include dividend ratios, research, portfolio design, protecting capital, and the use of funds. That breadth makes the dividend part of a method: examine the company, consider the income, and decide how the holding fits with everything else.
A dividend also gives patience something tangible to do. A shareholder can receive cash while the quoted price moves around. The payment does not abolish risk; a company can reduce it, and a falling share price can overwhelm it. But it changes the experience of ownership. Waiting comes with an entry on the account statement.
Schreiber could be more colorful when discussing individual businesses. Describing the insurer Chubb in 2017, he called it a “Tiffany insurance company.” He also reached for Cadillac as a comparison. The point was premium positioning and the ability to charge for it. Even in a quantitative investment career, a familiar shop window sometimes makes the explanation easier.
“It’s a Tiffany insurance company.”
Don Schreiber Jr., discussing Chubb in 2017
A billion dollars changes its clothes
By August 2014, WBI was celebrating thirty years in business. At the time, it reported nearly $3 billion under management and approximately seventy employees. These were the dimensions of the firm at that anniversary, before the ETF launch became the more memorable headline.
The ten-fund launch brought an existing allocation approach into tradable components. Investors who had used separately managed accounts could hold the approach through ETFs. Much of the first-day asset total represented that migration. Schreiber’s explanation was characteristically procedural: take a complete portfolio approach and divide it into ten funds.
The attraction included the tax efficiency associated with the ETF structure. The bill deserved attention too. At launch, annual fund expenses ranged from 1% to 1.08%, above the contemporary active-ETF average cited in coverage of the debut. Those historical fees belong beside the historical asset figure. A different wrapper can improve some things while leaving an investor with a meaningful cost to assess.
The episode shows Schreiber at work as a designer of delivery as well as investments. He had clients, portfolios, and an approach already in use. The task was to move them into another structure. A billion-dollar opening day made the event visible; thirty years of business made much of it possible.
Two Schreibers, one set of problems
Matt joined WBI in 2005. Today, father and son share the titles of co-CEO and co-chief investment officer, and both work as portfolio managers. Their collaboration on the 2014 launch provides a concrete chapter in that relationship: an established founder and the next generation building products together.
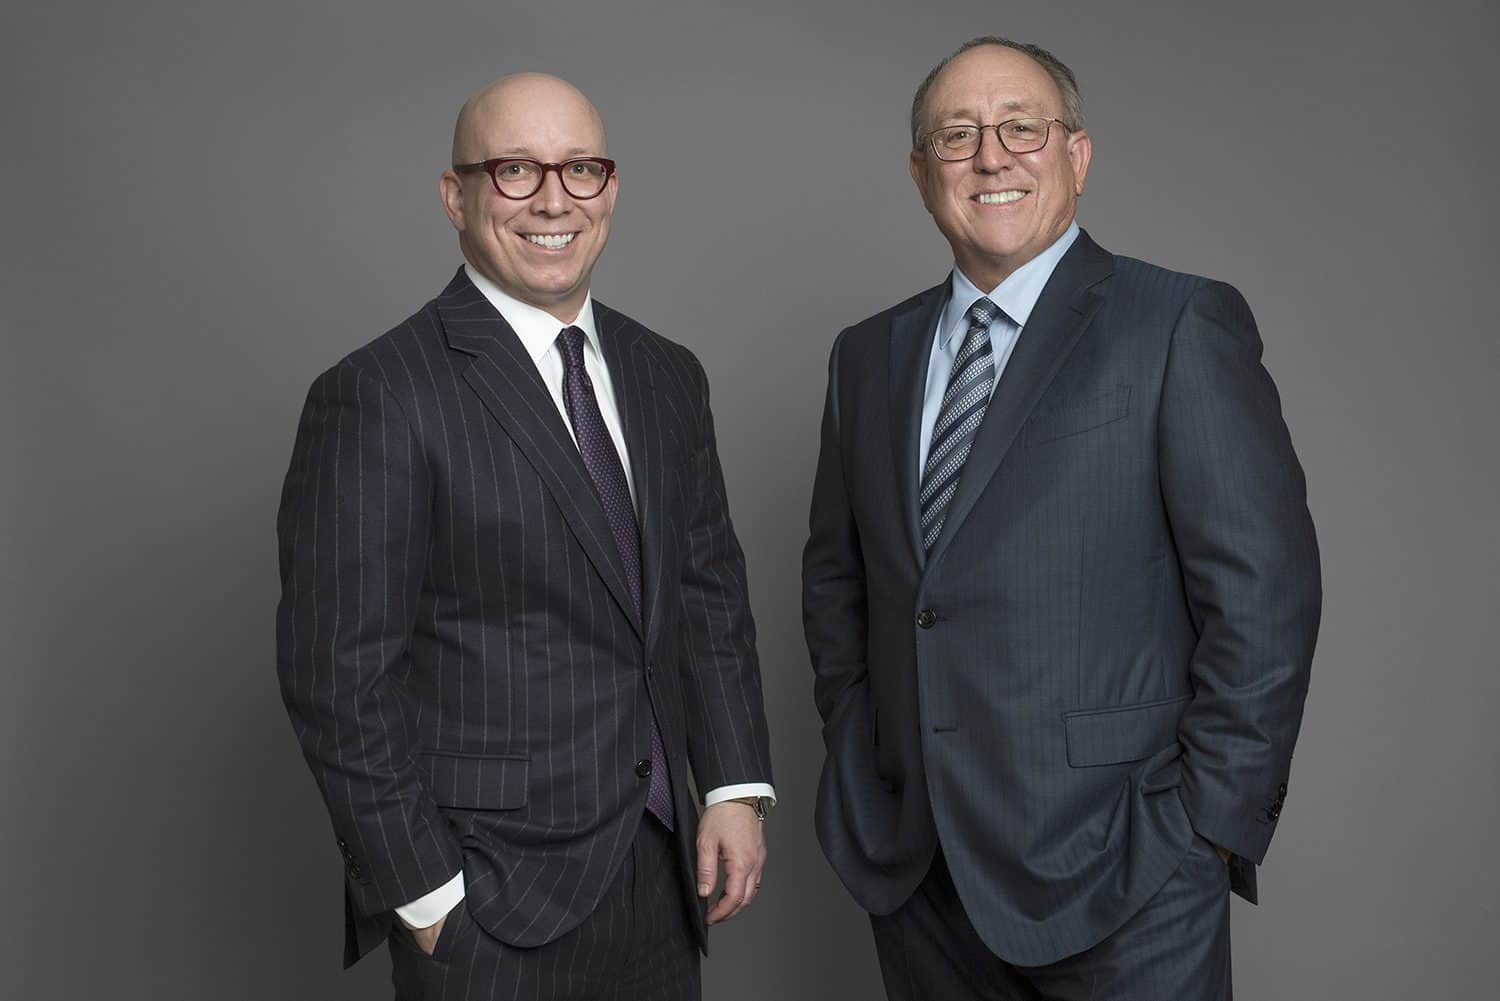
The partnership also became audible. On Bull | Bear Radio, Don and Matt discussed investing in a format less formal than a fund document. Rick Kundracik joined as host in 2021. The archive includes conversations about taxes, market conditions, and portfolio decisions, including a July 2021 discussion with PIMCO’s Alan Trice.
In that July conversation, the subjects included municipal bonds, dividend income, and the tax characteristics of ETFs. These are less theatrical subjects than predicting the next market move, but they belong to the everyday decisions an investor actually faces.
Those appearances add a public-facing job to the founder’s list. An investment process has to be explained as well as operated. A client can look at the same price movement as a portfolio manager and draw a very different conclusion. Talking through taxes or market conditions offers a chance to connect the calculation with the person expected to live with its result.
The founder cannot do every job
Schreiber’s other book tackles the economics of the advisor’s own business. Published in 2001, Building a World-Class Financial Services Business addresses how a sales practice can become a company with equity value. Its subtitle makes the financial ambition explicit: turning a practice into a business worth millions.
There is an awkward problem beneath that promise. A successful advisor can accumulate clients while remaining indispensable to every task. The calendar fills up, revenue comes in, and the business still depends heavily on one person. Building value requires a service that other people can help deliver, using systems that survive a busy afternoon.
His later technology work belongs in that context. In 2020, Cy announced machine-optimized ETF portfolios personalized around client parameters. Schreiber was identified as WBI Technologies’ founder and chief visionary officer. The platform combined portfolio tools with electronic account opening, performance reporting, billing, and back-office support.
Billing rarely gets the glamorous paragraph in a founder’s story. It earns its place here. These are the recurring jobs that consume an advisor’s time. Putting them into a workflow gives a business a better chance of serving clients consistently. Cy received a FinTech Breakthrough award for Best Robo Advisory Platform in 2021, recognition for the platform rather than a personal trophy for its founder.
The business book and the software therefore sit comfortably together. One describes the move toward an enterprise with lasting value. The other supplies tools intended to help advisors do the daily work.
Still looking for a way to participate
Schreiber’s public commentary can sound wary. In 2015 and 2016, he argued that low rates and quantitative easing could encourage investors to assume asset prices would keep rising. He questioned the gap between market prices and underlying fundamentals. These were positions taken at particular moments, with all the uncertainty that market judgments carry.
His later writing also makes room for enthusiasm. A WBI paper published in June 2026, carrying his name and an internal May date, argues for disciplined participation in the AI investment cycle. It describes an approach to selecting companies across the AI economy while discussing valuation, concentration, and other risks.
Read together, the pieces show a concern with how to participate when opportunity arrives with uncomfortable prices and uncertain outcomes. The subject changes from central-bank policy to artificial intelligence. The work still involves choosing investments, sizing exposure, and deciding what can go wrong.
Four decades after founding Wealth Builders, Schreiber remains involved in the firm’s leadership and portfolios. The career is long enough to contain both an advisory-business manual and a paper about AI, both a family partnership and a billion-dollar launch. Underneath those different chapters sits the original calculation. Capital lost has to be earned back. He has kept building around the difficulty of doing so.
Follow the work
Read WBI’s leadership profile, explore the WBI blog, or find Don on LinkedIn and X.
Listen to Bull | Bear Radio. For more on the work: the dividend book, the 2014 ETF launch and its fees, and the 2026 AI paper.