A venture investor can learn a great deal from a streaming bill. Before Theta was a blockchain network, its founders were building SLIVER.tv, a platform for watching esports from unusual angles, including virtual reality. More viewers meant more video to deliver. In a later public account, co-founder Mitch Liu described content delivery costs that his young business could not sustain. The audience was growing. So was the problem.
- DHVC pairs venture funding with technical understanding.
- Its Theta investment grew from esports financing into network participation.
- The useful lesson: find the costly constraint before choosing the technology.
That is an illuminating way into DHVC, the venture firm historically known as Danhua Capital. A portfolio list tells you where a fund placed its money. In this case, the question became whether the machinery needed to deliver the entertainment could become an opportunity of its own.
A difficult operating decision tells you what an investor might actually be good for.
The professor and the practitioner
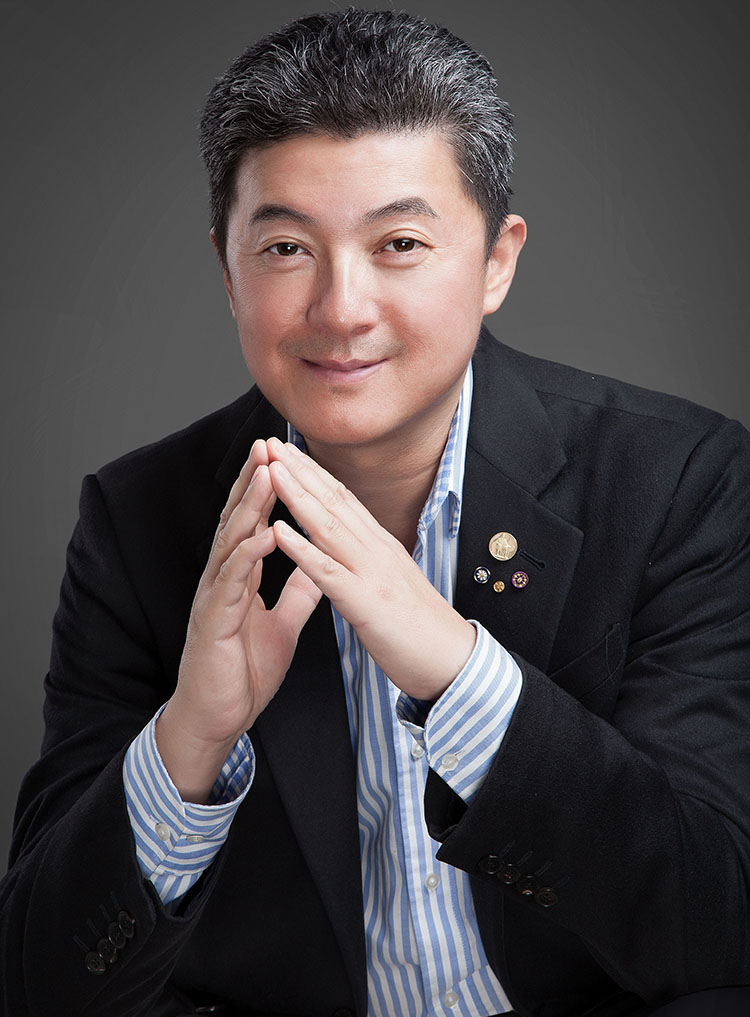
DHVC began in 2013 with Shoucheng Zhang, a Stanford physicist, and Andrew Gu, his former student. Their biographies supplied an unusual combination: theoretical research alongside experience building technology companies. Gu had worked at InvenSense, the sensor business. Zhang’s research explored quantum states of matter. The shared thread was an interest in how unfamiliar technical ideas become useful.
It is tempting to turn that origin into a formula: hire scientists, discover tomorrow. The more defensible interpretation is narrower. People who understand a technology may be better equipped to interrogate its assumptions. They can ask what must be true for it to work, which experiment would settle the question, and whether the proposed advantage survives outside a demonstration.
The expensive part of watching
In August 2017, SLIVER.tv announced a $9.8 million Series A led by Danhua Capital. Its proposition involved making esports viewing more interactive, including 360-degree perspectives. This was a bet on an entertainment experience, with machine vision and streaming technology underneath it.
Liu’s later account adds the revealing detail. DHVC managing director Dovey Wan joined the board and helped guide the company toward a peer-to-peer, blockchain-based approach to delivery. Viewers’ computing and bandwidth resources could help distribute video. A cost inside one business suggested infrastructure that other video businesses might also use. That thinking helped produce Theta.
The account describes a portfolio company changing direction; it does not establish a wholesale change in DHVC’s strategy. What it does show is an investor participating in the technical conversation when the original economics became uncomfortable. The attractive feature was no longer simply a better seat at an esports match. It was a possible answer to the bill for broadcasting it.
- 01More viewersVideo delivery demand rises
- 02A costly bottleneckCentralized delivery strains the model
- 03A different architectureExplore shared bandwidth and incentives
By June 2021, DHVC’s involvement had become operational. It joined Theta as the ninth external enterprise validator and a governance council member, alongside an existing group that included Google, Samsung, and Sony. Ali Farahanchi, then a DHVC managing director, described it as “taking a direct role in securing its blockchain.” Financing had been followed by participation in the network itself.
Capital that stays for the experiment
DHVC’s business sits between two groups. Fund investors commit capital; startup founders receive financing and support. The product is a financing relationship rather than a software subscription. For founders, the proposed advantage is an investor who can understand the technical work and contribute as the business develops. For fund investors, the proposition is exposure to privately held technology ventures.
The money needs the right labels. Danhua’s first fund reported approximately $91.25 million in 2014. Its second fund was reported at $250 million during fundraising in 2016 and later at $343.2 million in 2018. Those second-fund figures describe stages in the same vehicle’s history. Adding them together would count the money twice.
Capital for investment. Separate from the management company’s revenue, valuation, or realized returns.
There is a price on both sides of the relationship. Equity financing gives investors an ownership claim; founders weigh dilution and decision rights against the capital and help offered. Private fund investors accept exposure to uncertain outcomes and limited liquidity. DHVC’s March 2026 filing reports a routinely required $500,000 investor commitment for each of its two listed funds. That historical reporting detail is not a current offer.
The same question, inside a cell
The portfolio’s scientific range becomes clearer with Engine Biosciences. In January 2018, DHVC and 6 Dimensions Capital co-led its $10 million seed financing. Engine combined biological experimentation with artificial intelligence to investigate genetic interactions relevant to drug discovery. The funding supported platform development, hiring, and preclinical work across Singapore and San Francisco.
Here, too, the starting point was a constraint: the enormous number of biological relationships researchers might need to test. Computation could help interpret experimental data and direct further work. The family resemblance to the streaming investment lies in the question being asked: can a different technical method change the economics of a difficult task?
Borrow the question, not the portfolio
For a founder evaluating DHVC or a comparable investor, that is the practical test. Bring the expensive, slow, or unreliable part of the business into the discussion. Explain the mechanism, propose a measurable experiment, and ask what relevant help the investor has provided before. A specific story about a board-level technical decision is more useful than a promise of introductions.
The approach has limits. Technical understanding cannot guarantee customer demand, workable distribution, or enough capital to finish development. Peer-to-peer delivery still faces physical network constraints; biological predictions still require experiments. A method that improves one bottleneck may leave the rest of the business untouched. The investor and founder need a shared understanding of those remaining problems.
The recent record is quieter than the origin story. Public databases list DHVC in Ink Finance’s $5 million financing in June 2024. Its March 2026 regulatory filing places the adviser in Menlo Park and still lists two venture funds. The enduring lesson is a question founders can use immediately: which cost have you accepted as inevitable, and what would an experiment reveal about changing it?