In October 2021, a private equity investor arrived at Savant Wealth Management, and the founder kept control. Brent Brodeski would continue to run the company and its board. His management team would remain. Kelso would take a minority stake, and Christopher Collins and Steve Dutton would join the board. For a transaction involving a firm with nearly $12 billion in assets under management at the time, the arrangement contained a surprisingly plain idea: bringing in an investor need not mean handing over the keys.
That is a useful place to begin with Collins, Kelso’s co-chief executive officer. A title can tell you where someone sits in an organization. A transaction tells you something about the work. Here, money, advice, ownership, and authority had been fitted together in a particular way. The business could seek more resources while its founder retained the controls. The seating plan was changing; the person at the wheel was staying.
The founder kept the keys
Savant’s investment was intended to support acquisitions and organic growth. Kelso would also offer access to resources in technology, marketing, human capital, and mergers and acquisitions. Those are practical areas of a service business: the systems people use, the colleagues they hire, the clients they reach, and the firms they might bring into the organization. A capital infusion becomes more interesting when its intended uses have names.
Collins described the connection in terms of aligned interests. Savant’s employee ownership was part of that connection. Brodeski, meanwhile, emphasized that he had sought a partner whose values and approach matched the company’s own. The two sides were talking about the relationship as well as the financing. Neither statement, by itself, settles how a partnership will perform. The ownership arrangement gives the words something concrete to stand on.
“Central to Kelso’s investment approach is a clear alignment of interests with our partner companies”
Chris Collins, on the Savant investment, October 2021
The distinction between an equity stake and operating authority matters throughout this story. An investor can own part of a business, sit on its board, and help fund expansion while someone else directs the daily work. Savant’s announcement made those divisions explicit. Collins entered as a board member associated with a minority investor. Brodeski remained in control. One could call that partnership, but the useful part is being able to describe who would do what.
Three responsibilities, one ownership arrangement. No ownership percentage was disclosed in the announcement.
English, then equity
Collins’s route into this work began with an English degree at Duke, completed in 1996. Three years as an analyst at Stonington Partners preceded business school. In 2001, he received his MBA from Stanford and joined Kelso. It is a compact sequence: undergraduate study, investment work, graduate study, and entry into the firm where he still works.
The English degree is an appealing detail, especially in a profession usually described through financial qualifications. It is also simply a degree, rather than a ready-made explanation of how he thinks. The documented transition is interesting enough on its own. Collins moved from one discipline into investment analysis, then business school, then a career that now combines leadership of a private equity firm with financial-services investing.
His Kelso responsibilities include membership of the Management Committee and an investment-partner role. He co-leads the financial-services practice and also focuses on business services. Those two areas overlap in his portfolio work. Insurance companies require operational support. Wealth advisers require people and systems. Growing businesses require accounting expertise. Collins’s investments lead repeatedly toward the organizations that help other organizations function.
The work behind the policy
Two months after Savant’s announcement, ReSource Pro announced that Kelso had taken a majority interest in its business. The company provided business-process solutions for property and casualty insurance organizations. In December 2021, it had more than 5,000 employees and service operations in the United States, China, and India. Its customers worked in insurance; ReSource Pro helped with the operations supporting that work.
The company said it would remain an independent, privately held entity and retain its management team. The contrast with Savant is instructive. One transaction involved a minority investment, the other a majority interest. In both announcements, management continuity was stated plainly. Ownership and leadership were being addressed as separate parts of the deal, rather than bundled into a vague promise of collaboration.
Collins’s comments on ReSource Pro emphasized its understanding of the insurance industry and its position in its market. Dutton discussed supporting its growth with expertise and capital. Together, those comments describe an investor’s proposed contribution to an existing organization. The people running the business brought the operating knowledge. Kelso brought a financial stake and additional resources. The transaction was meant to connect them.
Insurance runs through other parts of Collins’s work. Kelso invested in Bermuda-based Premia Re in 2017, and Collins is a director. Premia focuses on the property and casualty run-off market. In a 2021 announcement concerning Premia’s acquisition of Armour, Collins referred to Kelso founding the business with Arch and management in 2017. That is another form of relationship: helping establish a company alongside industry participants, then supporting its further development.
Founder retained control
Management team retained
Different ownership positions. Management continuity was explicit in both announcements.
The accountants enter the picture
In August 2022, Kelso announced an agreement to acquire WilliamsMarston. The advisory business provided accounting, tax, valuation, and managed SEC services to more than 1,100 clients. At that point it had approximately 145 consulting professionals across six metropolitan areas in the United States. These were the people companies could call when growth or a transaction made the financial reporting considerably less comfortable.
WilliamsMarston works with pre-IPO, public, and private equity-backed businesses managing growth and transformation. Its current range of services also includes technology and transaction advisory. Collins is a director and appears on the Kelso team associated with the investment. Dutton is there too, along with other colleagues. The recurring names make the work look less like a collection of isolated purchases and more like a continuing practice.
Consider the relationship between this business and ReSource Pro. Their customers and services differ, but both sell specialized help with work a client must get right. The comparison explains the connection between Collins’s stated areas of focus without pretending the companies are identical. Financial services and business services can meet in the same boardroom, particularly when a company’s product is the expertise its people deliver.
An ownership stake travels north
Pathstone added another wealth-management relationship in 2023. The firm announced an investment from Kelso alongside a continuing commitment from Lovell Minnick Partners. At the time, Pathstone had more than 350 employees, including over 180 shareholders, and operated across 17 offices. Its work included family-office services and investment advice for families, individuals, foundations, and endowments.
The employee shareholders matter to the story because ownership already existed inside the business. Kelso was entering an organization where many colleagues also held equity. Pathstone described the new relationship as supporting investment in people, processes, and technology while existing management continued to control and manage daily operations. Kelso confirmed that it completed the investment in May 2023. Collins is active in the investment; his biography distinguishes that involvement from the directorships it lists.
Then the wealth-management thread crossed into Canada. On January 12, 2026, Wellington-Altus confirmed the close of a secondary minority investment of nearly C$400 million from Kelso. Kelso acquired a 25 percent stake. Collins is active in that investment as well. The transaction involved existing shares, which makes it different from a simple description of new money entering a company to fund expansion.
Secondary transactions allow existing owners to sell holdings. They therefore put another question beside growth capital: what can shareholders realize from the ownership they already have? The Wellington-Altus transaction adds this dimension to the story. Savant, Pathstone, and Wellington-Altus belong to the same broad world of wealth management, but their deal structures deserve their own sentences. “Investment” is a rather small word for so many different arrangements.
A board seat is a relationship
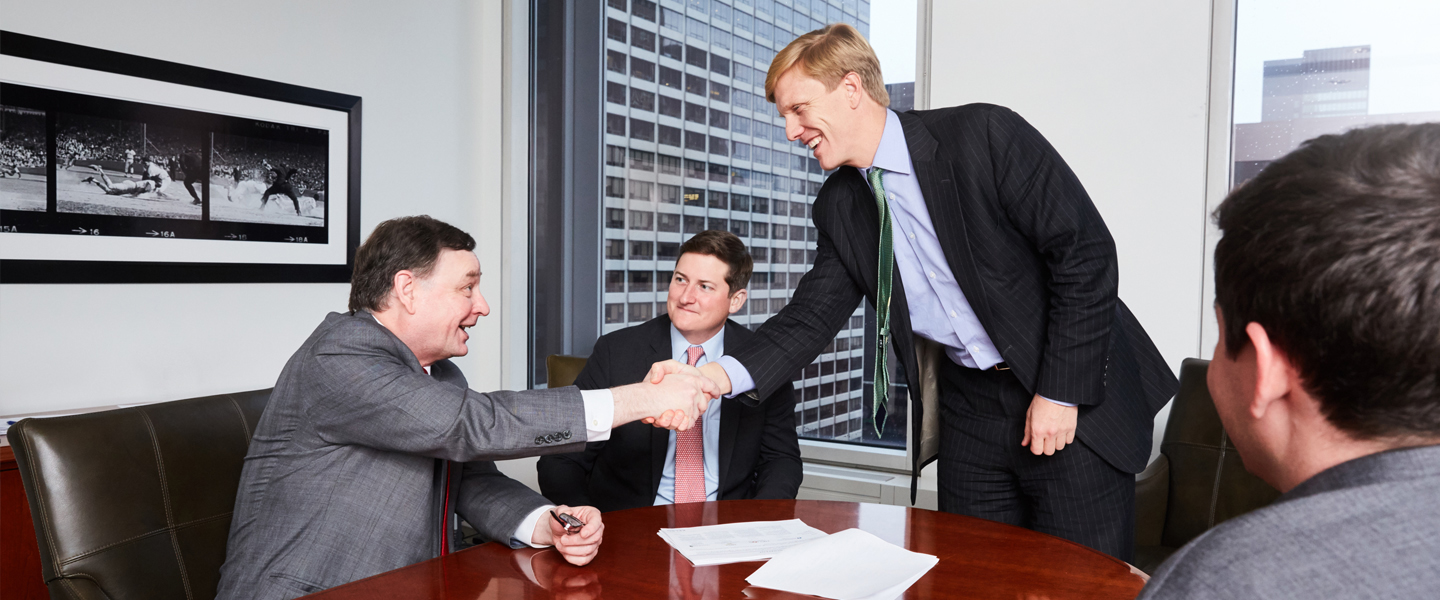
Collins’s work is shared with colleagues. Dutton co-leads Kelso’s financial-services practice and appears with him across several investment teams. Collins also shares the co-CEO title with Frank Loverro. The firm’s governance and portfolio responsibilities spread across a group of partners. Even the photograph of Collins in a meeting contains several people; a handshake is rarely a solo performance.
Beyond Kelso, Collins serves as a trustee of Brunswick School in Greenwich, belongs to Duke’s College Board of Visitors, and sits on Greenwich Youth Lacrosse’s Board of Trustees. These are specific governance commitments alongside his business roles. They add schools, a university, and youth sport to a professional record otherwise dominated by investment companies and portfolio boards.
Return to Savant, and the profile comes into focus. Collins’s name appeared beside a change in ownership, a decision about control, and an offer of resources. That is the work beneath the title. A founder wanted room to grow. An investor wanted a stake. The arrangement allowed both to take their places around the table, with the keys remaining where the announcement said they would.