Imagine a payroll team finishing its work on a Friday. The spreadsheet is complete. The instructions are sent. Somewhere else, a contractor is waiting to be paid. The work has crossed a border; the money still has appointments to keep. This is an illustrative scene, but it captures the problem BVNK sells against: a digital business can operate continuously while parts of its payment chain operate by timetable.
- BVNK connects bank money and stablecoins for business payments.
- Partners bring the infrastructure into payroll, payouts and financial apps.
- Layer1 lets customers run the technology and retain custody themselves.
- Mastercard closed the acquisition in August 2026; the announced price was up to $1.8bn.
On August 3, 2026, Mastercard completed its acquisition of BVNK. The agreement announced in March put the price at up to $1.8 billion, including $300 million in contingent payments. It buys a way to connect digital assets with the payment systems businesses already use.
BVNK provides stablecoin payment infrastructure for businesses. Stablecoins are digital tokens designed to track an asset such as the US dollar. BVNK connects those tokens, the blockchains carrying them, and conventional money. Its customers can send, receive, store and convert funds through a platform and API. A buyer need not turn its finance department into a cryptocurrency trading desk.
The company’s proposition is appealingly prosaic: let money take another route without making everyone learn a new profession. For a worker, the important screen is the one showing a spendable balance. For a business, it is the one showing that the payment arrived and the books agree.
02The customer need not know the plumbing
Consider Worldpay. In May 2025, it announced a collaboration with BVNK to offer nearly instant stablecoin payouts to its US and European clients, with a pilot expected in the second half of that year. The intended recipients included contractors, creators, sellers and customers. Businesses would access the option through their existing Worldpay payouts integration, without holding or handling the stablecoins themselves.
That last detail explains the distribution strategy. BVNK can sell to a payment company that already owns the customer relationship. A marketplace sees a familiar payout service; under the surface, a different payment rail becomes available. The benefit is judged by the delivery, rather than by the novelty of the machinery.
Payroll provides another test. In May 2026, Deel announced stablecoin salary payouts powered by BVNK and a dedicated crypto division. BVNK has separately reported 10,000 contractors opting for stablecoin payouts across 100 countries. That measures use of a particular option, rather than the entire payroll business.
Corpay’s May 2026 partnership addressed a related job: adding stablecoin wallets for global customers. The common thread is a financial product acquiring another way to move or hold money. BVNK’s customers include payment providers, fintechs, brokerages and global enterprises. The end user may encounter their employer or financial app while BVNK works underneath.
03Three founders, two kinds of money
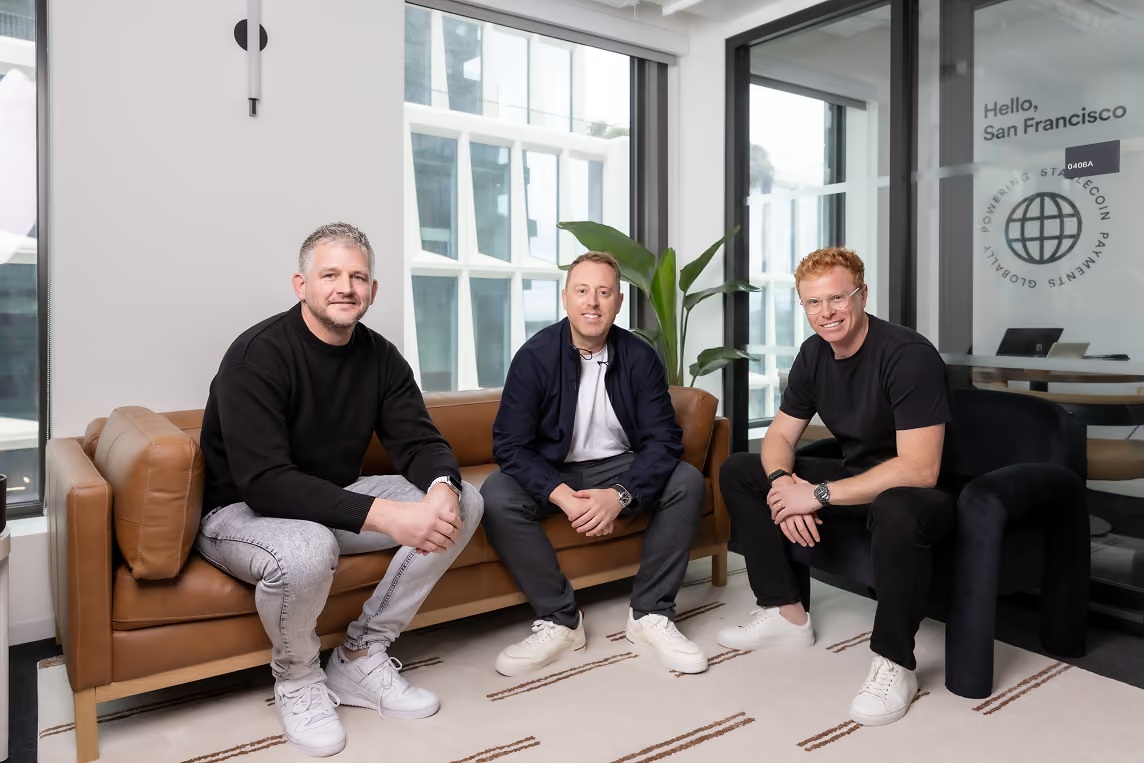
BVNK’s founding trio brought different occupations to the same problem. Jesse Hemson-Struthers, its chief executive, had built businesses in e-commerce and gaming. Donald Jackson, the chief technology officer, had founded customer-engagement and fraud-reduction businesses. Chris Harmse, the chief business officer, came from foreign-exchange trading and a macro/crypto fund.
The company’s May 2022 Series A raised $40 million, led by Tiger Global. Its announcement described an ambition to modernise international payments using both digital and fiat currencies. Funding would support market expansion, regulatory licences and product development. The bet already involved the awkward junction between systems, rather than a promise that every customer would become crypto-native.
By December 2024, BVNK reported $10 billion in annualised processing volume and raised a $50 million Series B led by Haun Ventures. Coinbase Ventures, Scribble Ventures, DRW Venture Capital, Avenir and Tiger Global participated. The announced US expansion gave the funding a concrete destination. Visa then invested in 2025; Citi Ventures followed with a strategic investment announced that October.
By September 2026, BVNK reported $39 billion in annualised volume. Annualised volume is a running pace of payments, not revenue and not necessarily the total settled during a completed year. Still, the sequence suggests why an incumbent network might want the team and technology. BVNK had become a conduit that established financial businesses were choosing to use.
Two dated snapshots. Annualised payment volume is a running rate, not revenue or a completed year’s total.
04The part that disappointed the engineers
The most revealing admission comes from Jackson’s June 2024 introduction of Layer1. Describing earlier experience with third-party infrastructure, he wrote that the team had been “frustrated or let down.” This was a specific technology complaint. Connecting to blockchain nodes meant management and maintenance; relying on wallet services brought concerns about control and privacy.
Customers wanted custody arrangements that existing options did not adequately serve, while BVNK needed infrastructure it could deploy across jurisdictions. The response was Layer1: self-hosted, self-custody payment infrastructure. It automated work such as wallet creation, reconciliation and asset management. Businesses could keep keys and data within their own environment and connect their chosen providers.
That changes the purchase decision. A managed customer buys operational help with payments. A self-managed customer buys software while retaining more responsibility. The practical choice is who will hold the keys, run the controls and handle the failure at an inconvenient hour. Owning the machinery does not make those duties disappear.
Here is the useful lesson for builders: inspect the dependencies that become painful at scale. BVNK’s published account points to maintenance, privacy and jurisdictional deployment. Layer1 turned those constraints into a product. The move makes sense when customers want control strongly enough to operate infrastructure; it is less attractive to a team whose main objective is to delegate the work.
“Our role is to make that infrastructure invisible”Chris Harmse / Marqeta partnership announcement, September 2026
05The bill survives the blockchain
What does BVNK cost? Its European pricing policy supplies a structure rather than one universal percentage. Conversion prices combine a sourced BVNK rate with an agreed commercial fee. External crypto payments can carry fixed or percentage fees, potentially tiered by volume. Blockchain charges are estimated and disclosed at the transaction, and the amount ultimately paid on-chain can differ.
That policy also allows agreed onboarding fees, monthly platform fees and minimum monthly commitments. It says crypto custody and internal wallet transfers are free within the scope of the disclosure. These terms concern its MiCA-regulated crypto services; fiat service fees sit in the client agreement. A fast payment can still have several lines on its bill.
The right buying exercise is therefore a route-specific comparison. Add conversion, network and platform charges. Measure when the recipient can actually use the money. Include reconciliation and the capital required to fund the flow. This is an editorial buying checklist, not a claim that every BVNK payment produces a saving. Cheap transport through the middle does not guarantee cheap delivery at the end.
BVNK’s own current eligibility guidance targets businesses processing at least $500,000 per month, with six months of operating history. That threshold tells you where the economics and sales process are aimed. A small shop seeking a casual crypto checkout button is looking at a different problem from an international payroll platform.
Compare the complete route. A quick middle mile can still have an expensive exit.
06A bridge has neighbours
BVNK occupies a competitive patch of financial infrastructure. Bridge offers stablecoin orchestration APIs and issuance capabilities. Zerohash offers digital-asset infrastructure spanning stablecoin payments, trading and tokenisation. Conventional bank-payment providers remain alternatives when familiar local rails already meet the job.
BVNK’s distinctive combination is its managed payment service, its self-managed Layer1 option, and its integration with bank and blockchain rails. Direct customers can use a portal or API for their treasury. Embedded partners can put payment capabilities inside their own platform, with customer onboarding built into the delivery model. Different responsibilities accompany each arrangement.
Licence coverage and security controls matter here because the software sits between real balances. BVNK reports more than 40 licences and registrations, alongside ISO 27001 and SOC certifications. Those are company disclosures, not a guarantee for every asset or every jurisdiction. BVNK explicitly says it is not a bank. Evaluating the relevant legal entity and service remains part of choosing the route.
07Mastercard buys the junction
The acquisition brings the story to a pleasingly practical turn. Mastercard’s announced rationale was interoperability across currencies, rails and regions. The purchase acknowledges that a payment network can extend its usefulness by connecting forms of money. It need not ask the customer to declare allegiance to one.
The September 2026 Marqeta partnership follows that logic. BVNK supplies stablecoin infrastructure; Marqeta handles card issuance and the associated bank and network relationships. The announced capabilities are intended to let stablecoin balances support ordinary payment cards. Merchants would continue accepting cards. Implementation and product availability, rather than the announcement alone, determine how broadly that promise becomes useful.
Later that month, BVNK integrated Stellar, adding another blockchain route through its platform and API. The integration was announced as live across its supported markets. An enterprise need not build a fresh connection to each network merely to gain another settlement option. This is where infrastructure earns its keep: it absorbs a new choice without forcing the customer to rebuild the application.
08Copy the experiment, then check the receipt
For a payments team, the sensible experiment is small and measurable: choose one troublesome payout route, specify the recipient’s desired currency, and decide whether custody should be managed or self-managed. BVNK’s developer documentation provides sandbox and production environments. Test the complete flow, including notifications and the accounting record, before treating a quick blockchain confirmation as a completed business process.
The conditions matter. A recipient who needs local currency still needs a usable exit into that currency. A company unable to complete onboarding cannot skip it by selecting a blockchain. A cheap, reliable domestic payment may offer little reason to add another provider. Self-custody also needs people capable of running it. These limits follow from the product choices and payment chain, rather than from any reported universal failure rate.
BVNK describes a distributed team across the UK, US, Europe and Africa. Its stated values include moving fast, over-delivering and being resourceful. The more useful cultural clue is what the company chose to build after infrastructure disappointed it. It made room for customers who wanted to outsource payments and customers who wanted to operate the technology themselves.
The reader can copy that habit without copying a blockchain stack: find the handoff that makes an otherwise efficient process wait. Fix the handoff, measure the whole journey, and charge for a problem somebody recognises. Saturday is free on the calendar. In a payment operation, the delay attached to it can be surprisingly expensive.
Follow the money
Explore the platform, meet the builders, or watch the plumbing explained.