The debit card was supposed to meow. This presented a modest engineering problem and a rather larger question of taste. In the summer of 2018, ANNA Money had asked a South London design agency for a hundred unusual debit-card ideas. Other companies had metal cards, bright cards, cards whose principal achievement appeared to be their own appearance. ANNA wanted a little theatre at the till.
The team considered putting a speaker and battery inside the plastic. Then an engineer observed that the app’s payment notification could make whatever sound they liked. The phone could supply the cat. An elaborate object became a small piece of software, and a purchase acquired a punchline.
Boris Diakonov, ANNA’s co-founder and co-CEO, has spent much of his working life around less entertaining parts of the payments system. His career includes internet banking, a bank’s lost licence, a new banking service built with the old team, and a British business account whose name expands to Absolutely No Nonsense Admin. The joke travels on top of a substantial amount of plumbing.
An intranet before a bank
Diakonov was born in 1977 in Sverdlovsk, now Yekaterinburg. He began studying philosophy at Ural State University before going to Centenary College of Louisiana. There he studied theology and helped build the college intranet. A student interested in religious questions found a practical occupation in connecting computers.
He graduated in 1998 and returned to Russia. His working life included being a Methodist pastor and a programmer. At Severnaya Kazna, a bank in Yekaterinburg, he worked on early internet banking. The web was becoming somewhere customers could actually transact, rather than somewhere an institution merely displayed its telephone number.
That change helps explain the continuity in a career that otherwise looks full of turns. A website could let someone do a job previously reserved for a visit, a queue, or a conversation during office hours. For a developer, the question was what the system could be made to do. For a customer, the attraction was an errand disappearing.
Severnaya Kazna
For entrepreneurs
United Kingdom
Australia
The team that crossed over
In 2002, he joined Bank24.ru and became a shareholder. His responsibilities grew from technology into running banking operations. Alongside Eduard Panteleev, he worked on the machinery that makes an account usable: information systems, card processing, a contact centre, and services for entrepreneurs.
In September 2014, Bank24.ru lost its banking licence. Diakonov and the team moved to Otkrytie, where they developed a service for small businesses called Tochka. It launched in early 2015. Biographical accounts put the team that moved at 350 people. The name and institutional arrangement changed; the accumulated knowledge travelled with them.
The episode is a useful corrective to the founder story told entirely through products. A banking service also consists of people who understand how customers work, where a payment might stall, and which explanation will make a confusing process bearable. Rebuilding requires those people as much as it requires a new screen.
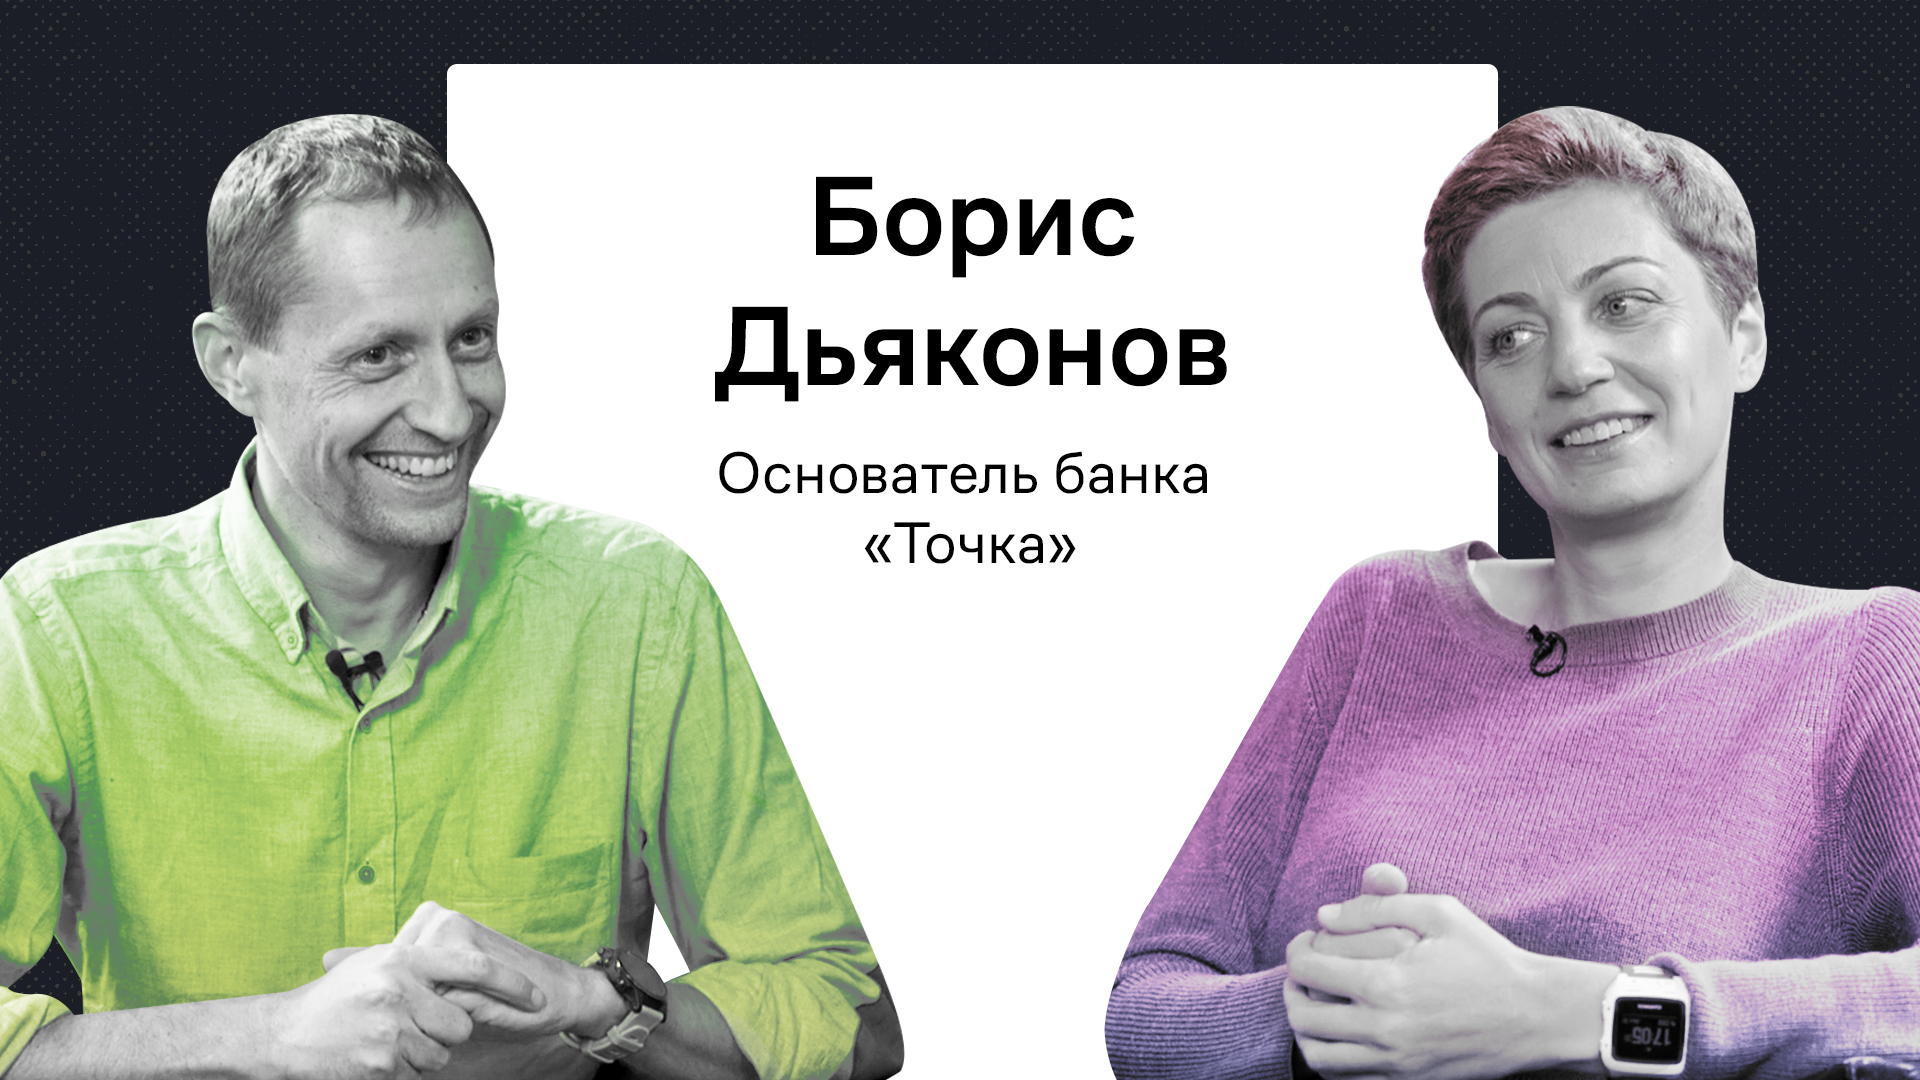
Two people in the CEO chair
Diakonov and Panteleev founded ANNA in Britain in 2017. The business account launched the following year. Their shared interest in small companies had survived a change of country. People running a business still needed to collect money, pay bills, and make sense of the accompanying paperwork.
The account was a starting point. ANNA’s chat interface let a customer ask for things in ordinary language, with software handling requests and a human support team available when needed. Over time, the service extended further into the financial chores surrounding the account. A balance is useful information. An invoice sent or a receipt dealt with is work completed.
The founders share the CEO job. Diakonov brings an IT and banking-infrastructure background; Panteleev brings experience in diplomacy and business. They describe a partnership in which different instincts contribute to common decisions. Two people can hold the same title while arriving at a problem from different directions.
There is a homely detail in Diakonov’s account of whom he admires: “You are never too important to load the office dishwasher.” It is an unusually specific answer in a field where admiration often comes with a valuation attached. Here, the proposed qualification is being useful within reach of the sink.
“It is about using the technology for the good of the people.”
Boris Diakonov
When the plumbing becomes the story
In 2020, Wirecard’s collapse pushed ANNA’s underlying payments infrastructure into the foreground. Customers temporarily could not access their money. The company faced the practical consequences of depending on a provider whose problems had suddenly become everyone else’s problem too.
ANNA moved its backend to Railsbank. Migration meant more than announcing a replacement supplier. Customers had existing cards, incoming payments, direct debits, and account details already circulating through their businesses. Those connections had to be handled while people continued trying to get through an ordinary working day.
The updates from that period show the granular work. New cards were sent in batches. Customers were told when an old card would stop working and how to keep enough money in the appropriate account. Direct debits had their own timetable. A change of infrastructure could create two accounts where the customer had previously needed to understand one.
Later updates described quicker payments and business names appearing on transfers as advantages of the new system. The improvements were tangible, but so was the inconvenience on the way there. For a founder with a technical background, this was the unromantic centre of the job: making a complicated transition intelligible to someone with other things to do.
A word he would gladly retire
Diakonov has an objection to the word fintech. In a 2025 essay, he argued that it was so broad it concealed the actual work, grouping different kinds of financial businesses into a label that said little about their customers. He had almost banned it from the office and company communications.
The irritation is revealing. He is comfortable building technology, but impatient with language that makes technology the point. A sole trader has little reason to celebrate an industry category when an invoice remains unpaid. The pitch has to survive translation into the customer’s working day.
His Payments Innovation Forum work adds another side to that argument. Appointed to its board in 2023, he has spoken about established payment infrastructure, customer care, and the responsibilities that arrive as challengers grow. A convenient interface is part of the work. Operating the service responsibly remains a continuing obligation.
In November 2024, he appeared at a Scam Safe roadshow in Cardiff, answering questions alongside ANNA colleagues. Preventing fraud involves a different sort of interface: people explaining risks to people. Even a company keen on automation has good reason to keep that conversation going.
A payment leaves paperwork behind.
- 01Get paidInvoices and payment collection
- 02Keep trackReceipts and bookkeeping
- 03Get readyTax preparation and filing
ANNA’s product direction: bring these connected jobs into the same service.
A robot at the registration desk
In August 2025, ANNA described an experiment in which an AI agent navigated its company-registration process through the web interface. The sequence included collecting details, logging in, identity verification, payment, and submitting information to Companies House. The experiment also opened a business account with a virtual card.
The company said it was working on a version of the process designed to be easier for software agents to use. This was an experiment with completing a defined administrative journey. Its interest lay in the connection between steps: a form, an identity check, a payment, a submission.
For Diakonov’s story, the distance from a college intranet is considerable, but the underlying attraction is recognisable. Computers can connect procedures that people otherwise have to shepherd themselves. The useful question is how much of that shepherding can be removed without leaving the customer confused about what has happened.
He and Panteleev continued discussing AI, tax workflows, and their shared leadership model on The Payments Shed in April 2026. The company’s direction increasingly joins financial transactions to the administrative consequences of those transactions. That gives the software more work to do, and gives its operators more responsibility for the result.
The paperwork keeps moving
ANNA’s reach has also widened geographically. Its acquisition of Australian spend-management business Cape was announced in 2024. Corporate cards and expense management brought another set of everyday business tasks into view, along with the practical demands of serving customers in a different market.
Recognition followed in Britain: ANNA placed 26th in Deloitte’s 2024 UK Technology Fast 50 and won the South West and South Wales scale-up category at the Spectator and Rathbones awards. Those are company achievements, shared across a team. They also show how far the account with the audible cat had travelled.
In September 2026, ANNA added access to revenue-based funding through YouLend. The company said 1,531 of its customers were already using that provider independently before the integration. The feature followed visible customer behaviour. Funding is supplied by YouLend and depends on eligibility; the useful editorial detail is that the demand preceded the announcement.
That leaves Diakonov with a recurring assignment. Follow the customer’s work beyond the account balance. Notice the next form, receipt, or unpaid invoice. Decide which part the service should take on. The ambition can be stated in grander language, but a finished piece of admin has an advantage over a grand statement: someone gets their evening back.