A handshake is a wonderfully photogenic thing. Two people lean across a table, the lawyers permit themselves a smile, and a transaction acquires its official expression. Andrew Weinberg’s career makes more sense if you look past that picture to the following Monday. Somebody still has to run the company. Employees need decisions. Customers expect deliveries. The founder’s children may have rather different ideas about their inheritance.
Weinberg founded Brightstar Capital Partners in 2015 after a career that took him through Morgan Stanley, Goldman Sachs and Lindsay Goldberg. Along the way, he stepped into an operating business as chief operating officer and chief strategy officer. That detour matters. It put a professional investor on the receiving end of the daily demands that investment plans create.
Today he is Brightstar’s founder, chief executive officer and co-chair, as well as chair of its investment committee. His chosen territory is the middle market, particularly businesses built by founders, families and entrepreneurs. The interesting question about him is how those two experiences, buying businesses and helping run one, fit together. His answer keeps returning to people who must keep working together after ownership changes.
Three years on the other side of the spreadsheet
Weinberg’s education paired history and economics at Dartmouth, followed by an MBA at Stanford Graduate School of Business. The combination looks apt for someone whose work involves both financial calculations and organizations with memories. A balance sheet can describe what a family owns. It takes a different conversation to understand why they might be reluctant to part with it.
He began at Morgan Stanley in mergers and acquisitions and leveraged finance, then worked in Goldman Sachs’s Principal Investment Area. He joined Lindsay Goldberg in 2003. During his time there he served on the boards of 13 portfolio companies, a succession of vantage points on how businesses behave once the financing is arranged.
Between 2008 and 2011, he also served as COO and chief strategy officer of the business now called Likewize, formerly Brightstar Corp. The dates place his operating assignment across the financial crisis and its aftermath. He worked alongside Marcelo Claure, who had founded the wireless distribution company. Their professional connection would survive the assignment and eventually become part of Weinberg’s own firm.
There is a useful distinction between presenting a strategy and being responsible for its implementation. The latter exposes the small dependencies that a presentation can glide over: the manager who needs help, the process that resists standardization, the customer whose habits refuse to obey a forecast. Weinberg’s later emphasis on operating experience has a concrete episode behind it. He has held the titles that make those dependencies somebody’s working day.
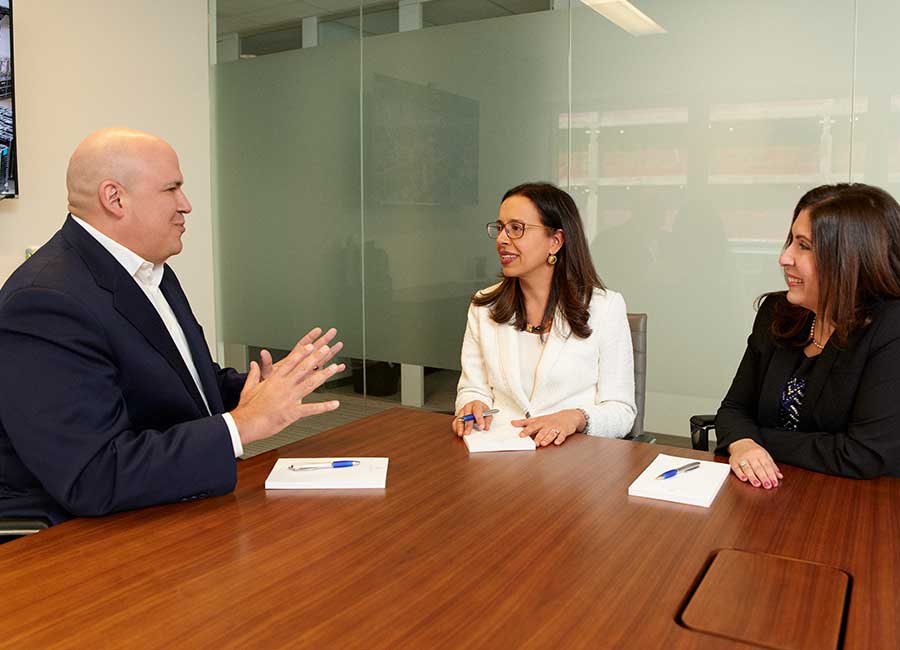
A founder meets the family business
Starting Brightstar in 2015 put Weinberg in another familiar position for his future counterparties: he was building a business himself. His customers included the owners of companies that might already represent decades of work. Offering them capital meant entering a conversation about control, continuity and what each generation wanted from the enterprise.
Brightstar calls its partnership model “Us & Us.” The phrase is short enough to fit on a meeting-room wall, where corporate philosophies often go to enjoy a quiet retirement. Its practical claim is more demanding: investors and management should approach the company as partners. For a founder weighing an ownership change, the quality of that working relationship has consequences long after the sale proceeds arrive.
In a February 2025 conversation with Nikitha Sattiraju, Weinberg discussed investing in family- and founder-owned companies approaching succession. In March, speaking with Giovanni Amodeo, he returned to the opportunities created by generational ownership changes. These are recurring questions in his public thinking, rather than a passing theme attached to a single transaction.
Succession contains several decisions that can look deceptively like one. Who owns the shares? Who runs the business? Who wants liquidity? Who wants to remain involved? In his October 2026 discussion of the subject, Weinberg emphasized creating ownership options. Separating those choices can give a family more room to act. A daughter can care deeply about a company without wanting her father’s office, calendar and entire collection of responsibilities.
The numbers come with responsibilities
The firm Weinberg built has attracted institutional capital on a substantial scale. Its second flagship fund closed in April 2021 at approximately $1.27 billion, ahead of a $1 billion target. About $60 million came from the general partner. Investors also committed another $190 million for co-investments alongside the fund.
In April 2024, Brightstar announced $1.26 billion in commitments for Fund III. These are fundraising figures, describing capital entrusted to the firm. They measure its ability to assemble backing for the strategy; the businesses still have to do the work that makes the investment worthwhile.
That distinction is central to Weinberg’s current argument. Capital can support expansion, acquisitions and management development, but each creates a set of operating tasks. An acquisition brings a new organization into the fold. Expansion asks existing systems to cope with more volume. A larger company gives its leadership more possibilities and more opportunities to discover that yesterday’s process was held together by one indispensable person.
Old colleagues, new chairs
In April 2025, Claure deepened his investment in Brightstar Capital Partners and joined as partner and co-chair. He had first invested in 2023. The reunion connected the private equity firm with an entrepreneur Weinberg had worked alongside years earlier, giving a visible example of his preference for relationships that outlast an individual deal.
Claure’s responsibilities span deal origination, capital formation and value creation. His current biography describes the two working together at Brightstar Corp. during the Great Recession. Their shared history gives the later appointment context: these were colleagues with an operating chapter already behind them.
A further appointment followed in 2026. Eric Epstein, previously partner and president at Davidson Kempner Capital Management, joined as partner and co-chair effective May 1. His remit included strategic development and engagement with limited partners. Weinberg emphasized Epstein’s experience with institutional investors and the trust between them. Building the firm now involves bringing in people equipped to manage its own growth, alongside the teams supporting portfolio companies.
“I’m a big believer in the apprentice model.”
Andrew Weinberg · October 2026
A short list beats a magnificent binder
Weinberg’s September 2026 essay on operations makes a surprisingly modest recommendation for an industry fond of elaborate plans: focus on two to four high-confidence value creation initiatives. Too many can exceed the organization’s ability to execute. Too few can leave it vulnerable when markets change. The constraint he identifies is the available talent, experience and judgment about priorities.
His examples are concrete. At America’s Group, he reported more than $12 million in operational efficiencies over the previous year and $15 million in revenue uplift through pricing and channel work. At Stratus, he described an organized acquisition-integration function. These are Brightstar’s reported examples of its approach, with the emphasis on assigning work, coordinating it and following through.
Artificial intelligence belongs in that same discussion. In his July 2025 conversation with Shiv Narayanan, Weinberg explored its use in businesses such as auto auctions and roofing, alongside preserving institutional memory. The appeal is easy to understand: existing companies have accumulated knowledge, repetitive work and difficult coordination problems. Applying new tools usefully requires understanding how those companies already function.
For Weinberg, the next stage of investing therefore reaches into the ordinary machinery of a business. A new system changes who enters information and who acts on it. An acquisition changes which colleagues need to coordinate. AI adds possibilities to that machinery, but somebody must choose the task and take responsibility for the result. His operating argument keeps the attention on that somebody.
High-confidence initiatives.
A list a team can carry.
The teacher, the apprentice and the closing credits
Asked about himself in October 2026, Weinberg described his belief in apprenticeship: “I’m a big believer in the apprentice model.” He spoke about mentors who remained involved in his life. It is an unusually practical account of a professional network, built around being able to ask for advice and receive feedback years after the original job has ended.
His public biography extends beyond the investment committee. He is a trustee of the PGA of America REACH Foundation, a member of YPO and a participant in the World Economic Forum. He has served on the forum’s investing councils and appeared at Milken Institute and FII conferences. Those connections place him in rooms where business owners, investors and policymakers exchange views on how capital gets used.
Away from work, the details become pleasantly less institutional. His stated interests include family, travel, Italian food, and films and music from the 1980s. A 2026 off-duty interview identifies teaching as his fantasy job, Hawaii as a favorite destination and golf as a way to relax. When Harry Met Sally even earns a place in the interview’s title. Private equity does occasionally allow a romantic comedy into the room.
The teaching answer is especially revealing beside the apprenticeship answer. One concerns what he might enjoy doing; the other describes how he says he learned. Together they suggest why the transfer of experience occupies so much of his thinking. The family deciding who takes over, the investor helping a management team and the junior colleague asking a mentor for advice all face a version of the same problem: how useful knowledge survives a change of hands.
Weinberg’s business is organized around such changes. A founder can step back. A former colleague can return with a new role. A company can add technology or acquire another business. Each event produces a pleasing announcement. What gives his career its through-line is his insistence on attending to the work that follows, when everyone has put the announcement away and Monday has arrived.
Conversations worth continuing
More from Weinberg, plus the announcements behind the milestones.
- Brightstar biography
- World Economic Forum
- Milken Institute
- Watch: AI and operating strategy
- Listen: succession and private equity, October 2026
- Read: the age of operations
- Interview: the middle market
- Off-duty: teaching, films and golf
- Career and personal interests
- Fund II announcement
- Fund III announcement
- Marcelo Claure’s appointment
- Eric Epstein’s appointment
- Behind the Buyouts